Automotive Door Module Market Size and Forecast (2026–2034), Global and Regional Growth, Trends, Share and Industry Analysis Report Coverage; By Component, Door Type, Vehicle Type, Mode of Operation, End User and Geography
2026-10-30
Automotive & Transportation (Mobility)
Ekta Chaurasia (Team Lead)
Description
Automotive Door Module Market Overview
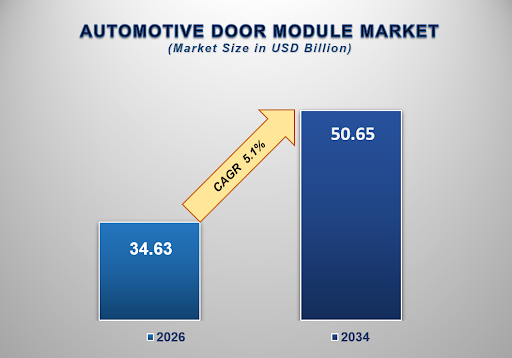
The global Automotive Door Module Market is valued at USD 34.63 billion in 2026 and is projected to reach USD 50.65 billion by 2034, registering a CAGR of 5.1% during the forecast period. Automotive door modules combine mechanical, electrical and structural components into coordinated assemblies that support door locking, window movement, sealing, access and passenger convenience. Their integration allows automakers to simplify vehicle assembly while improving consistency across different vehicle platforms.
A typical door module may include a carrier panel, window regulator, latch, actuator, wiring harness, connectors, switches and electronic controls. Depending on the vehicle, speakers, sensors and additional powered functions may also be incorporated. The final configuration varies according to vehicle class, price category, safety requirements and the features offered by the manufacturer.
Vehicle production remains the primary source of demand because door modules are supplied mainly to original equipment manufacturers (OEMs). Rising integration of power windows, electronic locking, remote access and automated closure features is increasing the functional content of many assemblies. Automakers also rely on pre-assembled modules to reduce component handling, simplify installation and maintain consistent manufacturing quality.
The transition toward electric vehicles is influencing door-system design. Manufacturers are working to reduce component weight, manage cabin noise, and integrate electronic functions more effectively. Electric vehicles may also feature advanced access systems and powered doors, although the level of automation differs by model and price segment.
Safety and durability remain essential purchasing considerations. Door latches, regulators and locking mechanisms must operate reliably through repeated use and exposure to vibration, moisture and temperature changes. Manufacturers must also address water ingress, noise, component wear and electrical reliability, making testing and quality control important parts of product development.
Another important trend is the integration of mechanical hardware with electronic controls. Functions such as anti-pinch window operation, powered closure and electronic access require coordination among motors, sensors, switches and control units. This increases the importance of supplier engineering capabilities and compatibility with the vehicle's electrical architecture.
Cost pressure continues to influence the market, particularly in entry-level vehicles. Automakers seek lighter components, lower assembly costs and fewer warranty claims while expecting suppliers to maintain strict quality standards. Suppliers must therefore balance innovation with manufacturing efficiency and competitive pricing.
Asia-Pacific is an important manufacturing region because of its automotive production base and established component supply chains. North America and Europe also contribute demand through established vehicle manufacturers, advanced vehicle features and continued development of integrated door systems. Regional growth depends on vehicle output, production investment and the specifications adopted by automakers.
Automotive Door Module Market Drivers and Opportunities
Rising Vehicle Production and Integrated Assembly Requirements Are Supporting Market Growth.
Automotive door modules are required across a broad range of passenger cars and commercial vehicles. Production growth, new model launches and vehicle-platform upgrades therefore create recurring demand for integrated door assemblies.
Pre-assembled modules can reduce the number of separate components that must be installed and handled on the vehicle assembly line. This approach can improve process consistency, simplify logistics and help automakers coordinate production schedules. Suppliers capable of delivering complete, quality-tested assemblies can consequently strengthen their relationships with vehicle manufacturers.
The opportunity is particularly relevant to suppliers operating close to automotive production facilities. Reliable deliveries, flexible manufacturing and consistent component quality are important because delays in a door module can disrupt downstream assembly operations.
Increasing Adoption of Powered Door Functions and Automotive Electronics Is Expanding Module Content.
Power windows, electronic locking, remote access and automated closure systems are increasing the functional complexity of vehicle doors. These features require reliable motors, actuators, wiring, sensors and control electronics that work together within limited space.
Higher vehicle trims often incorporate more advanced convenience features, while mainstream vehicles continue to adopt selected electronic functions as standard equipment. This creates opportunities for suppliers offering integrated systems that can be adapted to different vehicle platforms and price points.
Electric vehicles add further design considerations, including weight reduction, cabin-noise management and electronic integration. Suppliers that can deliver compact, durable and efficient components may benefit from these changing requirements.
Lightweight Materials and Intelligent Door Systems Are Creating Opportunities for Product Innovation.
Automakers are seeking ways to reduce vehicle weight without compromising structural integrity, safety or durability. Door-module suppliers can respond through optimized carrier designs, lighter materials and more efficient regulator and actuator systems.
Intelligent door functions also provide opportunities for differentiation. Improved sensing, anti-pinch protection, electronic diagnostics, and controlled closure can enhance convenience while supporting vehicle safety and reliability. Such systems require coordinated engineering rather than the addition of isolated components.
Suppliers that combine mechanical expertise with electronic integration can pursue higher-value programmes. However, adoption depends on cost, testing requirements, and the ability to maintain reliable performance over the vehicle's service life.
Automotive Door Module Market Scope
The Report Covers the Main Product, Vehicle and Geographic Dimensions of the Automotive Door Module Industry.
Automotive Door Module Market Report Segmentation Analysis
The market is segmented by component, door configuration, vehicle type, operating mode and end user. Each category reflects different requirements for durability, comfort, cost, electronic functionality and manufacturing integration.
Automated Door Modules Represent the Dominant Operating Category in a Published Market Estimate.
Automated door modules integrate powered functions such as electric window movement, electronic locking and other motorized operations. Their adoption is supported by consumer demand for convenience, broader availability of vehicle electronics and automaker efforts to standardize features across model ranges.
Manual configurations remain relevant in cost-sensitive vehicles and applications where powered functions are unnecessary. However, growing penetration of electronic access and comfort features supports demand for automated systems.
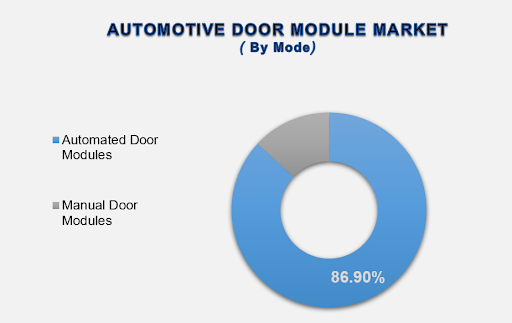
One published market estimate places automated door modules at approximately 86.9% of the combined manual and automated segment value in 2025, with manual modules accounting for the remaining 13.1%. This is an indicative segmentation reference from a separate market estimate, not a recalculation of the overall market values supplied for this report.
Latches and Handles Remain Essential to Vehicle Security and Door Functionality.
Latches and handles support door retention, opening and closing, and secure access to the vehicle. Because these components are required across vehicle categories, their design must meet demanding durability and safety requirements.
Electronic locking and powered access systems can increase integration complexity, but mechanical reliability remains essential. Suppliers compete through consistent performance, material quality and compatibility with different vehicle platforms.
Window Regulators Support Comfort and Safe Window Movement.
Window regulators guide and control the movement of vehicle glass. Manual and powered designs differ in construction, but both require stable operation and resistance to repeated use, vibration and environmental exposure.
Demand for powered windows supports the regulator segment, while anti-pinch functions and noise reduction influence product development. Compact designs are especially valuable where vehicle doors have limited internal space.
Motors and Actuators Enable Increasingly Sophisticated Door Functions.
Motors and actuators operate power windows, powered closures and other movement-related functions. Their performance affects response time, noise, energy consumption and long-term reliability.
As automakers incorporate more powered features, suppliers must optimize component size, control precision and durability. Integrated actuator systems can also reduce packaging complexity when designed for a specific vehicle platform.
Control Units and Wiring Systems Connect Mechanical Components with Vehicle Electronics.
Control units coordinate selected door functions, while connectors and wiring carry power and signals between components. Their importance increases as doors incorporate more sensors, switches and electronic features.
Suppliers must address electrical reliability, protection against moisture and compatibility with vehicle communication systems. Efficient wiring layouts and integrated controls can simplify installation and support consistent performance.
Sealing Systems and Other Components Protect Cabin Comfort and Module Reliability.
Seals help prevent water and dust ingress while contributing to noise control and cabin comfort. Carrier structures, brackets and related components provide mounting points and support the alignment of the complete assembly.
Although these parts may receive less attention than electronic functions, their performance influences durability, service requirements and overall door quality. Lightweight designs must preserve stiffness and resistance to repeated operating stresses.
The Following Segments Are Part of an In-Depth Analysis of the Global Automotive Door Module Market.
Passenger Car Door Modules Are Evolving with Comfort, Safety and Electronic Features.
Passenger cars account for demand across a wide range of module configurations, from basic locking and window systems to electronically controlled door functions. Vehicle price, body style and equipment level determine the degree of integration required.
SUVs and premium vehicles may incorporate powered liftgates, advanced access systems and additional comfort features. Compact and entry-level models, by contrast, often emphasize affordability and component standardization.
Light Commercial Vehicle Door Modules Must Balance Durability and Cost.
Light commercial vehicles are used for deliveries, passenger transport and business operations. Their door modules must withstand frequent opening and closing while maintaining reliable locking and window functions.
Manufacturers serving this category need to balance operating durability with affordable replacement and maintenance costs. Vehicle platforms designed for high utilization can create demand for dependable components and efficient servicing.
Heavy Commercial Vehicle Door Modules Prioritize Reliability and Practical Functionality.
Heavy commercial vehicles generally require door systems designed for demanding operating conditions and long service lives. Durability, secure latching and vibration resistance are important considerations.
Advanced powered features may be included depending on vehicle type and specification, but procurement decisions remain strongly influenced by reliability and cost. Standardized components can help simplify maintenance across commercial fleets.
Front and Rear Door Modules Require Different Packaging and Functional Designs.
Front door modules must accommodate driver and passenger controls, mirrors, locking systems and window mechanisms. Their design may also need to support additional electronic interfaces and ergonomic requirements.
Rear door modules focus on passenger access, window operation and secure closure. Their configurations vary by vehicle body style and can include child-safety functions and specialized locking arrangements.
Sliding and Liftgate Modules Support Specialized Vehicle Access Requirements.
Sliding door modules are particularly relevant to vans, people carriers and selected commercial vehicles. They require reliable movement mechanisms and careful control of door alignment.
Liftgate modules support access to the rear cargo area in SUVs, hatchbacks and utility vehicles. Powered liftgates add motors, sensors and control systems, creating additional integration and reliability requirements.
Original Equipment Manufacturers Remain Central to Integrated Door Module Demand.
OEMs typically source door modules as part of vehicle development and production programmes. Suppliers must meet specifications, testing requirements, delivery schedules and quality standards established by vehicle manufacturers.
Long development cycles and platform-specific engineering can create stable supply relationships, but manufacturers face continuous pricing pressure. Suppliers with global production capacity and strong technical support are often better positioned to serve large automotive customers.
Aftermarket Demand Is Supported by Repairs and Replacement of Individual Components.
The aftermarket includes replacement latches, regulators, motors, handles and related door components. Damage, wear and electrical faults can create demand throughout a vehicle's service life.
Replacing an individual component may be more economical than replacing an entire integrated module. Consequently, aftermarket opportunities depend on serviceability, parts availability and compatibility with existing vehicle models.
Automotive Door Module Market Share Analysis by Region
Regional demand is influenced by vehicle production, automotive supplier networks, consumer feature preferences and investment in vehicle technology. Manufacturing proximity is especially important because door modules are often supplied directly to vehicle assembly plants.
Asia-Pacific Remains an Important Manufacturing Base for Automotive Door Modules.
Asia-Pacific benefits from a substantial automotive manufacturing ecosystem and established networks of component suppliers. China, Japan, India and South Korea contribute through vehicle production, electronics development and automotive component manufacturing.
Growing adoption of powered features and investment in new vehicle platforms support opportunities for integrated door systems. Suppliers must nevertheless balance advanced functionality with competitive pricing, particularly in high-volume vehicle categories.
North America Supports Demand Through Established Automotive Production and Feature Integration.
North America has a mature vehicle manufacturing base, including passenger vehicles, SUVs and commercial vehicles. Demand for powered windows, electronic locking and advanced convenience features supports the use of integrated modules.
Suppliers compete through product reliability, manufacturing efficiency and close coordination with automakers. Production changes and vehicle-platform launches can create opportunities for suppliers capable of delivering customized assemblies at scale.
Europe Emphasizes Engineering Quality, Lightweighting and Advanced Vehicle Systems.
European automotive manufacturers place significant emphasis on engineering performance, safety, quality and vehicle efficiency. These requirements support continued development of lightweight door structures, efficient regulators and integrated electronic functions.
Environmental targets and the growth of electric vehicles also influence material selection and system design. Suppliers must deliver innovation while maintaining cost competitiveness and compliance with vehicle requirements.
Latin America Presents Opportunities Through Vehicle Assembly and Replacement Demand.
Latin America's automotive component market is influenced by vehicle assembly activity, domestic demand and the availability of replacement parts. Door module demand is linked to new vehicle production as well as repairs to existing fleets.
Cost-sensitive purchasing and varying local supply capabilities can affect adoption of advanced systems. Suppliers that offer reliable products at competitive prices may be better positioned to serve regional manufacturers and distributors.
The Middle East and Africa Offer Selective Opportunities in Vehicle Components and Aftermarket Services.
Demand across the Middle East and Africa is associated with vehicle imports, local assembly in selected markets and the maintenance of existing vehicle fleets. Replacement latches, regulators and other door components provide opportunities for aftermarket suppliers.
The pace of adoption of more advanced modules varies according to vehicle mix and purchasing power. Availability of compatible parts and dependable distribution remains important for both repair providers and vehicle owners.
Automotive Door Module Market Competition Landscape Analysis
The Automotive Door Module Market is characterized by automotive suppliers that combine mechanical engineering, electronics integration and high-volume manufacturing. Competition depends on product reliability, cost efficiency, design capabilities and the ability to meet demanding OEM production schedules.
Major suppliers compete to secure vehicle-platform contracts, which can require extensive validation before production begins. Once a supplier is selected, consistent quality and dependable delivery become essential to maintaining the relationship.
Key competitive priorities include:
Integrated engineering: Combining latches, regulators, motors, wiring and controls into compatible assemblies.
Lightweight design: Reducing component weight without compromising durability or safety.
Manufacturing efficiency: Improving assembly consistency and controlling production costs.
Electronic integration: Supporting powered functions, sensing and vehicle communication systems.
Quality assurance: Testing resistance to moisture, vibration, repeated operation and environmental stress.
Global supply capability: Coordinating production and delivery across multiple vehicle manufacturing locations.
The competitive landscape includes established automotive component groups and specialist suppliers. Companies with broad OEM relationships and integrated engineering capabilities can pursue larger programmes, while specialized manufacturers may compete through expertise in regulators, latches, actuators or electronic controls.
Global Automotive Door Module Recent Developments News
Automotive Suppliers Are Expanding the Integration of Mechanical and Electronic Door Functions.
Automakers increasingly expect suppliers to deliver coordinated assemblies rather than separate components. This approach can reduce assembly complexity and improve consistency, but it also requires suppliers to validate mechanical, electrical and sealing performance together.
The trend creates opportunities for companies that can combine multiple door functions within a compact and dependable module.
Electric Vehicle Development Is Influencing Door Module Design Priorities.
Electric vehicles encourage attention to weight, cabin noise and electronic functionality. Door modules must accommodate these priorities without compromising access, sealing or durability.
Manufacturers are exploring lighter structures and more integrated control systems, although implementation varies according to vehicle architecture and price category.
Automation and Electronic Access Features Are Creating Opportunities for Advanced Components.
Powered closures, electronic locking and controlled window movement increase demand for reliable motors, sensors and control systems. These features also increase the need for careful system validation.
Suppliers that can integrate these components while meeting cost and reliability targets may gain opportunities in newer vehicle programmes.
The Global Automotive Door Module Market Includes Several Established Automotive Component Suppliers.
The following companies operate in automotive door modules or related vehicle-door systems and components. Their product portfolios and level of involvement vary by market and application.
Brose Fahrzeugteile
Magna International Inc.
AISIN Corporation
Robert Bosch GmbH
Continental AG
ZF Friedrichshafen AG
Hyundai Mobis
Inteva Products
Hi-Lex Corporation
DENSO Corporation
Valeo
Toyota Boshoku Corporation
Yanfeng Automotive Interiors
FORVIA
WITTE Automotive
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
Global Automotive Door Module Market Introduction and Market Overview
Objectives of the Study
Global Automotive Door Module Market Scope and Market Estimation
Global Automotive Door Module Market Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
Global Automotive Door Module Market Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
Market Segmentation
By Component of Global Automotive Door Module Market
Latches and Handles
Window Regulators
Motors and Actuators
Control Units
Electrical Connectors and Wiring
Speakers
Sealing Systems
Others
By Door Type of Global Automotive Door Module Market
Front Door Modules
Rear Door Modules
Sliding Door Modules
Liftgate Modules
By Vehicle Type of Global Automotive Door Module Market
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
By Mode of Operation of Global Automotive Door Module Market
Manual Door Modules
Automated Door Modules
By End User of Global Automotive Door Module Market
Original Equipment Manufacturers
Aftermarket Service Providers
Region of Global Automotive Door Module Market
North America
Europe
Asia Pacific
Latin America
Middle East & Africa
Competition Coverage List of Market Participants
Market Definition: Automotive Door Module Market
Executive Summary
Demand Side Trends
Key Market Trends
Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026 – 2034
Demand and Opportunity Assessment
Key Developments
Overview of Regulatory Landscape, Compliance Framework, and Industry Standards
Market Entry Strategies
Market Dynamics
Drivers
Limitations
Opportunities
Impact Analysis of Drivers and Restraints
Porter's Five Forces Analysis
PEST Analysis
Global Automotive Door Module Market Estimates & Historical Trend Analysis (2021 – 2025)
Global Automotive Door Module Market Estimates & Forecast Trend Analysis, by Component
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by Component, 2021 - 2034
Latches and Handles
Window Regulators
Motors and Actuators
Control Units
Electrical Connectors and Wiring
Speakers
Sealing Systems
Others
ecast Trend Analysis, by DoorGlobal Automotive Door Module Market Estimates & For Type
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by Door Type, 2021 - 2034
Front Door Modules
Rear Door Modules
Sliding Door Modules
Liftgate Modules
Global Automotive Door Module Market Estimates & Forecast Trend Analysis, by Vehicle Type
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by Vehicle Type, 2021 - 2034
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
Global Automotive Door Module Market Estimates & Forecast Trend Analysis, by Mode of Operation
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by Mode of Operation, 2021 - 2034
Manual Door Modules
Automated Door Modules
Global Automotive Door Module Market Estimates & Forecast Trend Analysis, by End User
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by End User, 2021 - 2034
Original Equipment Manufacturers
Aftermarket Service Providers
Global Automotive Door Module Market Estimates & Forecast Trend Analysis, by Region
Global Automotive Door Module Market Revenue (US$ Million) Estimates and Forecasts, by Region, 2021 - 2034
North America
Europe
Asia Pacific
Middle East & Africa
Latin America
North America Automotive Door Module Market: Estimates & Forecast Trend Analysis
North America Automotive Door Module Market Assessments & Key Findings
North America Automotive Door Module Market Introduction
North America Automotive Door Module Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By Component
By Door Type
By Vehicle Type
By Mode of Operation
By End User
By Country
The U.S.
Canada
Europe Automotive Door Module Market: Estimates & Forecast Trend Analysis
Europe Automotive Door Module Market Assessments & Key Findings
Europe Automotive Door Module Market Introduction
Europe Automotive Door Module Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By Component
By Door Type
By Vehicle Type
By Mode of Operation
By End User
By Country
Germany
Italy
The U.K.
France
Spain
Switzerland
Rest of Europe
Asia Pacific Automotive Door Module Market: Estimates & Forecast Trend Analysis
Asia Pacific Automotive Door Module Market Assessments & Key Findings
Asia Pacific Automotive Door Module Market Introduction
Asia Pacific Automotive Door Module Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By Component
By Door Type
By Vehicle Type
By Mode of Operation
By End User
By Country
China
Japan
India
Australia
South Korea
Rest of Asia Pacific
Middle East & Africa Automotive Door Module Market: Estimates & Forecast Trend Analysis
Middle East & Africa Automotive Door Module Market Assessments & Key Findings
Middle East & Africa Automotive Door Module Market Introduction
Middle East & Africa Automotive Door Module Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By Component
By Door Type
By Vehicle Type
By Mode of Operation
By End User
By Country
UAE
Saudi Arabia
South Africa
Rest of Middle East & Africa
Latin America Automotive Door Module Market: Estimates & Forecast Trend Analysis
Latin America Automotive Door Module Market Assessments & Key Findings
Latin America Automotive Door Module Market Introduction
Latin America Automotive Door Module Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By Component
By Door Type
By Vehicle Type
By Mode of Operation
By End User
By Country
Brazil
Mexico
Argentina
Rest of Latin America
Competition Landscape
Global Automotive Door Module Market Product Mapping
Global Automotive Door Module Market Concentration Analysis, by Leading Players
Global Automotive Door Module Market Concentration Analysis, by Innovators
Global Automotive Door Module Market Concentration Analysis, by Emerging Players
Global Automotive Door Module Market Concentration Analysis, by New Entrants
Global Automotive Door Module Market Tier Structure Analysis
Global Automotive Door Module Market Concentration & Company Market Shares (%) Analysis, 2026
Company Profiles
Brose Fahrzeugteile
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
*Similar details would be provided for all the players mentioned below
Magna International Inc.
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
AISIN Corporation
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Robert Bosch GmbH
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Continental AG
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
ZF Friedrichshafen AG
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Hyundai Mobis
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Inteva Products
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Hi-Lex Corporation
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
DENSO Corporation
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Valeo
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Toyota Boshoku Corporation
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Yanfeng Automotive Interiors
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
FORVIA
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
WITTE Automotive
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
Research Findings & Conclusion
Assumptions & Acronyms Used
Research Methodology
External Databases
Internal Proprietary Database
Primary Research
Secondary Research
Assumptions
Limitations
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
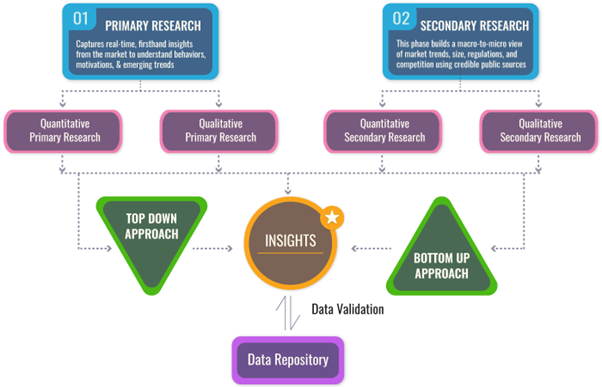
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables