Automotive Electronics Control Unit Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By ECU Capacity (16-Bit ECU, 32-Bit ECU, 64-Bit ECU); By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Electric Vehicles); By Application (Powertrain, Braking System, Body Electronics, ADAS, Infotainment); and Geography
2026-10-30
Automotive & Transportation (Mobility)
Ekta Chaurasia (Team Lead)
Description
Automotive Electronics Control Unit Market Overview
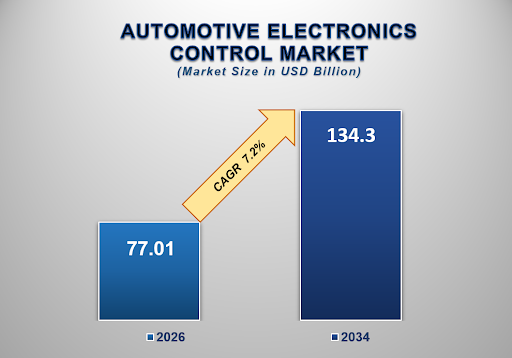
The global Automotive Electronics Control Unit Market is undergoing continued expansion as vehicle manufacturers increase electronic content across powertrain management, safety systems, body functions, infotainment, connectivity, and advanced driver-assistance systems. The market is estimated at USD 77.01 billion in 2026 and is projected to reach USD 134.30 billion by 2034, registering a CAGR of 7.2% during 2026–2034. Growth is being supported by the increasing number and sophistication of electronic functions installed in modern vehicles, growing adoption of ADAS, vehicle electrification, connected-car technologies, and the transition toward software-defined electrical/electronic architectures.
An automotive electronic control unit is an embedded computing and control module designed to receive information from sensors, process that information through programmed logic, and command vehicle components or actuators. ECUs are used across numerous vehicle functions, including engine management, transmission control, braking, steering, thermal management, lighting, body electronics, battery management, infotainment, connectivity, and driver-assistance functions. The increasing integration of electronics has consequently transformed ECUs from relatively specialized controllers into fundamental building blocks of modern vehicle architecture.
The market is also being influenced by the architectural transition from large numbers of distributed controllers toward domain and zonal architectures. Conventional vehicles can contain dozens of individual control units, while newer vehicle platforms increasingly consolidate functions into higher-performance domain controllers, zone ECUs, and centralized vehicle computers. Bosch describes this transition as a move toward vehicle-centralized, zone-oriented E/E architectures, where powerful vehicle computers interact with remaining embedded controllers through zone ECUs.
Electrification is another important factor changing ECU requirements. Battery-electric and hybrid vehicles require dedicated electronic controllers for battery management, electric motors, inverters, charging systems, thermal management, energy distribution, and regenerative braking. Consequently, electrified platforms are increasing the importance of high-performance real-time processing, functional safety, secure communications, and power-management capabilities within automotive control architectures.
ADAS is simultaneously raising the computing requirements of ECU platforms. Camera, radar, lidar, vehicle-motion, braking, steering, and driver-monitoring systems increasingly exchange large volumes of information and require rapid processing. Next-generation ECUs therefore combine more capable automotive microcontrollers and SoCs with high-speed networking, hardware security, AI acceleration, and safety mechanisms.
The evolution of software-defined vehicles is further expanding the role of ECUs. Vehicle functions are increasingly separated from fixed hardware implementations, enabling software updates, feature expansion, diagnostics, and performance improvements throughout the vehicle lifecycle. This transition is encouraging ECU suppliers and semiconductor companies to develop scalable computing platforms capable of supporting AUTOSAR-based software, centralized computing, Ethernet networking, OTA updates, and cybersecurity requirements.
Automotive cybersecurity has also become an increasingly important component of ECU development. Connected vehicles expose electronic systems to a broader digital environment, requiring secure boot, authentication, encrypted communication, intrusion detection, secure OTA mechanisms, and hardware-based security features. In March 2026, Infineon announced enhanced cybersecurity capabilities across automotive MCU families, including ISO/SAE 21434 compliance and post-quantum-cryptography-ready features for selected platforms.
Automotive Electronics Control Unit Market Drivers and Opportunities
The Expansion of Software-Defined Vehicle Architectures Is Increasing Demand for Advanced ECU Platforms
The transition toward software-defined vehicles is changing how automotive manufacturers design electrical and electronic architectures. Instead of assigning one fixed controller to every individual vehicle function, OEMs are increasingly consolidating functions into powerful domain controllers, centralized computers, and zonal control units. This architectural transition increases the processing, communication, safety, and software requirements of the remaining control platforms.
Centralized and zonal architectures require ECUs that can manage multiple functions while maintaining real-time performance and functional safety. They also require high-speed automotive Ethernet, advanced microcontrollers, system-on-chip platforms, memory, cybersecurity hardware, and sophisticated middleware. This is creating opportunities for ECU suppliers that can provide integrated hardware-software platforms rather than isolated control modules.
The transition is visible in commercial and passenger vehicle development programs. Bosch has highlighted the movement toward centralized computing platforms in which software and hardware are increasingly decoupled, while zone ECUs provide the connection between vehicle computers, sensors, actuators, and remaining embedded controllers.
NXP and Rimac Technology also demonstrated the direction of this transition in their 2025 collaboration, where the companies developed a centralized architecture capable of consolidating more than 20 electronic control units into three centralized units for next-generation software-defined vehicles.
This architectural shift does not eliminate the ECU market; instead, it changes its composition. Conventional standalone controllers are increasingly complemented or replaced by higher-performance domain and zonal controllers. Suppliers that can combine real-time processing, functional safety, cybersecurity, networking, and software compatibility are therefore positioned to participate in the higher-value portions of the ECU ecosystem.
ADAS, Vehicle Electrification and Increasing Electronic Content Are Expanding ECU Requirements
The rapid deployment of ADAS and electrified powertrains is increasing the number and sophistication of electronic control functions required within vehicles. ADAS functions such as automatic emergency braking, adaptive cruise control, lane assistance, parking assistance, blind-spot monitoring, and driver monitoring depend on continuous sensor processing and coordinated control between multiple vehicle systems.
Advanced ECUs increasingly need to process information from cameras, radar, vehicle-position sensors, wheel-speed sensors, inertial systems, and other sources while communicating commands to braking, steering, propulsion, and safety systems. This is encouraging adoption of more powerful MCUs and SoCs capable of meeting real-time processing and functional-safety requirements.
The electrification trend is creating another layer of demand. Electric vehicles require control systems for battery monitoring, state-of-charge estimation, cell balancing, traction motors, inverter management, charging, thermal systems, regenerative braking, and high-voltage safety. These requirements are increasing ECU content and expanding demand for specialized control platforms.
A March 2026 collaboration between Infineon and Subaru illustrates this trend. Infineon's AURIX TC4x MCU is being used in Subaru's next-generation integrated ECU for ADAS and vehicle-motion control, supporting sensor-data fusion and real-time decision-making.
The increasing electronics content of vehicles also extends beyond premium automobiles. Safety regulations, connectivity features, digital cockpits, electronic body systems, and driver-assistance functions are gradually reaching mid-range and mass-market vehicles. This broadens the addressable market for ECU suppliers and semiconductor manufacturers.
Opportunity: Centralized Computing, Zonal ECUs and Secure Automotive Processing Create New Revenue Pools
The migration from distributed architectures to centralized and zonal vehicle computing represents a major opportunity for ECU manufacturers and automotive semiconductor companies. Rather than competing only for individual engine, transmission, body, or infotainment controllers, suppliers can participate in higher-value computing platforms that consolidate several vehicle domains.
Centralized architectures require high-performance processors, automotive Ethernet switches, real-time MCUs, power-management devices, cybersecurity components, operating systems, middleware, and application software. This creates opportunities across the complete ECU value chain.
NXP's collaboration with Quanta in May 2026 focused on deterministic zonal networking for software-defined vehicles using the S32 automotive processing platform and MotionWise middleware. The solution is intended to provide predictable real-time communication across next-generation zonal networks.
Renesas is also developing multi-domain SoC technologies specifically for next-generation automotive ECUs. In February 2026, the company announced SoC technologies incorporating AI processing and chiplet capabilities for automotive multi-domain ECU applications.
These developments create opportunities for suppliers capable of offering scalable computing, AI acceleration, secure communications, software development environments, and functional-safety technologies. Over the longer term, the ECU opportunity is expected to increasingly shift toward integrated computing platforms that combine hardware, embedded software, networking, cybersecurity, and lifecycle update capabilities.
Automotive Electronics Control Unit Market Scope
Automotive Electronics Control Unit Market Report Segmentation Analysis
The global Automotive Electronics Control Unit Market industry analysis is segmented by ECU capacity, by vehicle type, by application, and by region. The capacity segment includes 16-bit, 32-bit, and 64-bit ECUs; the vehicle type covers passenger cars, light commercial vehicles, heavy commercial vehicles, and electric vehicles; while applications include powertrain, braking systems, body electronics, ADAS, infotainment, and other electronic functions. These segmentation categories reflect the transition from conventional vehicle controllers toward higher-performance computing platforms.
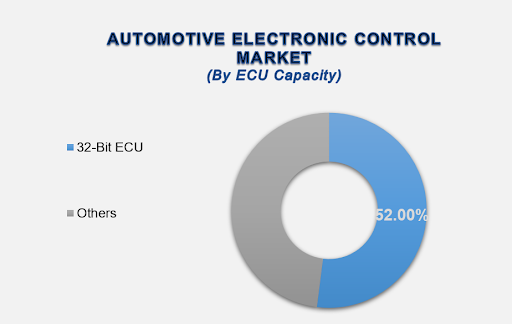
The 32-bit ECU segment represents a major portion of the market, accounting for approximately 52.0% in a current industry assessment.
The 32-Bit ECU Segment Is Expected to Dominate the Market During the Forecast Period
32-bit ECUs have established a strong position across automotive control applications because they provide a balance between processing capability, cost, memory support, real-time performance, and functional-safety requirements. They are suitable for numerous body, powertrain, chassis, transmission, thermal-management, and other embedded applications where computing requirements exceed the capabilities of older 16-bit platforms but do not necessarily justify the complexity and cost of high-end 64-bit processors.
The segment continues to benefit from the extensive installed base of automotive architectures designed around 32-bit microcontrollers. Manufacturers have developed mature development tools, software ecosystems, AUTOSAR compatibility, functional-safety frameworks, and semiconductor supply chains around these platforms.
At the same time, the market is gradually moving toward 64-bit computing for demanding ADAS, infotainment, gateway, cockpit, and centralized-domain applications. This creates a differentiated market structure in which 32-bit controllers remain important for distributed and real-time embedded functions while 64-bit platforms gain relevance for high-compute workloads.
The Passenger Car Segment Is Expected to Lead the Market by Vehicle Type
Passenger cars account for a substantial portion of ECU demand because modern passenger vehicles increasingly incorporate electronic powertrain management, digital cockpits, infotainment, ADAS, connected services, automated parking, electronic body controls, and sophisticated safety systems. A current industry assessment places passenger cars at approximately 76% of the automotive ECU market by vehicle type.
The growing electronics content of passenger vehicles is increasing ECU value per vehicle. Premium models typically introduce high-performance domain controllers, multiple ADAS systems, connected infotainment platforms, digital instrument clusters, electronic suspension and braking systems, and advanced thermal-management controls.
Mid-range vehicles are also becoming increasingly electronic as safety and connectivity features move into broader vehicle categories. This is supporting demand for cost-optimized ECUs and scalable semiconductor platforms capable of supporting common software architectures across multiple vehicle models.
Commercial vehicles represent another important market because trucks and buses require dedicated powertrain, transmission, braking, fleet-management, telematics, body-control, and safety systems. Electrification of commercial fleets is expected to further increase demand for battery, traction, charging, and thermal-control electronics.
The ADAS Application Segment Is Expected to Register Strong Growth During the Forecast Period
ADAS represents one of the most technologically dynamic application areas in the automotive ECU market. Functions such as adaptive cruise control, automatic emergency braking, lane-keeping assistance, blind-spot detection, traffic-sign recognition, parking assistance, and driver monitoring require real-time processing and communication between multiple vehicle systems.
ADAS ECUs increasingly combine high-performance processors with sensor interfaces, AI accelerators, automotive Ethernet connectivity, cybersecurity capabilities, and functional-safety mechanisms. Higher levels of driving automation also require increasingly sophisticated sensor-fusion and decision-making capabilities.
The growth of ADAS is consequently shifting ECU demand from simple control modules toward computing platforms capable of processing multiple sensor streams and coordinating vehicle responses. Renesas' 2026 multi-domain ECU technology development and Infineon/Subaru's integrated ADAS ECU work demonstrate the industry's movement toward more powerful centralized or integrated control platforms.
The following segments are part of an in-depth analysis of the global Automotive Electronics Control Unit Market:
Automotive Electronics Control Unit Market Share Analysis By Region
Asia Pacific is expected to remain a leading regional market for automotive electronic control units, supported by its large vehicle manufacturing base, expanding electric vehicle production, extensive automotive electronics supply chains, and strong presence of major vehicle and semiconductor manufacturers. Fortune Business Insights estimates that Asia Pacific accounted for approximately 46.11% of the global Automotive ECU Market in 2025.
North America
North America represents a technologically advanced market for automotive ECUs, supported by strong demand for connected vehicles, ADAS, premium vehicle electronics, electric vehicles, and software-defined vehicle technologies. The U.S. has a substantial ecosystem of automotive OEMs, Tier-1 suppliers, semiconductor companies, software developers, and autonomous-driving technology providers.
ECU demand in North America is increasingly influenced by centralized computing, vehicle cybersecurity, OTA software management, advanced cockpit systems, and high-performance ADAS platforms. The region is also an important development center for automotive AI and autonomous-driving computing.
Europe
Europe remains a major automotive electronics market due to its concentration of global automotive manufacturers and Tier-1 suppliers. Germany, France, Italy, the U.K., and other European countries are actively developing electrified and software-defined vehicle platforms.
The region's emphasis on vehicle safety, cybersecurity, emissions reduction, electrification, and advanced driver assistance supports demand for sophisticated ECU technologies. European OEMs are also investing heavily in centralized E/E architectures designed to reduce wiring complexity and enable software-driven vehicle functions.
The BMW Neue Klasse platform illustrates this transition. Infineon announced in February 2026 that its technologies support BMW's centralized computing, high-speed connectivity, and power-management architecture, including four high-performance central computing units.
Asia Pacific
Asia Pacific is the largest regional market in several current ECU market assessments, supported by vehicle production in China, Japan, India, and South Korea. The region combines high-volume passenger vehicle production with rapidly expanding electric vehicle manufacturing and a large automotive electronics supplier ecosystem.
China is particularly important because of its large automotive and EV production base and rapid adoption of connected and intelligent vehicle technologies. Japan continues to contribute through major automotive OEMs and suppliers, while South Korea has a strong position in automotive electronics and semiconductor technologies.
India represents a growing market as passenger vehicles, commercial vehicles, electric mobility, connected features, and safety electronics expand. Increasing vehicle localization and domestic automotive electronics manufacturing are also supporting the regional ecosystem.
Latin America
Latin America is developing steadily as automotive production and vehicle electronics adoption increase. Brazil and Mexico represent the region's principal automotive markets, with Mexico additionally benefiting from its role in North American automotive manufacturing.
ECU demand is supported by passenger vehicles, commercial vehicles, powertrain control, body electronics, safety systems, and increasing penetration of connected functions. Over time, the region is expected to see greater adoption of electronic architectures as global vehicle platforms introduce standardized ECU technologies.
Middle East & Africa
The Middle East & Africa market is comparatively smaller but offers opportunities associated with premium vehicles, commercial transportation, connected mobility, fleet management, and increasing vehicle electrification. Gulf countries are investing in smart mobility and EV infrastructure, which can encourage deployment of vehicles equipped with advanced electronic control functions.
South Africa remains an important automotive manufacturing center within Africa, while countries across the Middle East are gradually increasing adoption of connected and technologically advanced vehicles. Demand is expected to remain concentrated in passenger and commercial vehicles, with ADAS, infotainment, telematics, and powertrain applications representing important areas of ECU deployment.
Automotive Electronics Control Unit Market Competition Landscape Analysis
Competition in the Automotive Electronics Control Unit Market is shaped by major Tier-1 automotive suppliers, semiconductor manufacturers, automotive computing companies, and specialized electronic-system providers. Established suppliers compete through broad ECU portfolios covering powertrain, chassis, body, ADAS, infotainment, gateway, battery management, and centralized computing applications.
The competitive environment is changing as vehicle manufacturers move away from highly distributed ECU architectures. Traditional ECU suppliers are increasingly developing domain controllers, zone controllers, vehicle computers, high-performance gateways, and integrated hardware-software platforms.
Bosch is developing vehicle-centralized and zone-oriented E/E architectures designed to reduce the number of embedded control units and simplify vehicle wiring. Its approach connects powerful vehicle computers with remaining ECUs, sensors, and actuators through zone ECUs.
Infineon is expanding beyond conventional MCU supply through integrated software, cybersecurity, networking, and development ecosystems. In March 2026, the company expanded its DRIVECORE portfolio with software bundles supporting smart endpoint ECUs and AUTOSAR-based domain and zonal controllers.
Renesas is targeting the high-performance end of the market through multi-domain SoCs, AI processing, chiplet technologies, and its R-Car ecosystem. The company's Gen 5 R-Car X5H platform is designed to run multiple vehicle functions across ADAS, infotainment, and gateway applications.
NXP is similarly focusing on centralized and zonal computing through its S32 automotive processing family. Its collaborations with Rimac Technology and Quanta illustrate the industry's movement toward consolidated ECU architectures and deterministic zonal networking.
Competitive differentiation is increasingly based on processing performance, functional safety, cybersecurity, networking, AI acceleration, software compatibility, OTA capability, scalability, and the ability to support OEM-specific software architectures. Suppliers with integrated hardware-software capabilities can increasingly participate in higher-value centralized computing programs.
Global Automotive Electronics Control Unit Recent Developments News
September 2026 – Bosch advances centralized vehicle computing: Bosch highlighted its continued development of centralized E/E architectures for software-defined vehicles, including scalable vehicle computers and software platforms developed through Bosch and ETAS. The company is targeting the consolidation of previously distributed vehicle functions onto centralized computing platforms.
May 2026 – NXP and Quanta collaborate on zonal networking: NXP and Quanta announced a deterministic zonal networking platform based on NXP's S32 automotive processing platform and MotionWise middleware. The solution is designed to support predictable real-time communication in software-defined vehicle architectures.
March 2026 – Infineon expands ECU software ecosystem: Infineon introduced three DRIVECORE software bundles, including solutions for smart endpoint ECUs and AUTOSAR-based domain and zonal control ECUs. The portfolio is designed to simplify software-defined vehicle development and support future automotive MCU architectures.
March 2026 – Infineon and Subaru develop integrated ADAS ECU: Infineon and Subaru announced collaboration on an integrated ECU for next-generation ADAS and vehicle-motion control. The system uses Infineon's AURIX TC4x MCU for sensor-data fusion, real-time processing, and control functions.
February 2026 – Renesas develops multi-domain ECU SoC technologies: Renesas announced three SoC technologies for automotive multi-domain ECUs, incorporating AI processing, chiplet functions, and advanced power-control technologies for next-generation E/E architectures.
The Global Automotive Electronics Control Unit Market is Dominated by a Few Large Companies, Such As
Robert Bosch GmbH
Continental AG
DENSO Corporation
ZF Friedrichshafen AG
Valeo SE
Aptiv PLC
Hitachi Astemo
Panasonic Automotive Systems Co., Ltd.
Hyundai Mobis Co., Ltd.
Marelli Holdings Co., Ltd.
Mitsubishi Electric Corporation
NXP Semiconductors N.V.
Infineon Technologies AG
Renesas Electronics Corporation
Texas Instruments Incorporated
STMicroelectronics N.V.
Microchip Technology Inc.
Harman International
Lear Corporation
Magna International Inc.
Others
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
Global Automotive Electronics Control Unit Market Introduction and Market Overview
Objectives of the Study
Global Automotive Electronics Control Unit Market Scope and Market Estimation
Global Automotive Electronics Control Unit Market Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
Global Automotive Electronics Control Unit Market Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 20334)
Market Segmentation
By ECU Capacity of Global Automotive Electronics Control Unit Market
By Vehicle Type of Global Automotive Electronics Control Unit Market
By Application of Global Automotive Electronics Control Unit Market
Region of Global Automotive Electronics Control Unit Market
Competition Coverage List of Market Participants
Market Definition: Automotive Electronics Control Unit Market
Executive Summary
Demand Side Trends
Key Market Trends
Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026 – 2034
Demand and Opportunity Assessment
Key Developments
Overview of Regulatory Landscape, Compliance Framework, and Industry Standards
Market Entry Strategies
Market Dynamics
Drivers
Limitations
Opportunities
Impact Analysis of Drivers and Restraints
Porter's Five Forces Analysis
PEST Analysis
Global Automotive Electronics Control Unit Market Estimates & Historical Trend Analysis (2021 – 2025)
Global Automotive Electronics Control Unit Market Estimates & Forecast Trend Analysis, by ECU Capacity
Global Automotive Electronics Control Unit Market Revenue (US$ Million) Estimates and Forecasts, by ECU Capacity, 2021 - 2034
16-Bit ECU
32-Bit ECU
64-Bit ECU
Global Automotive Electronics Control Unit Market Estimates & Forecast Trend Analysis, by Vehicle Type
Global Automotive Electronics Control Unit Market Revenue (US$ Million) Estimates and Forecasts, by Vehicle Type, 2021 - 2034
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
Electric Vehicles
Global Automotive Electronics Control Unit Market Estimates & Forecast Trend Analysis, by Application
Global Automotive Electronics Control Unit Market Revenue (US$ Million) Estimates and Forecasts, by Application, 2021 - 2034
Powertrain
Braking System
Body Electronics
ADAS
Infotainment
Others
Global Automotive Electronics Control Unit Market Estimates & Forecast Trend Analysis, by Region
Global Automotive Electronics Control Unit Market Revenue (US$ Million) Estimates and Forecasts, by Region, 2021 - 2034
North America
Europe
Asia Pacific
Middle East & Africa
Latin America
North America Automotive Electronics Control Unit Market: Estimates & Forecast Trend Analysis
North America Automotive Electronics Control Unit Market Assessments & Key Findings
North America Automotive Electronics Control Unit Market Introduction
North America Automotive Electronics Control Unit Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By ECU Capacity
By Vehicle Type
By Application
By Country
The U.S.
Canada
Europe Automotive Electronics Control Unit Market: Estimates & Forecast Trend Analysis
Europe Automotive Electronics Control Unit Market Assessments & Key Findings
Europe Automotive Electronics Control Unit Market Introduction
Europe Automotive Electronics Control Unit Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By ECU Capacity
By Vehicle Type
By Application
By Country
Germany
Italy
The U.K.
France
Spain
Switzerland
Rest of Europe
Asia Pacific Automotive Electronics Control Unit Market: Estimates & Forecast Trend Analysis
Asia Pacific Automotive Electronics Control Unit Market Assessments & Key Findings
Asia Pacific Automotive Electronics Control Unit Market Introduction
Asia Pacific Automotive Electronics Control Unit Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By ECU Capacity
By Vehicle Type
By Application
By Country
China
Japan
India
Australia
South Korea
Rest of Asia Pacific
Middle East & Africa Automotive Electronics Control Unit Market: Estimates & Forecast Trend Analysis
Middle East & Africa Automotive Electronics Control Unit Market Assessments & Key Findings
Middle East & Africa Automotive Electronics Control Unit Market Introduction
Middle East & Africa Automotive Electronics Control Unit Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By ECU Capacity
By Vehicle Type
By Application
By Country
UAE
Saudi Arabia
South Africa
Rest of Middle East & Africa
Latin America Automotive Electronics Control Unit Market: Estimates & Forecast Trend Analysis
Latin America Automotive Electronics Control Unit Market Assessments & Key Findings
Latin America Automotive Electronics Control Unit Market Introduction
Latin America Automotive Electronics Control Unit Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
By ECU Capacity
By Vehicle Type
By Application
By Country
Brazil
Mexico
Argentina
Rest of Latin America
Competition Landscape
Global Automotive Electronics Control Unit Market Product Mapping
Global Automotive Electronics Control Unit Market Concentration Analysis, by Leading Players / Innovators / Emerging Players / New Entrants
Global Automotive Electronics Control Unit Market Tier Structure Analysis
Global Automotive Electronics Control Unit Market Concentration & Company Market Shares (%) Analysis, 2026
Company Profiles
Robert Bosch GmbH
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
*Similar details would be provided for all the players mentioned below
Continental AG
DENSO Corporation
ZF Friedrichshafen AG
Valeo SE
Aptiv PLC
Hitachi Astemo
Panasonic Automotive Systems Co., Ltd.
Hyundai Mobis Co., Ltd.
Marelli Holdings Co., Ltd.
Mitsubishi Electric Corporation
NXP Semiconductors N.V.
Infineon Technologies AG
Renesas Electronics Corporation
Texas Instruments Incorporated
STMicroelectronics N.V.
Microchip Technology Inc.
Harman International
Lear Corporation
Magna International Inc.
Others
Research Findings & Conclusion
Assumptions & Acronyms Used
Research Methodology
External Databases
Internal Proprietary Database
Primary Research
Secondary Research
Assumptions
Limitations
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
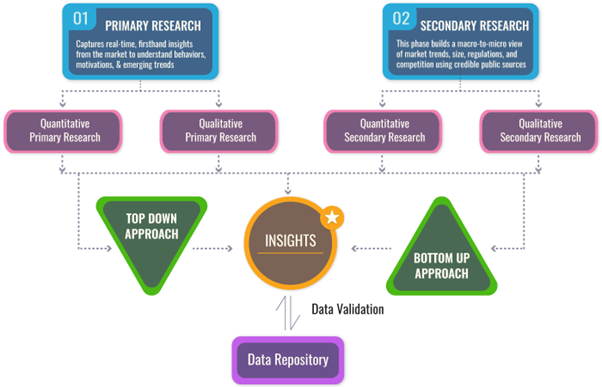
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables