Carbon Nano Tubes Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By Product (Multi-Walled Carbon Nanotubes (MWCNT) and Single-Walled Carbon Nanotubes (SWCNT)); By Method (Chemical Vapor Deposition (CVD), Catalytic Chemical Vapor Deposition (CCVD), High-Pressure Carbon Monoxide Reaction, and Others); By Application (Plastics & Composites, Electrical & Electronics, Energy, and Others); By End User (Automotive, Aerospace, Electronics & Semiconductors, Energy & Batteries, Healthcare, Construction, and Others); and Geography
2026-09-25
Chemicals & Materials
Aishwarya Panbude (Research Analyst)
Description
Carbon Nano Tubes Market Overview
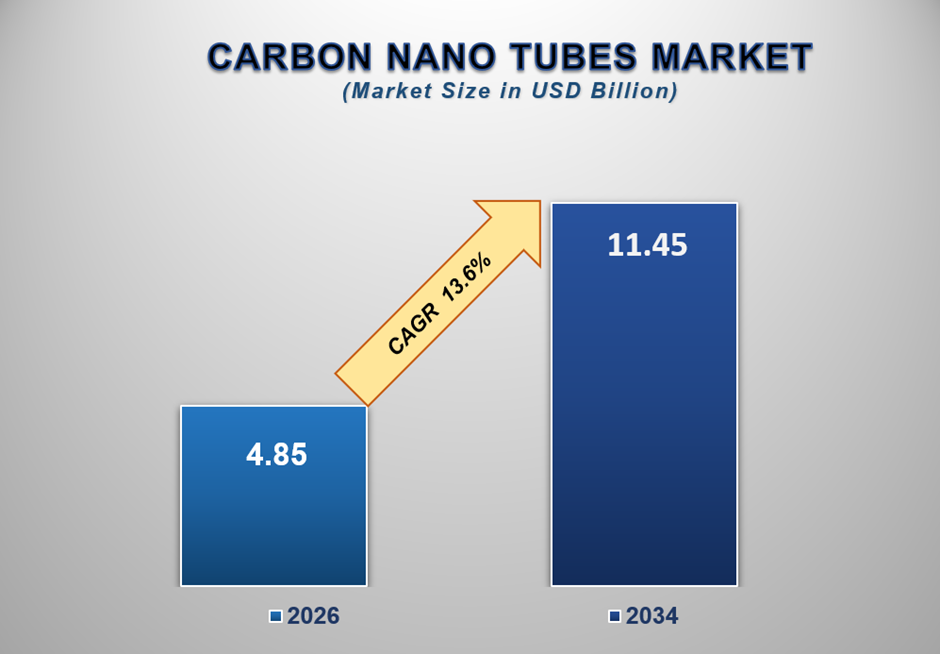
The global Carbon Nano Tubes Market was valued at USD 4.85 billion in 2026 and is projected to reach USD 11.45 billion by 2034, expanding at a CAGR of 13.6% during the forecast period. The market is experiencing strong growth due to increasing demand for lightweight and high-strength materials, expanding applications of conductive additives in batteries and electronics, rising adoption of advanced polymer composites, growing electric vehicle production, increasing semiconductor manufacturing, and continuous advancements in nanotube synthesis, dispersion, and functionalization technologies.
Carbon nanotubes are cylindrical carbon-based nanostructures characterized by a high aspect ratio and a combination of electrical, thermal, mechanical, and structural properties. They are generally categorized into single-walled carbon nanotubes and multi-walled carbon nanotubes, with each structure offering different performance and cost characteristics for industrial applications. CNTs are increasingly incorporated into polymers, composites, battery electrodes, electronic components, coatings, and other advanced materials. Recent market assessments identify plastics and composites, electrical and electronics, and energy among the principal application areas for carbon nanotubes.
The growing
requirement for materials that combine low weight with mechanical strength and
electrical conductivity is creating substantial demand for CNTs. When
incorporated into polymers and composite materials, carbon nanotubes can
improve mechanical performance and provide electrical conductivity, making them
suitable for applications where conventional materials may not deliver the
required combination of properties.
The automotive
industry represents an important demand center because manufacturers are
increasingly focused on reducing vehicle weight while maintaining structural
performance and incorporating electrically functional materials. CNT-enhanced
polymers and composites can be used in applications requiring electrostatic
dissipation, conductivity, reinforcement, thermal management, and
electromagnetic shielding. The increasing development of electric vehicles is
further expanding the opportunity for CNTs through their use in battery
electrodes and conductive additives.
The battery
industry is becoming one of the most strategically important growth areas for
carbon nanotubes. CNTs can form conductive networks within battery electrodes,
allowing efficient electron transport at relatively low loading levels. This is
particularly relevant to high-energy-density lithium-ion batteries,
silicon-containing anodes, nickel-rich cathodes, solid-state batteries, and
other emerging energy-storage chemistries. Recent research continues to
investigate CNTs as conductive additives and structural scaffolds for lithium,
sodium, potassium, and other advanced battery systems.
The electronics
and semiconductor industries are also increasing their use of CNT-based
materials because of their electrical conductivity, thermal properties, high
aspect ratio, and potential for miniaturized electronic architectures. CNTs can
contribute to conductive plastics, electromagnetic shielding, sensors,
field-emission devices, semiconductor manufacturing equipment, and other
specialized electronic applications.
Advancements in
manufacturing are helping address one of the historical limitations of carbon
nanotubes: achieving consistent quality, purity, dispersion, and cost-effective
large-scale production. Chemical vapor deposition and related catalytic
processes have become important commercial production methods, while
manufacturers continue to improve catalyst systems, reactor designs,
purification, functionalization, and dispersion technologies.
The development
of CNT dispersions is particularly important for industrial adoption. Carbon
nanotubes have a tendency to agglomerate because of their nanoscale structure
and high surface interactions. Effective dispersion allows manufacturers to
distribute CNTs more uniformly within polymers, battery slurries, coatings, and
other matrices, improving the consistency of the final material.
The energy
transition is further broadening the addressable market. CNTs are increasingly
being evaluated for lithium-ion batteries, silicon-based anodes, solid-state
batteries, supercapacitors, fuel cells, solar technologies, and other energy
applications. OCSiAl, for example, states that its single-walled nanotubes are
being used in battery technologies, including silicon-rich anodes,
single-crystal NCM cathodes, dry electrodes, and solid-state batteries.
As manufacturers
continue to scale production and improve CNT quality, the material is moving
from a specialized nanotechnology product toward a broader industrial input for
advanced composites, energy storage, electronics, automotive components,
aerospace materials, and other high-performance applications. This expansion is
expected to maintain strong growth in the carbon nanotubes market through 2034.
Carbon Nano Tubes Market Drivers and
Opportunities
Increasing
Demand for High-Performance Lightweight Materials Is Driving Market Growth
The increasing
demand for lightweight, strong, electrically conductive, and thermally
efficient materials is one of the primary factors driving the carbon nanotubes
market.
Automotive and
aerospace manufacturers are continuously seeking ways to reduce component
weight without compromising structural performance. CNTs can be incorporated
into polymer matrices and composite materials to improve mechanical strength
while adding electrical or thermal functionality.
The automotive
industry is particularly important because vehicle manufacturers are under
increasing pressure to improve energy efficiency and reduce vehicle weight.
Electric vehicles further increase the importance of lightweight materials
because reducing vehicle mass can contribute to improved energy efficiency and
driving range.
CNT-enhanced
polymers can also provide electrostatic dissipation and electromagnetic
shielding, making them suitable for automotive electronic components and other
electrically sensitive applications. Carbon nanotube-reinforced composites are
therefore being considered for applications extending beyond conventional
structural reinforcement.
Aerospace
applications offer another high-value opportunity because aircraft
manufacturers prioritize lightweight materials with high strength-to-weight
ratios. CNTs can potentially contribute to advanced composite systems,
conductive structures, thermal-management materials, and electromagnetic
shielding.
The broader
advanced-materials industry is also increasing its interest in CNTs as
manufacturers develop engineered plastics and composite materials for demanding
operating environments. Market research identifies lightweighting, advanced
composites, automotive applications, aerospace applications, and
high-performance materials as important factors supporting CNT demand.
Growing
Demand for Conductive Additives in Batteries and Electronics Is Supporting
Market Expansion
The rapid
development of electric vehicles, energy-storage systems, portable electronics,
and advanced electronic devices is significantly increasing demand for
conductive carbon materials.
CNTs are
particularly attractive for battery applications because their high aspect
ratio allows them to create interconnected conductive pathways within electrode
materials. This can improve electron transport while requiring relatively low
quantities of conductive additive compared with conventional carbon materials
in certain formulations.
The importance
of CNTs is increasing as battery manufacturers adopt higher-energy-density
materials. Silicon-based anodes, for example, can offer greater theoretical
capacity than conventional graphite but experience substantial volume changes
during cycling. CNT networks can help maintain electrical connectivity as
electrode structures expand and contract.
CNTs are also
being evaluated in next-generation batteries. Research published in 2026
highlights their potential in lithium-, sodium-, and potassium-ion systems
because of their electrical conductivity, mechanical resilience, tunable
surface chemistry, and ability to support stable conductive architectures.
Battery
manufacturers and CNT suppliers are therefore investing in specialized
dispersions and higher-performance nanotube formulations. LG Chem supplies CNT
grades designed for lithium-ion battery conductive additives, while Cabot
offers ENERMAX carbon nanotubes and carbon nanostructures for battery
applications.
The electronics
industry is another important growth area. CNTs can be used in conductive
polymers, sensors, electronic components, thermal-management systems,
semiconductor-related materials, and electromagnetic shielding. The increasing
miniaturization of electronics is creating demand for materials capable of
delivering high conductivity and functionality at low material loadings.
Expansion of
Advanced Battery Technologies and CNT-Based Functional Materials Presents
Significant Opportunities
The expansion of
advanced battery technologies presents substantial opportunities for carbon
nanotube manufacturers.
CNTs are
increasingly being incorporated into high-silicon anodes, high-nickel cathodes,
dry electrodes, solid-state batteries, lithium-sulfur batteries, and other
emerging energy-storage technologies. Their ability to establish conductive
networks and provide structural support makes them attractive as battery
manufacturers seek higher energy density and improved cycle performance.
The transition
toward dry-electrode manufacturing could create additional demand for CNT-based
conductive architectures because manufacturers are seeking electrode designs
that can reduce processing complexity while maintaining conductivity and
mechanical integrity.
CNT suppliers
are also developing customized dispersions rather than selling only dry
nanotube powders. These formulations can simplify integration into battery
slurries, polymer matrices, and coatings, creating additional value beyond the
underlying nanotube material.
OCSiAl has
expanded its European production infrastructure around single-wall carbon
nanotube dispersions, while its Serbia facility has been developed to support
high-performance battery manufacturing. The company has also announced further
European expansion associated with advanced battery supply chains.
Beyond
batteries, opportunities exist in conductive polymers, semiconductor equipment,
thermal interface materials, electromagnetic shielding, sensors, filtration,
biomedical systems, and aerospace composites. As manufacturing technologies
improve and costs decline, CNTs are expected to penetrate applications that
previously relied on carbon black, metallic fillers, conventional fibers, or
other conductive materials.
|
Report
Attributes |
Description |
|
Market Size
in 2026 |
USD 4.85 Billion |
|
Market
Forecast in 2034 |
USD
11.45 Billion |
|
CAGR %
2026-2034 |
13.6% |
|
Base Year |
2025 |
|
Historic
Data |
2021-2025 |
|
Forecast
Period |
2026-2034 |
|
Report USP |
Production,
Consumption, Company Share, Company Heatmap, Company Production, Service
Type, Growth Factors and more |
|
Segments
Covered |
• By
Product • By Method • By
Application • By End
User |
|
Regional
Scope |
● North America |
|
Country
Scope |
U.S. |
The global
carbon nano tubes market industry analysis is segmented by product, by method,
by application, by end user, and by region.
The
Multi-Walled Carbon Nanotubes Segment Is Expected to Dominate the Market During
the Forecast Period
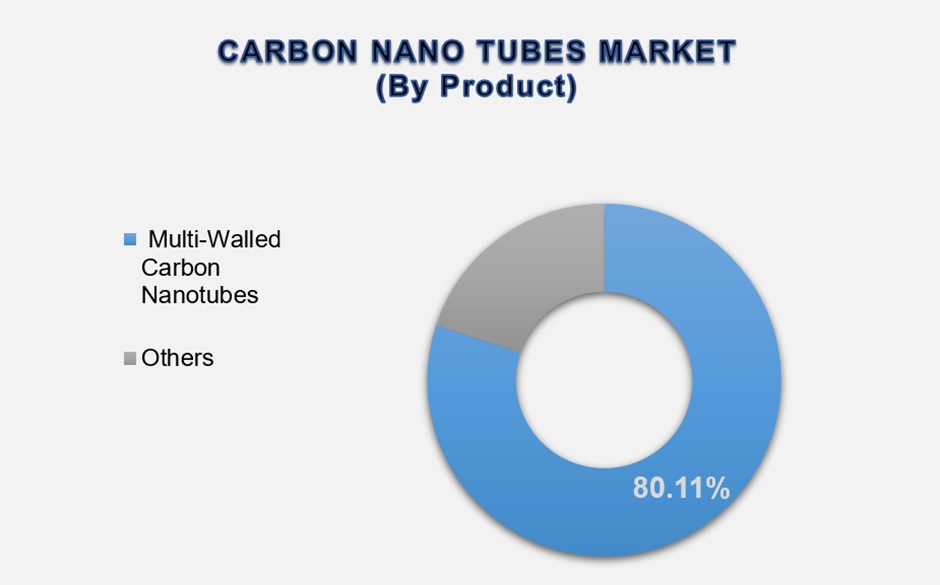
The Multi-Walled
Carbon Nanotubes (MWCNT) segment is expected to dominate the global carbon
nanotubes market, accounting for approximately 80.11% of the market in
2026.
MWCNTs consist
of multiple concentric graphene-like cylindrical walls and generally provide a
combination of electrical conductivity, mechanical reinforcement, thermal
performance, and cost efficiency.
Their
comparatively favorable production economics and broad compatibility with
polymers and composite materials make MWCNTs particularly attractive for
high-volume industrial applications.
MWCNTs are
widely used in engineered plastics, rubber compounds, automotive materials,
construction composites, coatings, conductive materials, and energy-storage
applications. Their ability to improve electrical conductivity and mechanical
properties without requiring large quantities of additive supports their use in
industrial formulations.
The growing
adoption of CNT-enhanced composites and conductive additives is expected to
maintain the dominance of MWCNTs during the forecast period.
The Chemical
Vapor Deposition Segment Is Expected to Hold a Significant Share of the Market
by Method
The Chemical
Vapor Deposition (CVD) segment represents a significant share of the carbon
nanotubes market because of its suitability for scalable CNT synthesis and its
ability to provide control over nanotube growth conditions.
CVD-based
processes use carbon-containing feedstocks and catalysts to grow nanotubes
under controlled temperature and reaction conditions. The method can be adapted
to different production scales and is widely investigated and utilized for
industrial CNT manufacturing.
Advancements in
catalysts, reactor configuration, feedstock utilization, purification, and
process control are improving production efficiency and material consistency.
Catalytic
chemical vapor deposition is also important because catalyst composition and
process parameters can influence nanotube diameter, wall structure, morphology,
purity, and yield.
As manufacturers
seek higher production volumes and consistent material characteristics, CVD and
related catalytic processes are expected to remain important commercial
production technologies.
The Plastics
& Composites Segment Is Expected to Dominate the Market by Application
The Plastics
& Composites segment accounted for approximately 69.2% of the
global carbon nanotubes market in 2026, making it the leading application
category.
CNTs are
increasingly incorporated into engineering polymers and composite materials to
improve mechanical strength, electrical conductivity, thermal characteristics,
and durability.
Automotive
manufacturers use advanced polymer materials to reduce component weight while
maintaining functionality. CNT-based additives can also provide electrostatic
discharge and electromagnetic shielding capabilities, which are increasingly
relevant as vehicles incorporate more electronic systems.
In aerospace,
CNT-enhanced composites can support lightweight structures and electrically
functional components. Construction and industrial applications similarly
benefit from conductive and mechanically reinforced polymer systems.
The electrical
and electronics application is expected to record strong growth as demand rises
for conductive materials, sensors, thermal-management components,
semiconductor-related products, and advanced electronic devices.
The
Automotive Segment Is Expected to Hold a Significant Share of the Market by End
User
The Automotive
segment represents a major end-user category because manufacturers are
increasingly adopting lightweight materials, electrically conductive polymers,
electromagnetic shielding materials, and advanced battery technologies.
CNTs can support
multiple automotive requirements simultaneously, including weight reduction,
electrical conductivity, static dissipation, thermal management, and battery
performance.
The expansion of
electric vehicles is particularly important because CNTs are increasingly used
as conductive additives in lithium-ion battery electrodes. CNT networks can
help maintain electrical conductivity while supporting high-energy-density
electrode materials.
Other end users,
including aerospace, electronics and semiconductors, energy and batteries,
healthcare, and construction, are also expanding their use of CNT-enabled
materials as nanotechnology moves into increasingly specialized applications.
The following segments are part of an in-depth analysis of the global Carbon Nano Tubes Market:
|
Market Segments |
|
|
By Product |
- Multi-Walled
Carbon Nanotubes (MWCNT) - Single-Walled
Carbon Nanotubes (SWCNT) |
|
By
Method |
- Chemical Vapor
Deposition (CVD) - Catalytic
Chemical Vapor Deposition (CCVD) - High-Pressure
Carbon Monoxide Reaction - Others |
|
By Application |
- Plastics &
Composites - Electrical &
Electronics - Energy - Others |
|
By End User |
- Automotive - Aerospace - Electronics
& Semiconductors - Energy &
Batteries - Healthcare - Construction - Others |
Carbon Nano Tubes Market Share
Analysis By Region
Asia Pacific is projected to hold the largest share of the global carbon
nanotubes market over the forecast period.
Asia Pacific
accounted for approximately 39.0% of the global carbon nanotubes market
in 2025, supported by strong manufacturing activity, advanced electronics
production, expanding electric vehicle and battery industries, growing polymer
and composite manufacturing, and significant investment in nanotechnology.
China represents one of the most important markets in the region because
of its large battery, electronics, automotive, semiconductor, plastic, and
advanced-materials manufacturing base. The country is also becoming
increasingly important for CNT dispersion and battery-grade conductive additive
production. OCSiAl's licensed Chinese partners have been expanding CNT
dispersion capacity to address demand from battery manufacturers.
Japan and South Korea are major contributors due to their advanced
electronics, automotive, semiconductor, battery, and chemical industries. South
Korea is particularly important because of its battery-material ecosystem and
domestic CNT production. LG Chem has developed large-scale CNT manufacturing
capabilities for battery and polymer applications.
India is expected to experience increasing demand as domestic automotive,
electronics, renewable-energy, aerospace, and advanced-materials industries
expand. Growing interest in local manufacturing and high-performance materials
is expected to create additional opportunities for CNT applications.
Europe represents a significant market due to strong automotive,
aerospace, battery, electronics, chemical, and research industries. Germany,
France, the U.K., Italy, Spain, and Switzerland are important markets. The
region is also becoming strategically important for CNT-based battery supply
chains as manufacturers seek localized sources of advanced conductive
materials.
North America is expected to experience robust growth due to advanced polymer
research, aerospace and defense manufacturing, electric vehicle development,
semiconductor investment, and increasing adoption of CNT-based conductive
materials. The United States represents the dominant regional market.
Latin America is expected to experience steady growth as automotive production,
industrial manufacturing, electronics, construction, and energy-storage
applications expand. Brazil and Mexico represent key markets within the region.
The Middle
East & Africa represents an emerging market
supported by increasing industrial diversification, advanced-material research,
renewable-energy investment, and growing demand for high-performance polymer
and composite materials. The UAE and Saudi Arabia provide important
opportunities through industrial modernization and advanced manufacturing
initiatives.
Carbon Nano
Tubes Market Competition Landscape Analysis
The global
carbon nanotubes market is competitive, with companies focusing on production
scalability, purity, dispersion quality, nanotube morphology,
application-specific formulations, and supply reliability.
Major market
participants include LG Chem, OCSiAl, Arkema, Cabot Corporation, Nanocyl,
Jiangsu Cnano Technology, Kumho Petrochemical, Resonac/Showa Denko, Hyperion
Catalysis International, Canatu, and other specialist CNT manufacturers.
LG Chem has
established a strong position through large-scale CNT production and its
integration with the battery-materials value chain. The company's CNT portfolio
includes grades designed for lithium-ion battery conductive additives as well
as plastics and rubber applications. LG Chem reports operating CNT capacity at
its Yeosu facilities and has continued developing high-conductivity and
high-dispersion CNT products.
OCSiAl competes
primarily in the single-walled carbon nanotube segment and has developed
industrial-scale production and dispersion capabilities. Its European
operations support applications across batteries, polymers, and advanced
materials, while the company continues to expand its presence in the EV battery
supply chain.
Cabot
Corporation competes through a portfolio of conductive carbons, carbon
nanotubes, and carbon nanostructures. Its ENERMAX CNT products are positioned
for lithium-ion battery applications, while its technology centers support
development of specialized CNT materials and conductive dispersions.
Arkema and
Nanocyl maintain strong positions through specialty nanomaterial technologies
and industrial customer relationships. Jiangsu Cnano and other Asian
manufacturers benefit from proximity to the world's major battery, electronics,
and polymer-processing industries.
Competitive
differentiation is increasingly shifting toward application-specific CNT
solutions rather than generic nanotube supply. Battery manufacturers
require controlled dispersion, consistent purity, suitable morphology, and
reliable large-scale supply, while polymer manufacturers may prioritize cost,
processing compatibility, conductivity, and reinforcement performance.
The ability to
provide customized dispersions, technical support, application development, and
stable long-term supply is therefore becoming increasingly important. As demand
expands into advanced batteries and electronics, manufacturers with strong production
capabilities and established customer qualification processes are expected to
gain competitive advantages.
Global Carbon
Nano Tubes Market Recent Developments News
●
In April 2026 – LG Chem highlighted the growing role of carbon nanotubes in
electric vehicle batteries, particularly as conductive additives for cathodes
and as conductive-network stabilizers for silicon-based anodes. The company
emphasized CNTs' role in supporting battery conductivity, capacity, charging
performance, and lifespan.
●
In November 2025 – OCSiAl announced the development of a flagship graphene nanotube
production facility in Luxembourg as part of a reported USD 300 million
investment, strengthening its European advanced-materials and battery
supply-chain presence.
●
In October 2025 – OCSiAl's Serbia production facility achieved ISO 9001, ISO 14001,
and ISO 45001 integrated management certifications, strengthening its quality,
environmental, and occupational-safety framework for industrial nanotube
production.
●
In 2025-2026 – Research activity continued to advance CNT-based battery
architectures, including their use in silicon-rich anodes, high-loading
electrodes, lithium-ion systems, and other next-generation energy-storage
technologies. Recent studies have focused on improving CNT dispersion,
conductive-network formation, cycling stability, and scalability.
The Global
Carbon Nano Tubes Market is Dominated by a Few Large Companies, Such As
●
LG Chem Ltd.
●
OCSiAl
●
Arkema S.A.
●
Cabot Corporation
●
Nanocyl SA
●
Jiangsu Cnano Technology Co.,
Ltd.
●
Kumho Petrochemical Co., Ltd.
●
Resonac Holdings Corporation
●
Hyperion Catalysis
International
●
Canatu Oy
●
Nano-C
●
Meijo Nano Carbon Co., Ltd.
●
Zeon Corporation
●
Chengdu Organic Chemicals Co.,
Ltd.
●
Shenzhen Sanshun Nano New
Materials Co., Ltd.
● Others
Frequently Asked Questions
Aishwarya Panbude (Research Analyst)
Aishwarya Panbude is a skilled Research Analyst with 4+ years of experience in market intelligence, consumer insights, competitive analysis, and industry forecasting across the consumer goods, agriculture, and food & beverage sectors. She specializes in market sizing, trend analysis, growth opportunity mapping, and strategic secondary research for global and regional markets.
Her expertise lies in transforming complex industry data into actionable business strategies that help organizations identify emerging trends, understand customer behavior, and gain a competitive edge. With a strong focus on data-driven insights, business intelligence, and future market trends, Jaya delivers high-quality research solutions aligned with evolving industry demands and market dynamics.
1.
Global Carbon Nano Tubes
Market Introduction and Market Overview
1.1. Objectives of the Study
1.2. Global Carbon Nano Tubes Market Scope and Market Estimation
1.2.1.
Global Carbon Nano Tubes Market
Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
1.2.2.
Global Carbon Nano Tubes Market
Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
1.3. Market Segmentation
1.3.1.
By Product of Global Carbon
Nano Tubes Market
1.3.2.
By Method of Global Carbon Nano
Tubes Market
1.3.3.
By Application of Global Carbon
Nano Tubes Market
1.3.4.
By End User of Global Carbon
Nano Tubes Market
1.3.5.
Region of Global Carbon Nano
Tubes Market
1.4. Competition Coverage List of Market Participants
1.5. Market Definition: Carbon Nano Tubes Market
2.
Executive Summary
2.1. Demand Side Trends
2.2. Key Market Trends
2.3. Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026
– 2034
2.4. Demand and Opportunity Assessment
2.5. Key Developments
2.6. Overview of Regulatory Landscape, Compliance Framework, and Industry
Standards
2.7. Market Entry Strategies
2.8. Market Dynamics
2.8.1.
Drivers
2.8.2.
Limitations
2.8.3.
Opportunities
2.8.4.
Impact Analysis of Drivers and
Restraints
2.9. Porter's Five Forces Analysis
2.10.
PEST Analysis
3.
Global Carbon Nano Tubes
Market Estimates & Historical Trend Analysis (2021 – 2025)
4.
Global Carbon Nano Tubes
Market Estimates & Forecast Trend Analysis, by Product
4.1. Global Carbon Nano Tubes Market Revenue (US$ Million) Estimates and
Forecasts, by Product, 2021 - 2034
4.1.1.
Multi-Walled Carbon Nanotubes
(MWCNT)
4.1.2.
Single-Walled Carbon Nanotubes
(SWCNT)
5.
Global Carbon Nano Tubes
Market Estimates & Forecast Trend Analysis, by Method
5.1. Global Carbon Nano Tubes Market Revenue (US$ Million) Estimates and
Forecasts, by Method, 2021 - 2034
5.1.1.
Chemical Vapor Deposition (CVD)
5.1.2.
Catalytic Chemical Vapor
Deposition (CCVD)
5.1.3.
High-Pressure Carbon Monoxide
Reaction
5.1.4.
Others
6.
Global Carbon Nano Tubes
Market Estimates & Forecast Trend Analysis, by Application
6.1. Global Carbon Nano Tubes Market Revenue (US$ Million) Estimates and
Forecasts, by Application, 2021 - 2034
6.1.1.
Plastics & Composites
6.1.2.
Electrical & Electronics
6.1.3.
Energy
6.1.4.
Others
7.
Global Carbon Nano Tubes
Market Estimates & Forecast Trend Analysis, by End User
7.1. Global Carbon Nano Tubes Market Revenue (US$ Million) Estimates and
Forecasts, by End User, 2021 - 2034
7.1.1.
Automotive
7.1.2.
Aerospace
7.1.3.
Electronics &
Semiconductors
7.1.4.
Energy & Batteries
7.1.5.
Healthcare
7.1.6.
Construction
7.1.7.
Others
8.
Global Carbon Nano Tubes
Market Estimates & Forecast Trend Analysis, by Region
8.1. Global Carbon Nano Tubes Market Revenue (US$ Million) Estimates and
Forecasts, by Region, 2021 - 2034
8.1.1.
North America
8.1.2.
Europe
8.1.3.
Asia Pacific
8.1.4.
Middle East & Africa
8.1.5.
Latin America
9.
North America Carbon
Nano Tubes Market: Estimates & Forecast Trend Analysis
9.1. North America Carbon Nano Tubes Market Assessments & Key
Findings
9.1.1.
North America Carbon Nano Tubes
Market Introduction
9.1.2.
North America Carbon Nano Tubes
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
9.1.2.1.
By Product
9.1.2.2.
By Method
9.1.2.3.
By Application
9.1.2.4.
By End User
9.1.2.5.
By Country
9.1.2.5.1.
The U.S.
9.1.2.5.2.
Canada
10. Europe Carbon Nano Tubes Market: Estimates & Forecast Trend
Analysis
10.1.
Europe Carbon Nano Tubes Market
Assessments & Key Findings
10.1.1.
Europe Carbon Nano Tubes Market
Introduction
10.1.2.
Europe Carbon Nano Tubes Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
10.1.2.1.
By Product
10.1.2.2.
By Method
10.1.2.3.
By Application
10.1.2.4.
By End User
10.1.2.5.
By Country
10.1.2.5.1.
Germany
10.1.2.5.2.
Italy
10.1.2.5.3.
The U.K.
10.1.2.5.4.
France
10.1.2.5.5.
Spain
10.1.2.5.6.
Switzerland
10.1.2.5.7.
Rest of Europe
11. Asia Pacific Carbon Nano Tubes Market: Estimates & Forecast
Trend Analysis
11.1.
Asia Pacific Carbon Nano Tubes
Market Assessments & Key Findings
11.1.1.
Asia Pacific Carbon Nano Tubes
Market Introduction
11.1.2.
Asia Pacific Carbon Nano Tubes
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
11.1.2.1.
By Product
11.1.2.2.
By Method
11.1.2.3.
By Application
11.1.2.4.
By End User
11.1.2.5.
By Country
11.1.2.5.1.
China
11.1.2.5.2.
Japan
11.1.2.5.3.
India
11.1.2.5.4.
Australia
11.1.2.5.5.
South Korea
11.1.2.5.6.
Rest of Asia Pacific
12. Middle East & Africa Carbon Nano Tubes Market: Estimates &
Forecast Trend Analysis
12.1.
Middle East & Africa Carbon
Nano Tubes Market Assessments & Key Findings
12.1.1.
Middle East & Africa Carbon
Nano Tubes Market Introduction
12.1.2.
Middle East & Africa Carbon
Nano Tubes Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
12.1.2.1.
By Product
12.1.2.2.
By Method
12.1.2.3.
By Application
12.1.2.4.
By End User
12.1.2.5.
By Country
12.1.2.5.1.
UAE
12.1.2.5.2.
Saudi Arabia
12.1.2.5.3.
South Africa
12.1.2.5.4.
Rest of Middle East &
Africa
13. Latin America Carbon Nano Tubes Market: Estimates & Forecast
Trend Analysis
13.1.
Latin America Carbon Nano Tubes
Market Assessments & Key Findings
13.1.1.
Latin America Carbon Nano Tubes
Market Introduction
13.1.2.
Latin America Carbon Nano Tubes
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
13.1.2.1.
By Product
13.1.2.2.
By Method
13.1.2.3.
By Application
13.1.2.4.
By End User
13.1.2.5.
By Country
13.1.2.5.1.
Brazil
13.1.2.5.2.
Mexico
13.1.2.5.3.
Argentina
13.1.2.5.4.
Rest of Latin America
14. Competition Landscape
14.1.
Global Carbon Nano Tubes Market
Product Mapping
14.2.
Global Carbon Nano Tubes Market
Concentration Analysis, by Leading Players / Innovators / Emerging Players /
New Entrants
14.3.
Global Carbon Nano Tubes Market
Tier Structure Analysis
14.4.
Global Carbon Nano Tubes Market
Concentration & Company Market Shares (%) Analysis, 2026
15. Company Profiles
15.1.
LG Chem Ltd.
15.1.1.
Company Overview & Key
Stats
15.1.2.
Financial Performance &
KPIs
15.1.3.
Product Portfolio
15.1.4.
SWOT Analysis
15.1.5.
Business Strategy & Recent
Developments
*Similar details would be provided for all
the players mentioned below
15.2.
OCSiAl
15.3.
Arkema S.A.
15.4.
Cabot Corporation
15.5.
Nanocyl SA
15.6.
Jiangsu Cnano Technology Co.,
Ltd.
15.7.
Kumho Petrochemical Co., Ltd.
15.8.
Resonac Holdings Corporation
15.9.
Hyperion Catalysis
International
15.10.
Canatu Oy
15.11.
Nano-C
15.12.
Meijo Nano Carbon Co., Ltd.
15.13.
Zeon Corporation
15.14.
Chengdu Organic Chemicals Co.,
Ltd.
15.15.
Shenzhen Sanshun Nano New
Materials Co., Ltd.
15.16.
Others
16. Research Findings & Conclusion
17. Assumptions & Acronyms Used
18. Research Methodology
18.1.
External Databases
18.2.
Internal Proprietary Database
18.3.
Primary Research
18.4.
Secondary Research
18.5.
Assumptions
18.6.
Limitations
18.7.
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
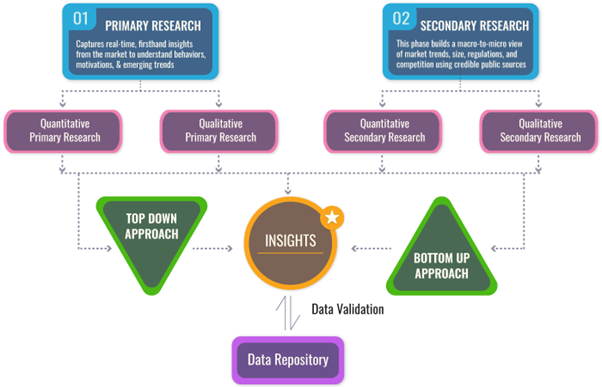
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables