France Biochip Market Size and Forecast (2026–2034), Regional Growth, Trend, Share and Industry Analysis Report Coverage: By Type (DNA Chips, Protein Chips, Lab-on-a-Chip (LOC), Cell Arrays, Others); By Product (Consumables, Instruments, Software and Services); By Application (Disease Diagnostics, Drug Discovery and Development, Genomics, Agricultural Biotechnology, Others); By End User (Biotechnology and Pharmaceutical Companies, Hospitals and Diagnostic Centers, Academic and Research Institutes, Others)
2026-11-17
Healthcare
Swetal (Research Analyst)
Description
France Biochip Market Overview
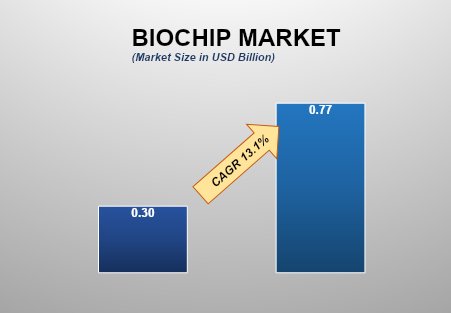
The France biochip market is projected to expand from USD 0.30 billion in 2026 to USD 0.77 billion by 2034, registering a CAGR of 13.1% during 2026–2034. The market for biochips in France benefits from the country’s well-established biotech, pharmaceutical, clinical diagnostics, and life sciences sectors that develop numerous technologies for genomics, proteomics, molecular diagnostics, and drug development. Since there is a need for DNA and protein chips, lab-on-chip technologies, genetic testing, and precision medicine, companies and research labs are starting to use biochips. The country strives to develop organ-on-chip and organoid-on-chip technologies, which allow biochip producers to focus on preclinical drug testing and new methods of personalized medicine. For instance, in the PEPR MED-OOC program (funded by France 2030), €48.4 million will be invested within six years. At the same time, high costs of developing new technologies, complicated production processes, and difficulties of standardization can affect commercialization.
France Biochip Market Growth Drivers
Strong Domestic In-Vitro Diagnostics Manufacturing Base
The excellent IVD manufacturing environment in France can make an excellent foundation for biochip technology's implementation and commercialization. According to DGE, France has around 100 IVD companies, the vast majority of which are SMEs. Such a diversified range of manufacturers results in a variety of diagnostic product developers and proof-of-concept manufacturers in the field of molecular testing.
The presence of local producers gives rise to the demand for biochips for multiplex immunoassays, authenticating pathogens, genetic testing, and automation of diagnostics. For example, NG Biotech, the manufacturer from France, exceeded 4 million tests produced per month in 2026 with two facilities located in Guipry-Messac. The company has its own proprietary immunoassay method, proving the efficiency of the French diagnostic technicians. Although not all of NG Biotech test devices rely on biochip technology, such production demonstrates proper infrastructure available to the French diagnostics industry.
Government Support for Organ-on-Chip and Advanced In-Vitro Technologies
In France, government-backed initiatives and research programs are advancing the development of technologies such as organ-on-chip, microfluidic, and organoid technologies. The France 2030 investment initiative, in particular, promotes research commercialization, transfer of technologies, and the development of alternative testing technologies for pharmaceutical purposes. For instance, the PEPR MED-OOC research program has been supported with €48.4 million over 6 years in order to enhance organ-on-chip and organoid-on-chip technologies. In addition, a specific France 2030 call for projects aimed at demonstrating the significance of organs-on-chips and organoids in preclinical research and precision medicine has been launched in July 2026. The France 2030 initiative fosters collaboration between industry, research centers, and healthcare facilities to achieve practical and reproducible applications. These programs are promoting the development of the biochip technology industry in France and opening the doors for manufacturers supplying microfluidic devices, organ-based chips, and testing technologies.
France Biochip Market Restraint
Limited Scalability of Specialized Biochip Manufacturing
Producing specialized biochips, especially related to organ-on-chip technology and microfluidic devices, necessitates intricate production processes, perfect conception of channels, integration of biological materials, conditions for cell cultivation, and other procedures ensuring proper quality control. Transitioning from lab-scale prototypes to commercial products is challenging. The architecture of the chip as well as the cell source, method of testing, and environmental conditions may change the quality of production. As an illustration, the French Organoids and Organs-on-Chip Initiative (F3OCI), in its November 2025 industry white paper, identified technology industrialization, the quality of the process, regulatory transparency, and standardization to be the key areas for the development of the local industry. The roadmap included the adoption of the OECD’s Good In Vitro Method Practices (GIVIMP) methodology and strengthening the validation protocols. The OECD published the second edition of its GIVIMP recommendations in December 2025, which reinforces the need to apply consistent practices for the generation of reliable and reproducible in vitro test results. These events show that manufacturers need to resolve issues with technological consistency and validation before biochip technologies can be widely used.
France Biochip Market Opportunities
Industrialization of Organ-on-Chip Technologies for Pharmaceutical Applications
The shift from experimental organ-on-chip devices to mass-produced commercial products represents an opportunity for French biochip firms. As pharmaceutical companies seek human-relevant in vitro models to test drugs for their toxicity, efficacy, metabolism, and tissue-specific responses in preclinical development, the manufacturers will be able to commercialize their platforms. Consequently, French biochip manufacturers will be able to produce standard microfluidic chips, interconnected tissue models, cell culture modules, disposable cartridges, and relevant analysis systems. For instance, in February 2025, NETRI opened the first organ-on-chip production facility in Lyon, France, covering more than 1,100 square meters of laboratories equipped for microfabrication in cleanroom conditions and controlled cell culture. This new facility is supposed to provide ten times the company’s current production capacity, enabling the production and operation of up to 500,000 devices per year at full production level. NETRI has also raised 5 million Euros in funding and benefited from the 4.8 million Euro AXONE project as part of the First Factory France 2030 initiative. This marks a step towards industrial-level production of organs on chips in France. The potential for such investment in organs-on-chips technology has also been made apparent due to the call for France 2030, which took place in July 2026. This provides funds for collaborative demonstration of the application of organoids and organs-on-a-chip for use in pharmaceutical research and precision medicine.
France Biochip Market Scope
France Biochip Market Report Segmentation Analysis
DNA Chips Segment Is Expected to Dominate the France Biochip Market During the Forecast Period
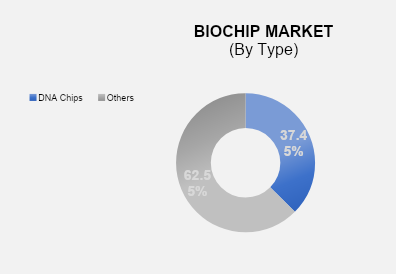
The DNA chips sub-segment is predicted to take over the French Biochip Market due to rising use of genomics profiling, gene expression analysis, genotyping, and molecular marker detection for both pharma industry research and clinical diagnostic purposes. As more and more emphasis is being laid on genomics research, together with the concept of personalized medicines in the country, increasing demand is being witnessed for DNA microarrays which can analyze many genes at once. Increasing applications of such microarrays are seen in oncological research, genetic disease testing, infectious disease evaluation, and drug target validation. With increased availability of microarray platforms and analytical tools, their usage is also increasing in high-throughput applications. Rising investment from the pharmaceutical industry in the field of genomics-based drug discovery and development will support demand for DNA chips in the coming years.
Consumables Segment Is Expected to Dominate the France Biochip Market During the Forecast Period
The consumables category is anticipated to hold the leading position within the France Biochip Market, due to the recurring need for assay reagents, microarray slides, diagnostic cartridges, sample preparation kits, buffers, and other disposable consumables. The biochip experiments and diagnostic procedures necessitate the use of special consumables for the processing of samples, detecting biological compounds, and analysis, thus causing repeat purchase demand. The rise in the use of DNA microarrays, multiplex immunoassays, and microfluidic diagnostic devices leads to an increase in demand for the related reagents and disposable biochips. Moreover, the adoption of organ-on-chip solutions in the development of pharmaceuticals also creates demand for the consumables needed in the process. The consumables have more purchase demand than capital-intensive instruments and equipment.
Disease Diagnostics Segment Is Expected to Dominate the France Biochip Market During the Forecast Period
The segment for disease diagnostics is set to be led by the rising utilization of biochips in detecting infectious diseases, diagnosing cancer biomarkers, genetic disorders, and molecular testing. The strong in-vitro diagnostics industry in France, along with homegrown diagnostic players, will aid in the advancement and uptake of integrated testing solutions utilizing biochip technology. Multiplex platforms help in the simultaneous identification of several pathogens, genetic markers, and disease-associated proteins. This helps in making testing faster and cuts out the need for conducting multiple tests. There will be increasing focus on early diagnosis and molecular characterization, due to which there will be increased adoption of advanced platforms for analysis. Increasing demand for fast molecular testing and biomarker analysis is set to further reinforce the leadership of the disease diagnostics segment.
Biotechnology and Pharmaceutical Companies Segment Is Expected to Dominate the France Biochip Market During the Forecast Period
The biotech and pharmaceutical companies sector is likely to be the dominant force in the France Biochip Market. This will happen because of the strong pharmaceutical research and development base in France, its biotechnology innovation platform, and increasing funding in innovative therapies. These organizations employ DNA chips, protein chips, and biochip microfluidics to conduct drug discovery, gene expression profiling, target validation, biomarker discovery, compound testing, and preclinical toxicity testing. The increasing development of biologics, RNA therapies, and precision medicine has increased demand for advanced molecular and cellular analysis systems. Further, expanding organ-on-a-chip and organoid platforms have raised the demand for specialized biochips to simulate the reactions of human organs to drugs. The increasing needs for high-throughput analysis, reproducibility, and improved preclinical tests will keep this sector at the forefront among end-users in France.
The following segments are part of an in-depth analysis of the France Biochip Market:
France Biochip Market Competition Landscape Analysis
The France Biochip Market is moderately fragmented, with participation from multinationals in life science and diagnostics, along with specialist French companies for the development of technology. The companies include Agilent Technologies, Thermo Fisher Scientific, Bio-Rad Laboratories, Illumina, Abbott, QIAGEN, Revvity, Roche, bioMérieux, and HORIBA, all of which leverage the existing portfolio and strong ties with pharma and research institutes. Specialist French firms like NETRI, Innobiochips, and Cherry Biotech distinguish themselves based on organ-on-chip technology, microfluidics, and novel biological models. Development by NETRI of a 2025 production facility in Lyon and the CEA-Leti’s association with Infiplast show how much effort has been put into industrializing these technologies.
France Biochip Market Recent Developments News:
In September 2026, Innobiochips completed the development of its expanded facilities at the Hub Eurasanté in France to support its growth in multiplex in-vitro diagnostics. The company develops and manufactures diagnostic platforms designed to extract multiple biological insights from a single sample, strengthening its position in high-definition diagnostics.
In May 2026, bioMérieux announced an investment of more than €250 million in a new manufacturing facility at La Balme-les-Grottes, France, for its BIOFIRE PCR test portfolio. Scheduled to become operational in 2030, the facility is intended to strengthen European diagnostic supply capacity and expand the company's domestic manufacturing footprint
The France Biochip Market is dominated by a few large companies, such as
Innobiochips
NETRI
Cherry Biotech
Eden Tech
NG Biotech
Bio-Rad Laboratories, Inc.
Standard BioTools Inc.
Revvity, Inc.
Abbott Laboratories
bioMérieux SA
HORIBA Ltd.
Siemens Healthineers AG
Becton, Dickinson and Company
Hologic, Inc.
QIAGEN N.V.
Other Prominent Players
Frequently Asked Questions
Swetal (Research Analyst)
Swetal is a Research Analyst with 4+ years of experience specializing in healthcare market research, medical devices, healthcare IT, and medical technology industry analysis. Her expertise includes competitive intelligence, secondary research, market trend forecasting, and healthcare business insights across global healthcare ecosystems.
She contributes to advanced market research reports by analyzing regulatory frameworks, emerging healthcare technologies, competitive landscapes, and innovation trends shaping the medical industry. With a strong focus on accurate market intelligence, strategic insights, and healthcare industry trends, Swetal supports businesses in making informed, data-backed decisions in a rapidly transforming healthcare environment.
France Biochip Market Introduction and Market Overview
Objectives of the Study
Market Segmentation
Type of the France Biochip Market
Products of the France Biochip Market
Application of the France Biochip Market
End User of the France Biochip Market
Competition Coverage List of Market Participants
Market Definition: Biochip Market
Executive Summary
France Biochip Market Estimation & Forecast
France Biochip Market Size (US$ Million) Estimates & Historical Trend Analysis (2021 - 2025)
France Peptide Cancer Vaccine Overall Market Size (US$ Million), Growth Rate (Y-o-Y), Market CAGR (%), Market Forecast (2026 - 2034)
Snapshot of France Biochip Market
France Biochip Market Revenue Share (%) 2025
Key Competitors & Key Insights
Market Overview (Qualitative Analysis)
Demand Side Trends
Supply Side Trends / Manufacturing Trends
Demand and Opportunity Assessment, 2026 - 2034
Market Dynamics
Drivers
Limitations
Opportunities
Impact Analysis of Drivers and Restraints
Key Developments
Regulatory Landscape
Pricing Analysis
Supply Chain Analysis
Porter’s Five Forces Analysis
Bargaining Power of Suppliers
Bargaining Power of Buyers
Threat of Substitutes
Threat of New Entrants
Competitive Rivalry
PEST Analysis
Political Factors
Economic Factors
Social Factors
Technology Factors
France Biochip Market Estimates & Forecast Trend Analysis, by Type
France Biochip Market Assessments & Key Findings, by Type
France Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Type, 2021 - 2034
Protein Chips
Lab-on-a-Chip (LOC)
Cell Arrays
Others
France Biochip Market Estimates & Forecast Trend Analysis, by Product
France Biochip Market Assessments & Key Findings, by Product
France Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Product, 2021 - 2034
Consumables
Instruments
Software and Services
France Biochip Market Estimates & Forecast Trend Analysis, by Application
France Biochip Market Assessments & Key Findings, by Application
France Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Application, 2021 - 2034
Disease Diagnostics
Drug Discovery and Development
Genomics
Agricultural Biotechnology
Others
France Biochip Market Estimates & Forecast Trend Analysis, by End User
France Biochip Market Assessments & Key Findings, by End User
France Biochip Market Revenue (US$ Million) Estimates and Forecasts, by End User, 2021 - 2034
Biotechnology and Pharmaceutical Companies
Hospitals and Diagnostic Center
Academic and Research Institutes
Others
Competition Landscape
France Biochip Market Product Mapping
France Biochip Market Concentration Analysis, by Leading Players / Innovators / Emerging Players / New Entrants
France Biochip Market Tier Structure Analysis
France Biochip Market Concentration & Company Market Shares (%) Analysis, 2025
Company Profiles
Innobiochips
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
* Similar details would be provided for all the players mentioned below
NETRI
Cherry Biotech
Eden Tech
NG Biotech
Bio-Rad Laboratories, Inc.
Standard BioTools Inc.
Revvity, Inc.
Abbott Laboratories
bioMérieux SA
HORIBA Ltd.
Siemens Healthineers AG
Becton, Dickinson and Company
Hologic, Inc.
QIAGEN N.V.
Other Prominent Players
Research Findings & Conclusion
Assumptions & Acronyms Used
Research Methodology
External Transportation / Databases
Internal Proprietary Database
Primary Research
Secondary Research
Assumptions
Limitations
Report FAQs
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
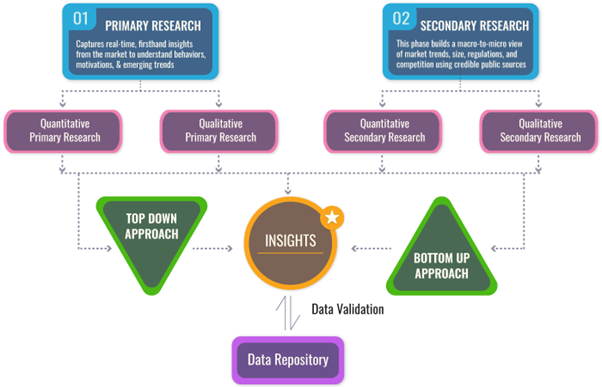
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables