France Food Robotics Market Size and Forecast (2026–2034), Regional Growth, Trend, Share and Industry Analysis Report Coverage: By Type (Articulated Robots, SCARA Robots, Delta Robots, and Collaborative Robots); By Application (Food Processing, Packaging, Palletizing, Sorting & Grading, and Others); By End User (Food Manufacturers, Food Service Providers, Beverage Industry, and Others)
2026-09-16
ICT
Ekta Chaurasia (Team Lead)
Description
France Food Robotics Market Overview
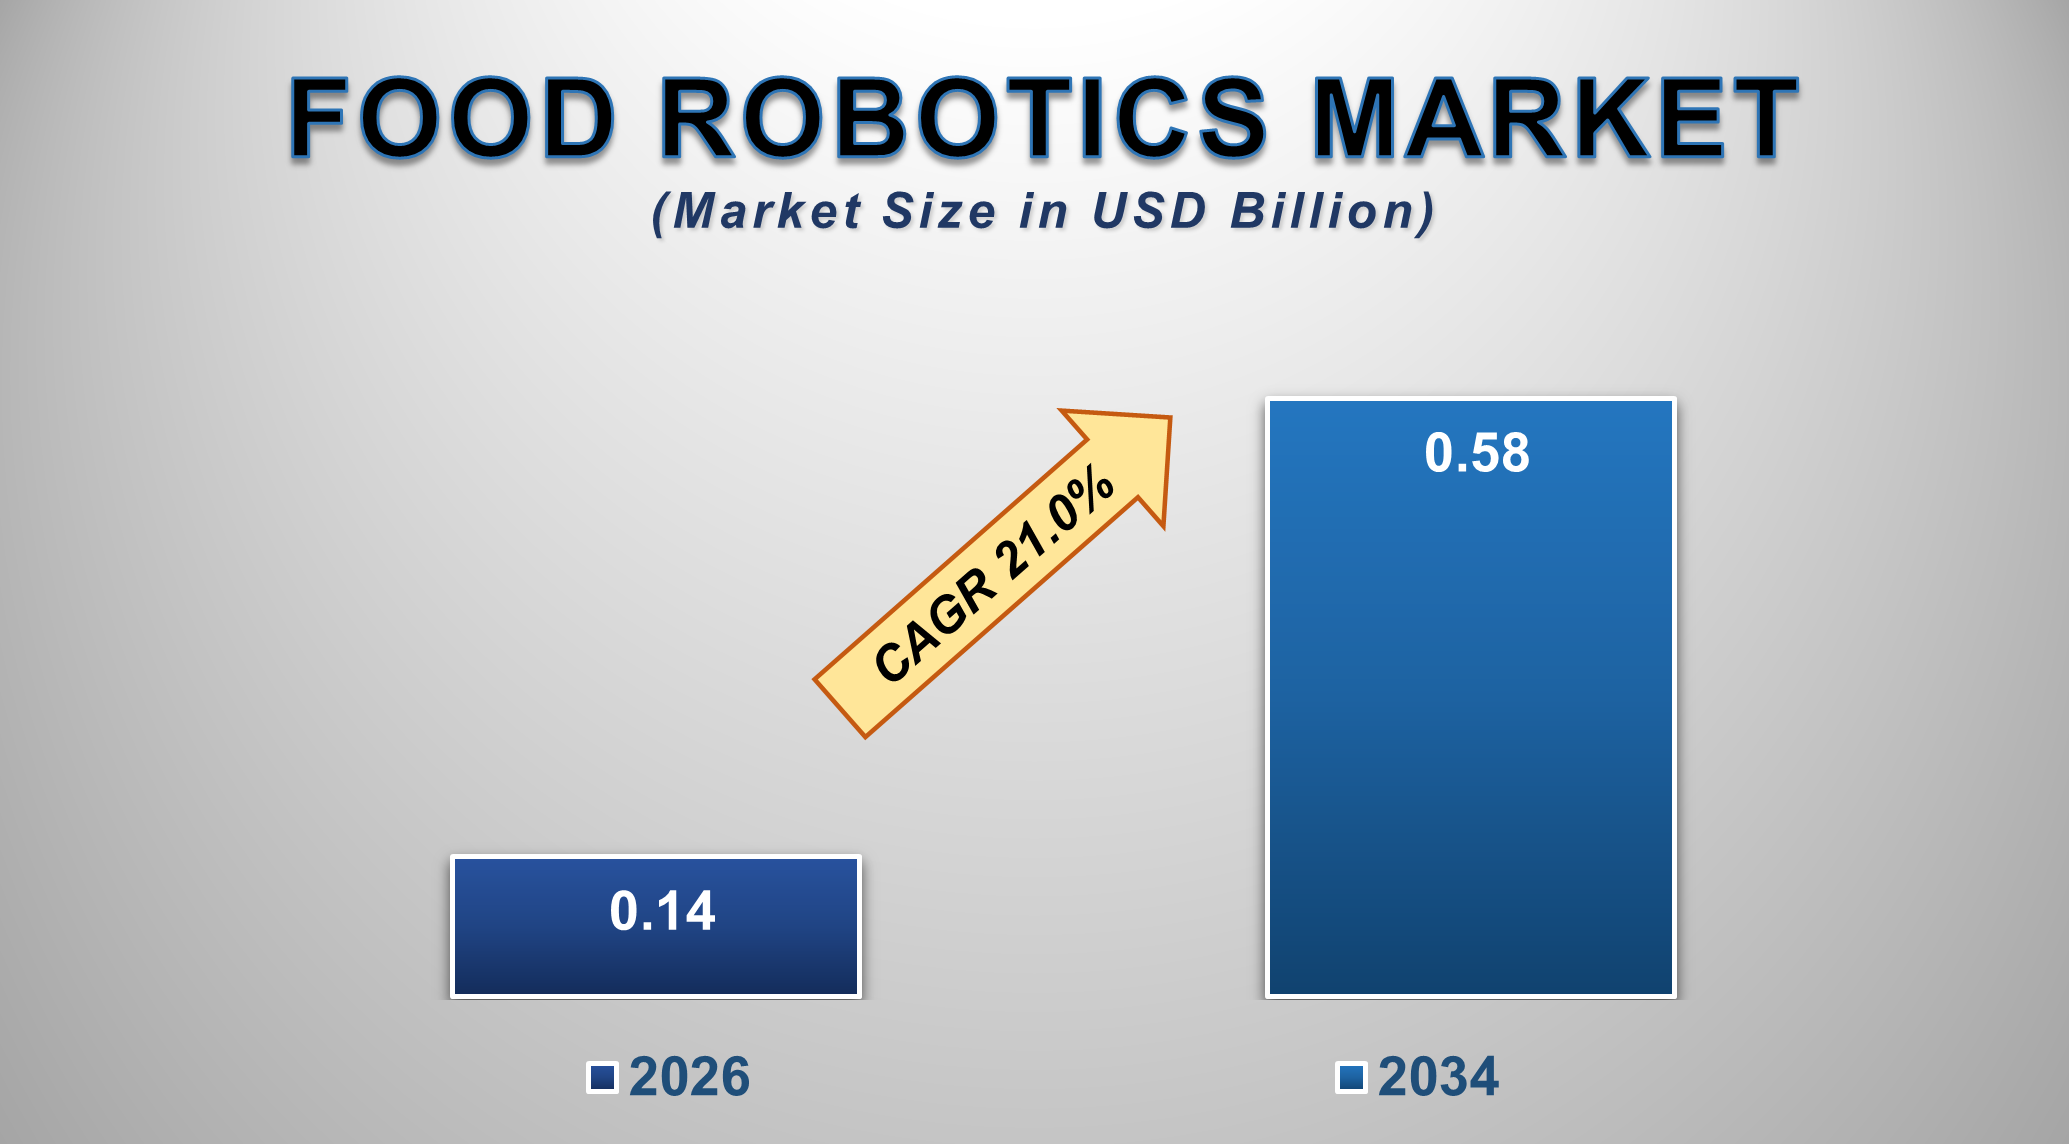
The France food robotics market is projected to expand from USD
0.14 billion in 2026 to USD 0.58 billion by 2034, registering a CAGR of 21.0%
during 2026–2034. The French food robotics market is developing due to the
increase in automation in food processing, packaging, picking, sorting,
inspection, and palletizing as food manufacturers strive to boost productivity,
improve product consistency, and ensure food safety amid labor shortages. The
presence of a strong food-processing foundation in France creates a wide range
of applications for articulated, delta, SCARA, and collaborative robots,
whereby their use will continue expanding from repetitive packaging processes
to more versatile food processing and handling activities. Moreover, the demand
will shift towards vision-guided, artificial intelligence, and modular robotics
solutions that can handle product variations, frequent changeovers, and limited
space. The market is also driven by the focus on modernization, digitalization,
and flexible automation, which offers significant opportunities for global
robot original equipment manufacturers (OEMs) and food automation
manufacturers.
France Food Robotics Market Growth Drivers
Severe Labor Shortages & Rising
Wage Costs
Labor shortages and rising wages are leading French food
manufacturers to become more mechanized for tasks that are repetitive and
involve large amounts of manual labor, such as processing, handling, packaging,
and palletizing. Hiring and retaining workers becomes a costly venture and also
poses production risk. This makes robotics more appealing for manufacturers to
continue production without relying on manual labor. According to France
Travail, as per the In the September 2026 report, the food industry in France
is facing a labor shortage, especially among production laborers, while at the
same time automation is leading to the creation of related jobs such as
technical, maintenance, and quality assurance jobs. In addition, according to
INSEE, in the July 2026 report, 37% of industries are facing hiring challenges,
whereas wage expectations in the manufacturing sector have hit the highest mark
since April 2024.
Stringent Food Safety and Hygiene
Regulations
Strict food safety and hygiene guidelines are driving French food
producers to invest in robotics in processes where minimizing human
interaction, contamination risks, and process variability is essential. The
robots can deliver controlled and repeatable handling during the processing,
sorting, packing, and palletizing of products in a hygienic process
environment. According to the January 16, 2026, report from the European Union
Reference Laboratory for Listeria monocytogenes from ANSES, new EU guidelines have
been established to assist food enterprises in complying with stricter criteria
for testing and monitoring of Listeria monocytogenes, as well as shelf-life
studies of ready-to-eat foods, with regulatory changes coming into effect in
July 2026.
France
Food Robotics Market Restraint
High Initial Capital Investment and
Integration Complexity
High costs of initial capital investment and integration can
hinder the application of robotics in the food processing industry in France,
especially for small and medium enterprises that have low budgets for
automation. Robotics entails a huge capital outlay not just for the purchase of
the robot itself but for the acquisition of other components such as hygienic
end effectors, machine vision, safety equipment, software, and system
integration. The integration process becomes even more complicated if robots
are to be used in existing production lines that have to cope with several
types of products or stringent hygiene standards. The technological complexity
of food production is also evident from the comments made by ANSES, which
asserts that food production consists of many processing operations that are
inter-related and use biologically highly varied raw materials, thus
complicating automation of the production process.
France
Food Robotics Market Opportunities
Expansion of Autonomous Fast-Food
& Commercial Catering Systems
The growth in the market for autonomous fast food and catering
services provides an emerging business opportunity for manufacturers of food
robots in France because restaurants and catering companies want to maintain
their operational capacity while balancing manpower issues and costs and, at
the same time, speeding up services. Robots can be used throughout the
processes of food processing, cooking, dispensing, assembling orders, and
material handling, thereby making these activities standardized and repeatable
during peak hours while minimizing human involvement. As stated by France
Travail on April 21, 2026, the planned recruitment projects for 2026 in the
hospitality and restaurant sector in France were 319,000, of which 44% were
difficult to recruit. This is an indication of a continuing problem that food
service establishments will face as far as manpower recruitment is concerned.
AI-Driven Soft Gripping & 3D
Vision Systems
Soft grippers and 3D vision technology powered by artificial
intelligence are among the most prominent emerging technology trends in the
French food robotics market, allowing robots to grip products with varied
shapes, sizes, textures, and orientations. While standard grippers and vision
systems may find it hard to work with delicate or non-standardized food
products, 3D vision technology equipped with AI and adaptive soft grippers can
accurately detect product location and orientation, applying appropriate
contact forces to minimize product damage. In June 2026, the research paper
entitled 'Soft Robotics' in the journal Robotics in Engineering demonstrated
that optimized soft robotic grippers were able to achieve more than 97%
trajectory-matching precision when working with different types of food items.
The technology is especially relevant in the French market due to the already
existing applications of food robotics that use soft grippers, 3D vision, and
artificial intelligence for the purpose of sorting and packaging delicate
produce.
France
Food Robotics Market Scope
|
Report
Attributes |
Description |
|
Market
Size in 2026 |
USD
0.14 Billion |
|
Market
Forecast in 2034 |
USD
0.58 Billion |
|
CAGR
% 2026-2034 |
21.0% |
|
Market
Concentration |
Moderate
to High |
|
Base
Year |
2025 |
|
Historic
Data |
2021-2025 |
|
Forecast
Period |
2026-2034 |
|
Report
USP |
Production,
company share, company heatmap, company production capacity, growth factors,
and more |
|
Geography |
France |
|
Segments
Covered |
●
By Type ●
By Application ●
By End User |
|
Key
Demand Side Trends |
●
Shift Towards High-Mix, Low-Volume Production ●
Prioritization of Traceability and Sustainability ●
Surge in Collaborative Robotics (Cobots) |
|
Key
Supply Side Trends |
●
Hygienic Design Innovations (Hygienic Environment /
HE Models) ●
Integration of AI & Predictive Analytics ●
As-a-Service Business Models (RaaS) |
|
Major
Players |
●
KUKA AG ●
ABB Ltd. ●
FANUC Corporation ●
Yaskawa Electric Corporation ●
Stäubli International AG ●
MULTIVAC Group |
France
Food Robotics Market Report Segmentation Analysis
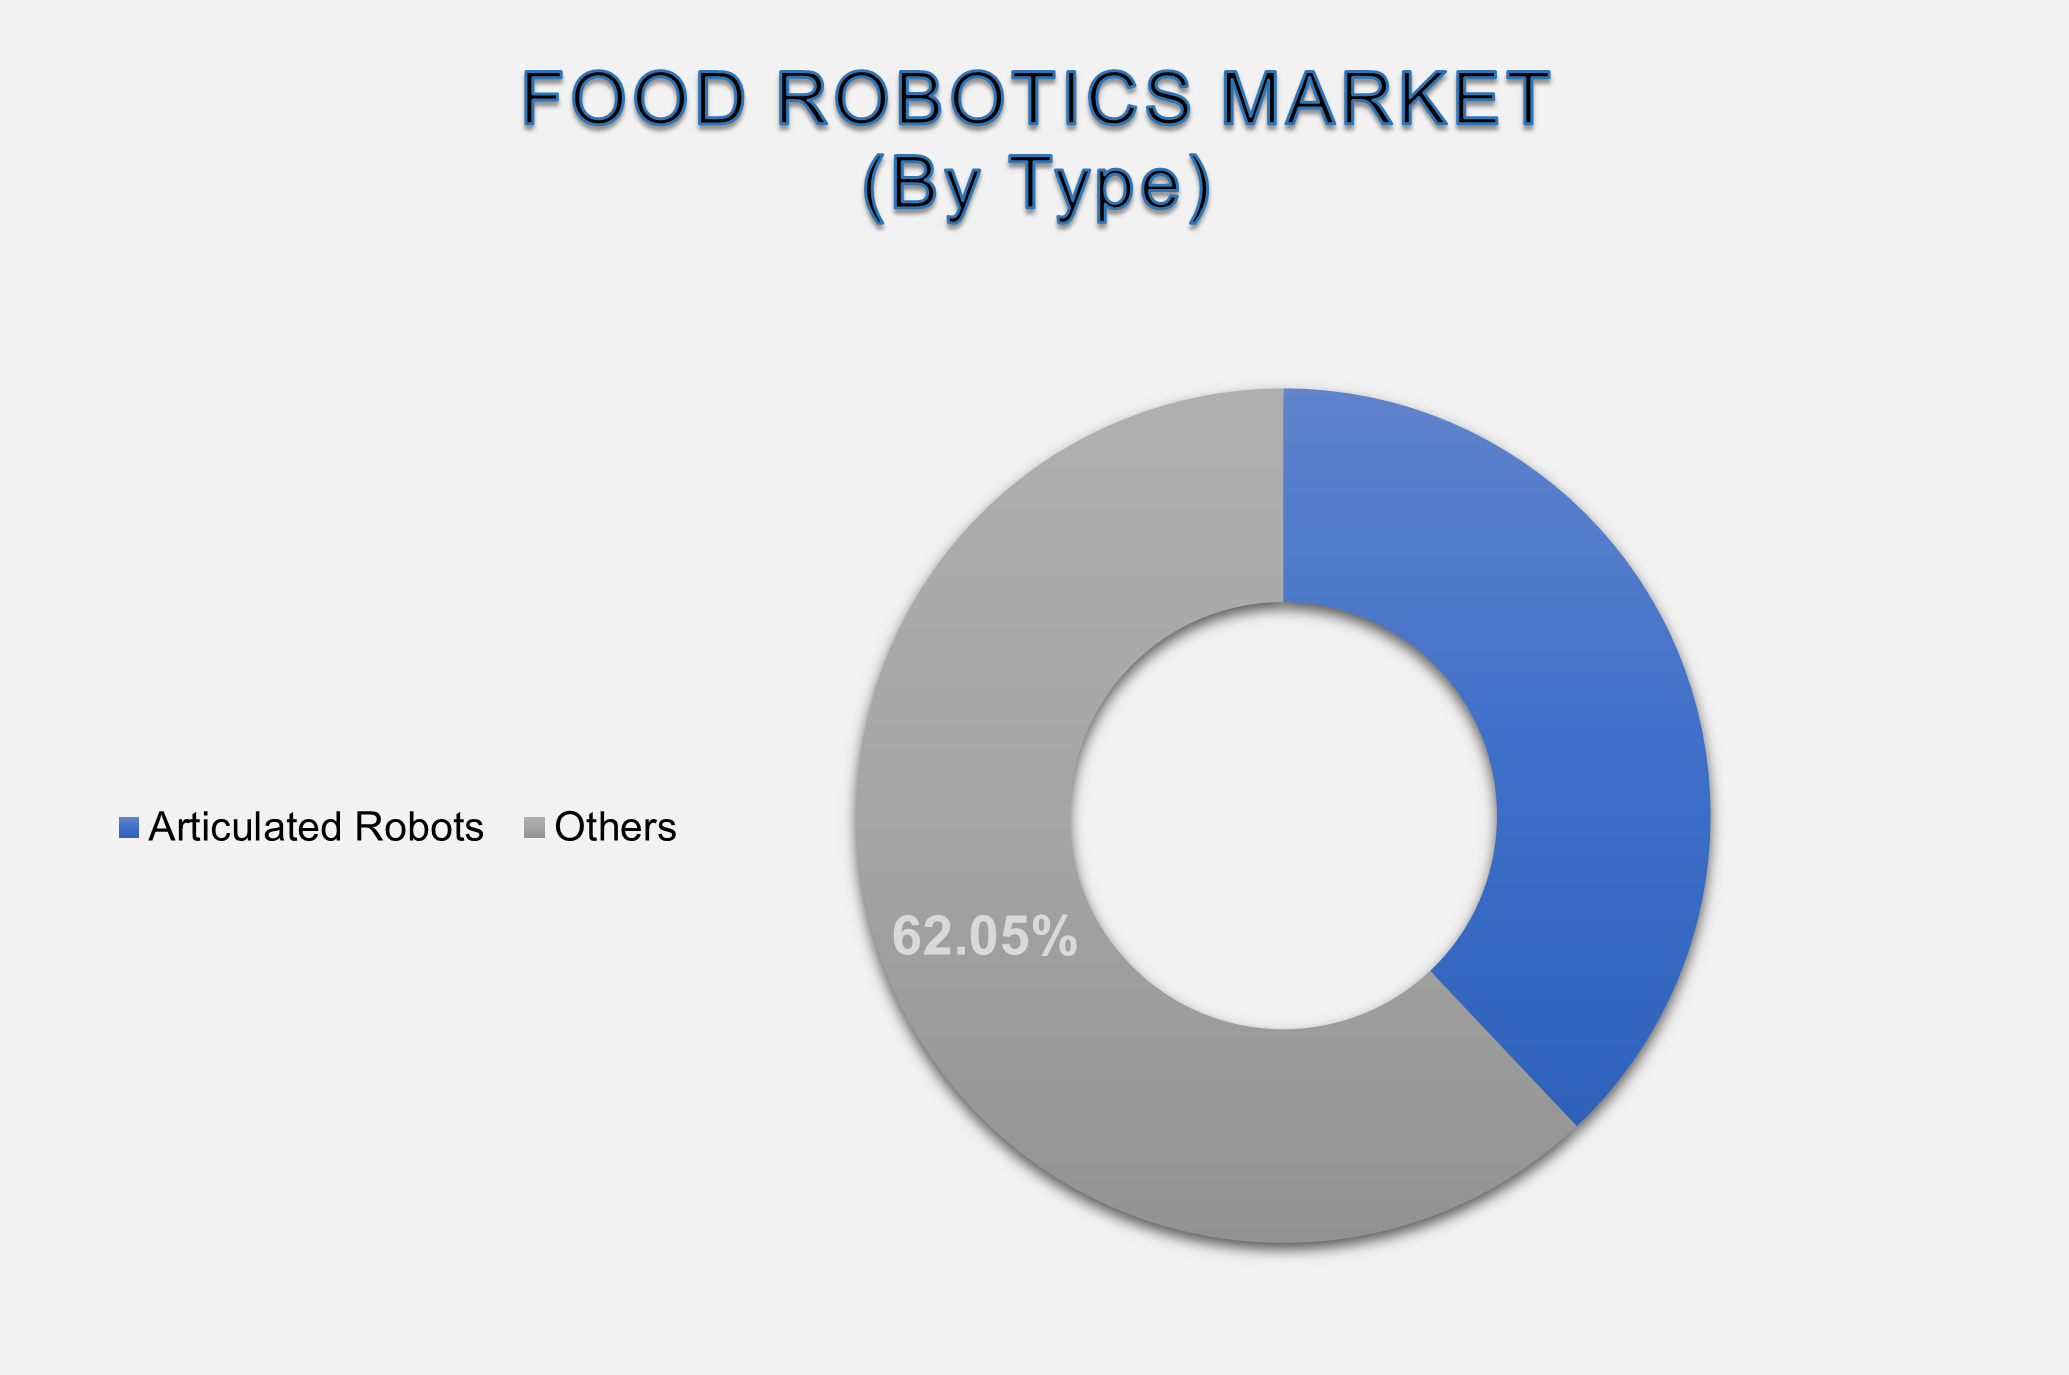
Articulated Robots Segment Is Expected
to Dominate the France Food Robotics Market During the Forecast Period
Segmentation by Robot Type shows that the articulated robots segment is likely to hold the top position in the French food robotics market throughout the forecast period due to their high flexibility, multi-axis operations, and capability to undertake various tasks involved in food processing, handling, packaging, and palletizing. While application-specific robotic systems are limited to certain applications only, articulated robots have the advantage of being customized using end effectors, vision systems, and hygienic designs to suit various types of food products and applications. The DLG Trend Monitor on Robots in the Food and Beverage Industry finds that articulated arm robots are still the most common robots used in the food industry, especially in logistics, packaging, and processing applications. This is also reinforced by the presence of the advanced food processing and packaging automation ecosystem in the country, which requires flexible systems capable of performing various applications. Epson France states that robotic systems are employed in various applications, including food handling and high-speed packaging. Thus, the versatility of applications, payload capacity, and integrability are likely to make articulated robots the top robot type in the country.
Packaging Segment Is Expected to
Dominate the France Food Robotics Market During the Forecast Period
Packaging is projected to lead the French food robotics market,
given the high volume of laborious, repetitive, and standardized activities
associated with primary, secondary, and end-of-line packaging operations.
Packaging robots will be able to perform pick-and-place, filling, wrapping,
sealing, case packing, and palletizing at constant cycle times and handling
precision. The report "Robotics in the Food Industry: DLG Expert
Report" lists packaging among the key application areas of food robots and
states that repackaging is one of the most common robot applications in
packaging, and robots are being used more often for packaging and
palletization, since these operations have a lot of laborious and repetitive
aspects. The relevance of automation in packaging in France is also confirmed
by Epson France, as it refers to robotics applications for food packaging and
palletizing in fresh food, bakery, ready-to-eat food, and dairy applications,
which require speed and flexibility. Thus, the combination of high throughput
needs, labor savings, and structured packaging processes is expected to drive
packaging as the leading application segment in France.
The Food Manufacturers Segment Is
Expected to Dominate the France Food Robotics Market During the Forecast Period
The food manufacturer segment is anticipated to occupy a dominant
share in the French food robotics market in the forecast period, owing to the
extensive requirement for automation in all activities related to food
processing, handling, sorting, inspection, packaging, and palletizing. Food
manufacturers function in large-scale production settings that involve
repetitive operations, strict hygiene, product quality consistency, and
efficiency of the production process. The use of robotics in various stages of
the production process increases the utilization rate of the equipment. Besides
this, the rising variation in products and decreasing production cycles are
motivating food manufacturers to incorporate flexible robots for varied
products and production process formats. The automation potential of
manufacturing settings is expected to make this segment dominate the French
food robotics market in the forecast period.
The following segments are part of an
in-depth analysis of the France Food Robotics Market:
|
Market Segments |
|
|
By Type |
●
Articulated Robots ●
SCARA Robots ●
Delta Robots ●
Collaborative Robots |
|
By Application |
●
Food Processing ●
Packaging ●
Palletizing ●
Sorting & Grading ●
Others |
|
By End User |
●
Food Manufacturers ●
Food Service Providers ●
Beverage Industry ●
Others |
France
Food Robotics Market Competition Landscape Analysis
The competitive environment in the French food robotics market can
be described as moderately concentrated, with leading robotics original
equipment manufacturers maintaining their dominance on the market in the
segment of robotic equipment and with French/European food robotics integration
companies being competitive through specialized application development and
full automation solutions. In terms of competitive differentiation, the leading
companies compete based on the quality of their robots, hygiene features, load
capacities, speed, use of artificial intelligence, vision systems, flexibility
of operations, software platforms, and after-sales services. Competition is
particularly fierce in such applications as packaging, pick-and-place
operations, palletizing, and food handling, where more and more manufacturers
demand integrated robotic cells. The integration market is also competitive
because local companies can offer custom-tailored solutions that integrate
globally available robot platforms into production lines.
France
Food Robotics Market Recent Developments News:
●
In August 2026, Serve Robotics announced a partnership with
Grubhub to expand autonomous food delivery across Chicago, Los Angeles, and
Alexandria, initially covering more than 100 participating merchants in Chicago
and nearly 200 in Los Angeles. The company also announced expansion into San
Jose and Washington, D.C., highlighting the growing deployment of robotics in
restaurant delivery and foodservice.
●
In October 2021, French food robotics start-up Cala announced a
€5.5 million seed investment to expand its autonomous pasta-making robot
operations across France and explore additional European locations. The company
had developed a fully robotic pasta restaurant in Paris, with its system
capable of preparing up to 400 orders per hour within a 4 m² kitchen,
highlighting the potential for compact autonomous food preparation systems to
improve throughput and operating economics in the foodservice sector.
The France Food Robotics Market is
dominated by a few large companies, such as
●
FANUC Corporation
●
KUKA AG
●
ABB Ltd.
●
Yaskawa Electric Corporation
●
Stäubli International AG
●
Kawasaki Heavy Industries Ltd.
●
Mitsubishi Electric Corporation
●
OMRON Corporation
●
DENSO Corporation
●
Seiko Epson Corporation
●
Universal Robots A/S
●
GEA Group AG
●
Syntegon Technology GmbH
●
Gerhard Schubert GmbH
●
MULTIVAC Group
●
Krones AG
●
JBT Marel
●
Ishida Co., Ltd.
●
MG Tech Group
●
Sepro Group
● Other Prominent Players
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
1.
France
Food Robotics Market Introduction and Market Overview
1.1. Objectives of the Study
1.2. Market Segmentation
1.2.1.Type of the France Food Robotics
Market
1.2.2.Application of the France Food
Robotics Market
1.2.3.End Users of the France Food
Robotics Market
1.3. Competition Coverage List of
Market Participants
1.4. Market Definition: Food Robotics
Market
2.
Executive Summary
2.1. France Food Robotics Market
Estimation & Forecast
2.1.1.France Food Robotics Market Size
(US$ Million) Estimates & Historical Trend Analysis (2021 - 2025)
2.1.2.France Food Robotics Overall
Market Size (US$ Million), Growth Rate (Y-o-Y), Market CAGR (%), Market
forecast (2026 - 2034)
2.2. Snapshot of France Food Robotics
Market
2.3. France Food Robotics Market
Revenue Share (%) 2025
2.4. Key Competitors & Key
Insights
3.
Market Overview (Qualitative
Analysis)
3.1. Demand Side Trends
3.2. Supply Side Trends /
Manufacturing Trends
3.3. Demand and Opportunity
Assessment, 2026 - 2034
3.4. Market Dynamics
3.4.1.Drivers
3.4.2.Limitations
3.4.3.Opportunities
3.4.4.Impact Analysis of Drivers and Restraints
3.5. Key Developments
3.6. Regulatory Landscape
3.7. Pricing Analysis
3.8. Supply Chain Analysis
3.9. Porter’s Five Forces Analysis
3.9.1.Bargaining Power of Suppliers
3.9.2.Bargaining Power of Buyers
3.9.3.Threat of Substitutes
3.9.4.Threat of New Entrants
3.9.5.Competitive Rivalry
3.10. PEST Analysis
3.10.1. Political Factors
3.10.2. Economic Factors
3.10.3. Social Factors
3.10.4. Technology Factors
4.
France Food Robotics Market
Estimates & Forecast Trend Analysis, by Type
4.1. France Food Robotics Market
Assessments & Key Findings, by Type
4.2. France Food Robotics Market
Revenue (US$ Million) Estimates and Forecasts, by Type, 2021 - 2034
4.2.1. Articulated Robots
4.2.2.SCARA Robots
4.2.3.Delta Robots
4.2.4.Collaborative Robots
5.
France Food Robotics Market
Estimates & Forecast Trend Analysis, by Application
5.1. France Food Robotics Market
Assessments & Key Findings, by Application
5.2. France Food Robotics Market
Revenue (US$ Million) Estimates and Forecasts, by Application, 2021 - 2034
5.2.1.Food Processing
5.2.2.Packaging
5.2.3.Palletizing
5.2.4.Sorting & Grading
5.2.5.Others
6.
France Food Robotics Market
Estimates & Forecast Trend Analysis, by End User
6.1. France Food Robotics Market
Assessments & Key Findings, by End User
6.2. France Food Robotics Market
Revenue (US$ Million) Estimates and Forecasts, by End User, 2021 - 2034
6.2.1.Food Manufacturers
6.2.2.Food Service Providers
6.2.3.Beverage Industry
6.2.4.Others
7. Competition Landscape
7.1. France Food Robotics Market Product
Mapping
7.2. France Food Robotics Market
Concentration Analysis, by Leading Players / Innovators / Emerging Players /
New Entrants
7.3. France Food Robotics Market Tier
Structure Analysis
7.4. France Food Robotics Market
Concentration & Company Market Shares (%) Analysis, 2025
8. Company Profiles
8.1. FANUC Corporation
8.1.1.Company Overview & Key Stats
8.1.2.Financial Performance & KPIs
8.1.3.Product Portfolio
8.1.4.SWOT Analysis
8.1.5.Business Strategy & Recent
Developments
* Similar details would be provided
for all the players mentioned below
8.2.
KUKA AG
8.3.
ABB Ltd.
8.4.
Yaskawa Electric Corporation
8.5.
Stäubli International AG
8.6.
Kawasaki Heavy Industries Ltd.
8.7.
Mitsubishi Electric Corporation
8.8.
OMRON Corporation
8.9.
DENSO Corporation
8.10.
Seiko Epson Corporation
8.11.
Universal Robots A/S
8.12.
GEA Group AG
8.13.
Syntegon Technology GmbH
8.14.
Gerhard Schubert GmbH
8.15.
MULTIVAC Group
8.16.
Krones AG
8.17.
JBT Marel
8.18.
Ishida Co., Ltd.
8.19.
MG Tech Group
8.20.
Sepro Group
8.21. Other Prominent Players
9.
Research Findings &
Conclusion
10. Assumptions & Acronyms Used
11. Research
Methodology
11.1. External Transportation /
Databases
11.2. Internal Proprietary Database
11.3. Primary Research
11.4. Secondary Research
11.5. Assumptions
11.6. Limitations
11.7. Report FAQs
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
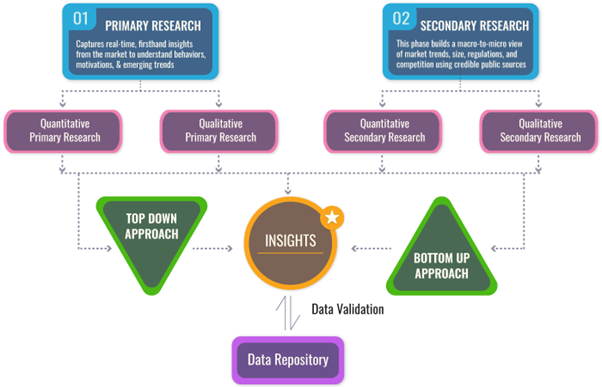
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables