Inverted Pouches Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By Type (Inverted Spouted Pouches, Inverted Stand-Up Pouches, Inverted Squeeze Pouches, Inverted Refill Pouches, Others); By Material (Polyethylene, Polypropylene, Multi-Layer Films, Others); By Application (Food & Beverages, Personal Care, Household Products, Pet Care, Healthcare, Industrial, Others); and Geography
2026-10-09
Packaging Industry
Aishwarya Panbude (Research Analyst)
Description
Inverted Pouches Market Overview
The global Inverted
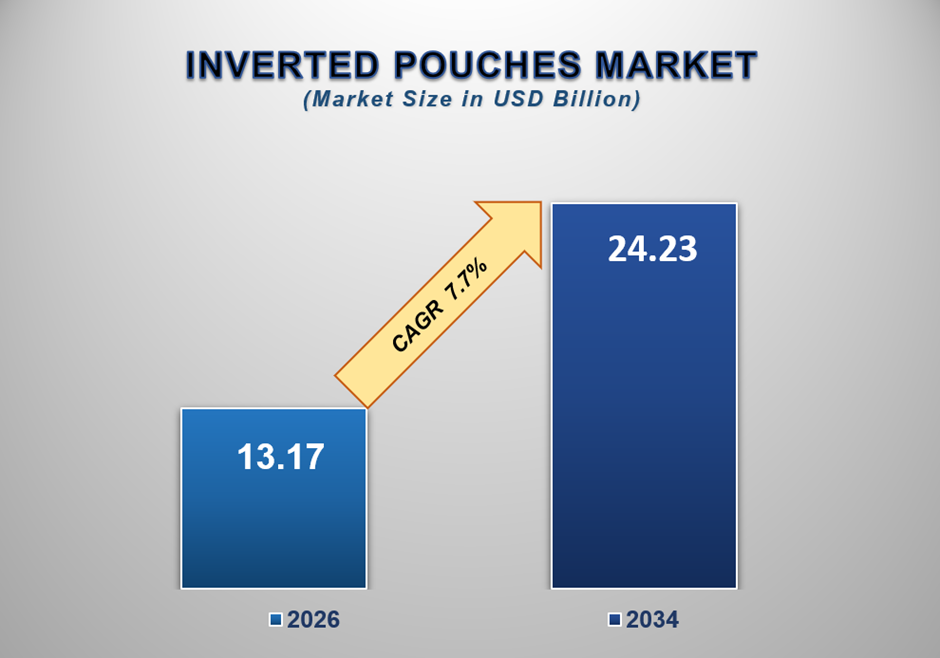
Pouches Market was valued at USD 13.17 billion in 2026 and is
projected to reach USD 24.23 billion by 2034, expanding at a CAGR of
7.7% during the forecast period. The market is witnessing sustained
expansion as manufacturers and brand owners increasingly shift toward
lightweight, convenient, space-efficient, and functional packaging formats.
Growing consumer preference for easy dispensing, rising adoption of flexible
packaging, increasing demand for portion-controlled products, and the need to
reduce packaging material and transportation requirements are supporting market
development.
Inverted pouches
are flexible packaging formats designed to remain positioned with the
dispensing opening facing downward or in an orientation that allows the
packaged product to move toward the closure. This configuration can improve
product evacuation and simplify dispensing, particularly for viscous and
semi-viscous products such as sauces, condiments, spreads, syrups, honey,
personal care formulations, and household liquids.
The increasing
movement away from conventional rigid containers is one of the important
factors supporting demand for inverted pouch solutions. Compared with many
rigid packaging formats, flexible pouches can provide lower package weight,
efficient storage, reduced transportation requirements, and greater design
flexibility. These characteristics are particularly valuable for manufacturers
seeking to optimize logistics while delivering convenient packaging to
consumers.
The food and
beverage industry represents a major area of opportunity for inverted pouches.
Products such as ketchup, mayonnaise, mustard, chocolate syrup, honey, sauces,
dressings, purees, and other semi-liquid foods can benefit from the upside-down
configuration because the product naturally moves toward the dispensing area.
This can make the package easier to squeeze and may reduce residual product
left inside the container.
Consumer
convenience is also encouraging adoption across personal care and household
applications. Shampoos, conditioners, lotions, creams, gels, liquid soaps,
cleaning products, and other formulations can be packaged in inverted pouch
structures with suitable spouts, caps, and barrier films.
The expansion of
e-commerce is creating another favorable environment for inverted pouches.
Lightweight flexible packaging can help reduce package weight and storage
volume compared with certain rigid alternatives, while custom pouch structures
can be designed to improve leak resistance and product protection during
transportation. Cheer Pack, for example, markets inverted spouted pouches that
emphasize lightweight construction, portability, and high product evacuation.
Advancements in
pouch materials, closures, barrier films, printing technologies, and filling
processes are further broadening application possibilities. Manufacturers are
developing recyclable, PCR-containing, and other lower-impact pouch structures
while maintaining the barrier, sealing, and mechanical performance required by
packaged products. ProAmpac currently offers pouch structures incorporating
recyclable, recycle-ready, post-consumer recycled, and compostable options
across selected applications.
Sustainability
is therefore becoming an increasingly important competitive factor. Brand
owners are evaluating flexible packaging formats not only on appearance and
functionality but also on material efficiency, recyclability, recycled content,
transportation requirements, and end-of-life considerations.
As packaging
manufacturers continue to improve inverted pouch performance and brand owners
seek alternatives to traditional bottles, jars, and other rigid containers, the
global inverted pouches market is expected to register strong growth through
2034.
Inverted Pouches Market Drivers and
Opportunities
Growing
Preference for Lightweight and Convenient Packaging Is Driving Market Growth
The increasing
demand for lightweight and consumer-friendly packaging is a major factor
contributing to the expansion of the inverted pouches market.
Consumers
increasingly prefer packaging that is easy to hold, open, squeeze, store, and
dispense. Inverted pouches can address these requirements by combining flexible
construction with a dispensing system positioned to facilitate product flow.
The
configuration is particularly useful for viscous products because gravity and
package orientation can help move the contents toward the closure. This can
improve dispensing convenience and reduce the effort required to extract
products from the package.
Packaging
manufacturers are also benefiting from the material-efficiency advantages
associated with flexible formats. Compared with rigid bottles and jars, pouch
structures can require less packaging material by weight for certain
applications and can occupy less space during transportation and storage.
The combination
of portability, functional dispensing, reduced package weight, and consumer
convenience is encouraging brands to evaluate inverted pouches for both new
product launches and packaging conversions.
The development
of specialized inverted pouch formats with improved seals, caps, spouts,
barrier properties, and structural strength is expected to further strengthen
adoption across food, personal care, household, and other consumer
applications.
Increasing
Adoption of Flexible Packaging in Food and Personal Care Is Supporting Market
Growth
The expansion of
flexible packaging across food, beverage, personal care, and household product
categories is creating additional opportunities for inverted pouch
manufacturers.
Food
manufacturers are increasingly using flexible formats for condiments, sauces,
spreads, syrups, purees, and other products where controlled dispensing and
efficient product evacuation are important. Inverted pouches can also provide
greater surface area for graphics and branding compared with some conventional
containers.
In personal
care, flexible pouches can be used for shampoos, conditioners, lotions, creams,
liquid soaps, and other products. The combination of flexible construction and
dispensing functionality can create a convenient package while allowing brands
to differentiate products through shape, graphics, closure design, and material
selection.
Household
products represent another expanding application area. Concentrated cleaners,
detergents, liquid solutions, and refill products can benefit from lightweight
packaging and controlled dispensing.
The broader
transition toward flexible packaging is therefore increasing the addressable
market for inverted pouch technologies. Industry research identifies food,
personal care, home care, and related applications as important areas for
spouted and flexible pouch adoption.
Recyclable
Materials, Refill Formats and Advanced Dispensing Technologies Present
Significant Opportunities
Sustainability-focused
packaging development is creating substantial opportunities for inverted pouch
manufacturers.
Packaging
companies are investing in mono-material and recycle-ready structures,
recycled-content films, improved barrier technologies, and pouch designs that
reduce material consumption while preserving package performance.
Cheer Pack, for
example, offers PCR-content spouted pouch solutions and recyclable-oriented
structures, while its inverted pouch portfolio emphasizes lightweight
construction and product evacuation.
Refill
applications are also emerging as an important opportunity. Brands can use
flexible pouches to supply concentrated or repeat-use products while reducing
the quantity of packaging material required for individual purchases. Household
cleaning products, personal care formulations, and selected food products can
benefit from refill-oriented pouch systems.
Advanced
closures and dispensing technologies are further increasing functionality.
Screw caps, flip-top closures, child-resistant systems, tamper-evident
features, and specialized spouts can be incorporated depending on product
requirements.
The development
of high-barrier films and improved sealing technologies is also allowing
inverted pouches to accommodate a wider range of sensitive products. As brands
seek packaging that combines convenience, product protection, sustainability,
and attractive shelf presentation, investments in advanced inverted pouch
technologies are expected to create new market opportunities through 2034.
Inverted Pouches Market Scope
|
Report Attributes |
Description |
|
Market Size in 2026 |
USD 13.17 Billion |
|
Market Forecast in 2034 |
USD 24.23 Billion |
|
CAGR % 2026-2034 |
7.7% |
|
Base Year |
2025 |
|
Historic Data |
2021-2025 |
|
Forecast Period |
2026-2034 |
|
Report USP |
Production, Consumption,
Company Share, Company Heatmap, Company Production, Service Type, Growth
Factors and more |
|
Segments Covered |
• By Type • By Material • By Application |
|
Regional Scope |
● North America |
|
Country Scope |
U.S. |
Inverted Pouches Market Report
Segmentation Analysis
The global
inverted pouches market industry analysis is segmented by type, by material, by
application, and by region.
The Inverted
Spouted Pouches Segment Is Expected to Dominate the Market During the Forecast
Period
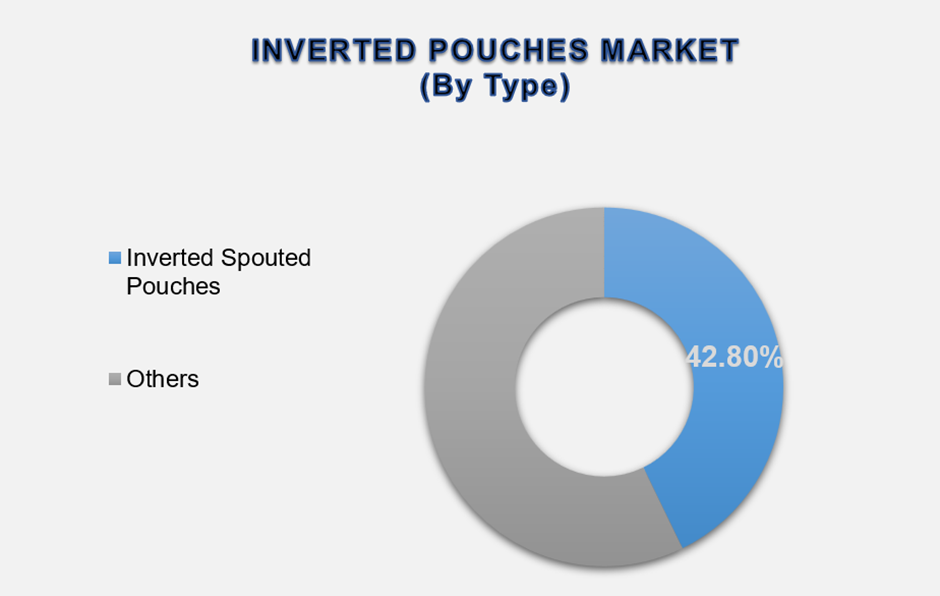
The Inverted
Spouted Pouches segment accounted for approximately 42.8% of the
global market, representing the leading product category.
Inverted spouted
pouches maintain a strong position because they combine flexible packaging with
controlled product dispensing. The integrated spout and closure system allows
manufacturers to package liquid and semi-liquid products while providing consumers
with greater control over the quantity dispensed.
The format is
particularly suitable for sauces, condiments, syrups, honey, spreads, personal
care products, and household liquids. The inverted orientation helps keep the
product near the dispensing opening, which can make the package easier to use
and improve product evacuation.
Spouted inverted
pouches can also be customized according to product viscosity, fill volume,
barrier requirements, closure specifications, and branding needs. Cheer Pack's
MultiFlex inverted spouted pouch, for instance, is designed to stand on its cap
or gusset and is positioned for applications requiring portability and high
product evacuation.
Continued
innovation in spouts, caps, barrier films, and recyclable structures is
expected to support the segment's expansion during the forecast period.
The
Polyethylene Segment Is Expected to Lead the Market by Material
The Polyethylene
segment is expected to represent a leading share of the inverted pouches market
due to the material's flexibility, sealing characteristics, chemical
resistance, lightweight nature, and suitability for flexible packaging
structures.
Polyethylene
films can be engineered for different thicknesses and performance requirements
and are widely used as part of pouch structures requiring reliable heat sealing
and mechanical flexibility.
The development
of PE-based recycle-ready structures is also creating additional opportunities.
Packaging manufacturers are increasingly working on structures that simplify
material composition and improve compatibility with recycling systems.
Polyethylene is
particularly relevant for applications involving food products, household
liquids, personal care formulations, and other products where flexible
packaging and reliable seals are required.
The Food
& Beverages Segment Is Expected to Dominate the Market by Application
The Food
& Beverages segment represents a major application area for inverted
pouches due to the extensive use of convenient flexible packaging for sauces,
condiments, spreads, syrups, purees, honey, dressings, and other products.
The inverted
format provides an advantage for products that are difficult to remove from
conventional containers. By keeping the dispensing point toward the bottom, the
package can facilitate product movement and minimize the need for repeated
shaking or scraping.
Food
manufacturers are also seeking packaging formats that provide strong shelf
visibility, easy handling, controlled dispensing, and efficient transportation.
Flexible pouches can address several of these requirements while allowing
brands to use distinctive shapes, high-quality graphics, and specialized
closure systems.
The growing
popularity of convenient food products, ready-to-use sauces, packaged spreads,
and portion-controlled formats is expected to continue supporting demand for
inverted pouches in the food sector.
The following segments are part of an in-depth analysis of the global Inverted Pouches Market:
|
Market Segments |
|
|
By Material |
●
Polyethylene ●
Polypropylene ●
Multi-Layer Films ●
Others |
|
By
Type |
●
Inverted Spouted Pouches ●
Inverted Stand-Up Pouches ●
Inverted Squeeze Pouches ●
Inverted Refill Pouches ●
Others |
|
By Application |
●
Food & Beverages ●
Personal Care ●
Household Products ●
Pet Care ●
Healthcare ●
Industrial ●
Others |
Inverted Pouches Market Share
Analysis By Region
Europe is expected to maintain a significant share of the global inverted
pouches market over the forecast period, supported by established flexible
packaging manufacturing capabilities, strong consumer demand for convenient
packaging, and increasing attention toward recyclable and resource-efficient
packaging solutions. Existing industry analysis identifies Europe as a leading
regional market for inverted pouches.
North America represents an important market due to strong demand for convenient
food packaging, personal care products, household products, and flexible
packaging alternatives. The United States accounts for a major portion
of regional demand, supported by established packaging converters, strong
brand-owner activity, and continuing development of spouted and inverted pouch
technologies.
The region is
also witnessing increased attention toward recycled-content and recycle-ready
pouch structures. Cheer Pack North America markets PCR-content and
recycle-ready spouted pouch solutions and serves food and non-food applications
including personal care and home and garden products.
Asia Pacific is expected to register significant growth during the forecast
period. Expanding food processing industries, rising consumer spending,
increasing urbanization, growing packaged-food consumption, and development of
personal care and household product industries are supporting flexible
packaging demand.
China, India,
Japan, and South Korea are major contributors to
regional growth. The expansion of modern retail, e-commerce, packaged foods,
personal care products, and household consumables is creating an expanding
customer base for convenient pouch formats.
Increasing
manufacturing capacity and technological development in flexible packaging are
also strengthening the regional supply ecosystem. Asia Pacific's expanding
industrial and consumer markets are expected to make the region an important
growth center for inverted pouch manufacturers.
Latin America is expected to experience steady expansion as packaged food
consumption, modern retail, personal care products, and flexible packaging
adoption continue to develop. Brazil and Mexico represent important
markets because of their large consumer bases and established food and
consumer-goods manufacturing sectors.
Inverted pouches
can provide manufacturers in the region with opportunities to combine
convenient dispensing, lightweight construction, attractive graphics, and
efficient transportation characteristics.
Middle East
& Africa represents an emerging opportunity for
inverted pouch packaging. Increasing retail development, expanding food and
beverage processing, rising personal care consumption, and growing interest in
modern packaging formats are contributing to regional demand.
Countries such
as Saudi Arabia, the UAE, and South Africa are expected to remain
important markets as manufacturers and retailers increasingly adopt flexible
packaging solutions for food, household, personal care, and other consumer
products.
Inverted
Pouches Market Competition Landscape Analysis
The inverted
pouches market is competitive, with established flexible packaging
manufacturers, pouch converters, closure suppliers, and specialized packaging
companies competing through product innovation, material development,
customized pouch structures, and dispensing technologies.
Companies are
increasingly focusing on packaging solutions that combine lightweight
construction with reliable sealing, strong barrier performance, convenient
dispensing, and attractive shelf presentation. The competitive environment is
also being influenced by growing demand for recyclable and recycled-content
packaging.
Product
development is an important strategy across the industry. Manufacturers are
introducing inverted pouch formats with different spouts, caps, gussets, film
structures, sizes, and shapes to accommodate products with varying viscosities
and packaging requirements.
Sustainability
has become another major area of competition. Packaging companies are
developing mono-material and recycle-ready structures as well as PCR-content
solutions. ProAmpac offers several premade pouch structures incorporating
recyclable, recycle-ready, PCR, and compostable options across its portfolio.
Glenroy's
STANDCAP pouch is another example of specialized inverted pouch development.
The company describes the format as an alternative to rigid plastic and glass
packaging for applications including food, beverages, and personal care, with
versions incorporating PCR materials.
Strategic
partnerships, technology development, manufacturing expansion, customized
packaging programs, and collaboration with brand owners are expected to remain
important competitive strategies.
As demand
increases for convenient, lightweight, and sustainability-oriented packaging,
manufacturers with capabilities in advanced films, closures, pouch conversion,
filling compatibility, and recyclable structures are expected to compete
actively for new applications.
Global
Inverted Pouches Market Recent Developments News
●
In 2026 – Packaging manufacturers continued expanding recyclable and
PCR-content spouted pouch solutions to address increasing demand for
lower-impact flexible packaging. Cheer Pack has introduced PCR-content spouted
pouch solutions for selected liquid applications.
●
In 2026 – Flexible packaging companies continued developing inverted pouch
formats for food, personal care, household, and e-commerce applications, with
emphasis on lightweight construction, product evacuation, and dispensing
convenience.
●
In 2025 – Manufacturers increasingly focused on mono-material and
recycle-ready pouch structures as packaging sustainability requirements became
more important for brand owners and retailers.
●
In 2025 – Advanced spout, cap, and closure systems continued to gain
attention as manufacturers sought to improve leak resistance, controlled
dispensing, resealability, and consumer convenience.
●
In 2025 – Flexible packaging producers expanded application-specific pouch
portfolios covering food and beverages, personal care, home care, pet products,
and other consumer applications.
The Global
Inverted Pouches Market is Dominated by a Few Large Companies, Such As
●
Amcor plc
●
AptarGroup, Inc.
●
Cheer Pack North America
●
Constantia Flexibles Group GmbH
●
Coveris Management GmbH
●
Glenroy, Inc.
●
Goglio S.p.A.
●
Mattpack, Inc.
●
Mondi plc
●
Polymer Packaging, Inc.
●
Pouches, Inc.
●
ProAmpac Holdings Inc.
●
Sealed Air Corporation
●
Semco S.A.M.
●
Universal Plastics Bag Co.
●
Viking Masek
●
Volpak Industries
● Others
Frequently Asked Questions
Aishwarya Panbude (Research Analyst)
Aishwarya Panbude is a skilled Research Analyst with 4+ years of experience in market intelligence, consumer insights, competitive analysis, and industry forecasting across the consumer goods, agriculture, and food & beverage sectors. She specializes in market sizing, trend analysis, growth opportunity mapping, and strategic secondary research for global and regional markets.
Her expertise lies in transforming complex industry data into actionable business strategies that help organizations identify emerging trends, understand customer behavior, and gain a competitive edge. With a strong focus on data-driven insights, business intelligence, and future market trends, Jaya delivers high-quality research solutions aligned with evolving industry demands and market dynamics.
1.
Global Inverted Pouches
Market Introduction and Market Overview
1.1. Objectives of the Study
1.2. Global Inverted Pouches Market Scope and Market Estimation
1.2.1.
Global Inverted Pouches Market
Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
1.2.2.
Global Inverted Pouches Market
Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
1.3. Market Segmentation
1.3.1.
By Type of Global Inverted
Pouches Market
1.3.2.
By Material of Global Inverted
Pouches Market
1.3.3.
By Application of Global
Inverted Pouches Market
1.3.4.
Region of Global Inverted
Pouches Market
1.4. Competition Coverage List of Market Participants
1.5. Market Definition: Inverted Pouches Market
2.
Executive Summary
2.1. Demand Side Trends
2.2. Key Market Trends
2.3. Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026
– 2034
2.4. Demand and Opportunity Assessment
2.5. Key Developments
2.6. Overview of Regulatory Landscape, Compliance Framework, and Industry
Standards
2.7. Market Entry Strategies
2.8. Market Dynamics
2.8.1.
Drivers
2.8.2.
Limitations
2.8.3.
Opportunities
2.8.4.
Impact Analysis of Drivers and
Restraints
2.9. Porter's Five Forces Analysis
2.10.
PEST Analysis
3.
Global Inverted Pouches
Market Estimates & Historical Trend Analysis (2021 – 2025)
4.
Global Inverted Pouches
Market Estimates & Forecast Trend Analysis, by Type
4.1. Global Inverted Pouches Market Revenue (US$ Million) Estimates and
Forecasts, by Type, 2021 - 2034
4.1.1.
Inverted Spouted Pouches
4.1.2.
Inverted Stand-Up Pouches
4.1.3.
Inverted Squeeze Pouches
4.1.4.
Inverted Refill Pouches
4.1.5.
Others
5.
Global Inverted Pouches
Market Estimates & Forecast Trend Analysis, by Material
5.1. Global Inverted Pouches Market Revenue (US$ Million) Estimates and
Forecasts, by Material, 2021 - 2034
5.1.1.
Polyethylene
5.1.2.
Polypropylene
5.1.3.
Multi-Layer Films
5.1.4.
Others
6.
Global Inverted Pouches
Market Estimates & Forecast Trend Analysis, by Application
6.1. Global Inverted Pouches Market Revenue (US$ Million) Estimates and
Forecasts, by Application, 2021 - 2034
6.1.1.
Food & Beverages
6.1.2.
Personal Care
6.1.3.
Household Products
6.1.4.
Pet Care
6.1.5.
Healthcare
6.1.6.
Industrial
6.1.7.
Others
7.
Global Inverted Pouches
Market Estimates & Forecast Trend Analysis, by Region
7.1. Global Inverted Pouches Market Revenue (US$ Million) Estimates and
Forecasts, by Region, 2021 - 2034
7.1.1.
North America
7.1.2.
Europe
7.1.3.
Asia Pacific
7.1.4.
Middle East & Africa
7.1.5.
Latin America
8.
North America Inverted
Pouches Market: Estimates & Forecast Trend Analysis
8.1. North America Inverted Pouches Market Assessments & Key Findings
8.1.1.
North America Inverted Pouches
Market Introduction
8.1.2.
North America Inverted Pouches
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
8.1.2.1.
By Type
8.1.2.2.
By Material
8.1.2.3.
By Application
8.1.2.4.
By Country
8.1.2.4.1.
The U.S.
8.1.2.4.2.
Canada
9.
Europe Inverted Pouches
Market: Estimates & Forecast Trend Analysis
9.1. Europe Inverted Pouches Market Assessments & Key Findings
9.1.1.
Europe Inverted Pouches Market
Introduction
9.1.2.
Europe Inverted Pouches Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
9.1.2.1.
By Type
9.1.2.2.
By Material
9.1.2.3.
By Application
9.1.2.4.
By Country
9.1.2.4.1.
Germany
9.1.2.4.2.
Italy
9.1.2.4.3.
The U.K.
9.1.2.4.4.
France
9.1.2.4.5.
Spain
9.1.2.4.6.
Switzerland
9.1.2.4.7.
Rest of Europe
10. Asia Pacific Inverted Pouches Market: Estimates & Forecast Trend
Analysis
10.1.
Asia Pacific Inverted Pouches
Market Assessments & Key Findings
10.1.1.
Asia Pacific Inverted Pouches
Market Introduction
10.1.2.
Asia Pacific Inverted Pouches
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
10.1.2.1.
By Type
10.1.2.2.
By Material
10.1.2.3.
By Application
10.1.2.4.
By Country
10.1.2.4.1.
China
10.1.2.4.2.
Japan
10.1.2.4.3.
India
10.1.2.4.4.
Australia
10.1.2.4.5.
South Korea
10.1.2.4.6.
Rest of Asia Pacific
11. Middle East & Africa Inverted Pouches Market: Estimates &
Forecast Trend Analysis
11.1.
Middle East & Africa
Inverted Pouches Market Assessments & Key Findings
11.1.1.
Middle East & Africa
Inverted Pouches Market Introduction
11.1.2.
Middle East & Africa
Inverted Pouches Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
11.1.2.1.
By Type
11.1.2.2.
By Material
11.1.2.3.
By Application
11.1.2.4.
By Country
11.1.2.4.1.
UAE
11.1.2.4.2.
Saudi Arabia
11.1.2.4.3.
South Africa
11.1.2.4.4.
Rest of Middle East &
Africa
12. Latin America Inverted Pouches Market: Estimates & Forecast
Trend Analysis
12.1.
Latin America Inverted Pouches
Market Assessments & Key Findings
12.1.1.
Latin America Inverted Pouches
Market Introduction
12.1.2.
Latin America Inverted Pouches
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
12.1.2.1.
By Type
12.1.2.2.
By Material
12.1.2.3.
By Application
12.1.2.4.
By Country
12.1.2.4.1.
Brazil
12.1.2.4.2.
Mexico
12.1.2.4.3.
Argentina
12.1.2.4.4.
Rest of Latin America
13. Competition Landscape
13.1.
Global Inverted Pouches Market
Product Mapping
13.2.
Global Inverted Pouches Market
Concentration Analysis, by Leading Players / Innovators / Emerging Players /
New Entrants
13.3.
Global Inverted Pouches Market
Tier Structure Analysis
13.4.
Global Inverted Pouches Market
Concentration & Company Market Shares (%) Analysis, 2026
14. Company Profiles
14.1.
Amcor plc
14.1.1.
Company Overview & Key
Stats
14.1.2.
Financial Performance &
KPIs
14.1.3.
Product Portfolio
14.1.4.
SWOT Analysis
14.1.5.
Business Strategy & Recent
Developments
*Similar details would be provided for all
the players mentioned below
14.2.
AptarGroup, Inc.
14.3.
Cheer Pack North America
14.4.
Constantia Flexibles Group GmbH
14.5.
Coveris Management GmbH
14.6.
Glenroy, Inc.
14.7.
Goglio S.p.A.
14.8.
Mattpack, Inc.
14.9.
Mondi plc
14.10.
Polymer Packaging, Inc.
14.11.
Pouches, Inc.
14.12.
ProAmpac Holdings Inc.
14.13.
Sealed Air Corporation
14.14.
Semco S.A.M.
14.15.
Universal Plastics Bag Co.
14.16.
Viking Masek
14.17.
Volpak Industries
14.18.
Others
15. Research Findings & Conclusion
16. Assumptions & Acronyms Used
17. Research Methodology
17.1.
External Databases
17.2.
Internal Proprietary Database
17.3.
Primary Research
17.4.
Secondary Research
17.5.
Assumptions
17.6.
Limitations
17.7.
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
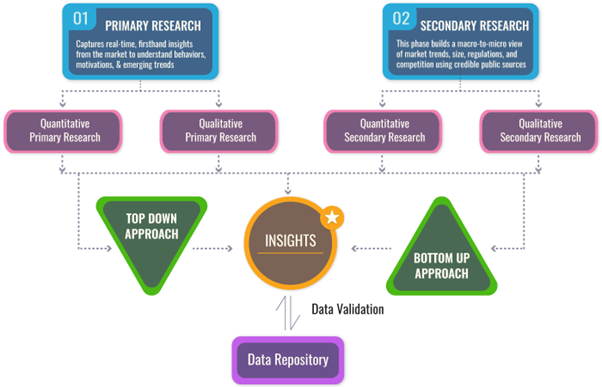
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables