Long Alloy Steel Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By Product Type (Bars, Rods, Wire Rods, Rails, Structural Sections, Others); By Alloy Type (Low Alloy Steel, Medium Alloy Steel, High Alloy Steel); By Application (Construction, Automotive, Mechanical Engineering, Energy & Power, Railways, Oil & Gas, Industrial Equipment, Others); By End User (Infrastructure & Construction, Automotive & Transportation, Industrial Manufacturing, Energy, Others); and Geography
2026-09-28
Real Estate & Infrastructure
Ekta Chaurasia (Team Lead)
Description
Long Alloy Steel Market Overview
The global Long
Alloy Steel Market was valued at USD 751.14 Million in 2026 and is
projected to reach USD 966.45 Million by 2034, expanding at a CAGR of
3.2% during the forecast period. The market is experiencing steady growth
due to continued infrastructure development, demand for high-strength steel
products, expansion of automotive and mechanical manufacturing, railway
modernization, energy infrastructure investment, and increasing requirements
for durable steel products capable of operating under demanding mechanical and
environmental conditions.

Long alloy steel
comprises steel products manufactured with controlled additions of alloying
elements such as chromium, nickel, molybdenum, manganese, silicon, vanadium,
and other elements to improve properties including strength, toughness,
hardness, wear resistance, fatigue performance, corrosion resistance, and
high-temperature performance.
Long alloy steel
products are commonly manufactured in long-form geometries such as bars, rods,
wire rods, rails, structural sections, and specialized profiles. These products
are used extensively in applications where conventional carbon steel may not provide
the required combination of mechanical strength, durability, machinability, or
resistance to demanding operating conditions.
The construction
sector represents an important source of demand. Alloy steel long products are
used in structural components, reinforcement-related applications, heavy
equipment, fasteners, foundations, bridges, industrial buildings, and other
infrastructure projects where higher strength and durability can improve
structural performance.
Infrastructure
modernization is also supporting demand. Governments and private-sector
developers across several regions are investing in transportation
infrastructure, bridges, railways, energy facilities, industrial parks, and
urban development. These projects require steel products capable of meeting
increasingly stringent performance and durability requirements.
The automotive
industry represents another important application area. Alloy steel bars and
rods are used in components such as axles, shafts, gears, crankshafts, steering
components, suspension components, transmission parts, and other high-load
mechanical systems. The use of alloy steel allows manufacturers to achieve the
strength and fatigue resistance required for components subjected to repeated
mechanical stresses.
The increasing
adoption of advanced manufacturing processes is also influencing product
requirements. Automotive and industrial manufacturers are increasingly seeking
steels with predictable metallurgical characteristics, dimensional consistency,
improved machinability, and controlled mechanical properties to support
automated and precision manufacturing.
Mechanical
engineering and industrial equipment manufacturing provide additional demand.
Heavy machinery, agricultural equipment, mining equipment, machine tools,
power-generation equipment, and industrial machinery frequently require
high-strength alloy steel components that can withstand impact, abrasion,
fatigue, and high operating loads.
Railway
development represents another important application. Rails and other railway
components require high wear resistance and fatigue performance because they
are subjected to repeated dynamic loading and contact stresses. Expansion and
modernization of rail networks therefore create opportunities for specialized
alloy steel long products.
Energy
infrastructure is also contributing to market development. Oil and gas
equipment, power-generation systems, renewable-energy infrastructure, and
industrial energy systems require steel components with specific strength,
toughness, heat resistance, or corrosion-performance characteristics.
The market is
also being influenced by developments in steelmaking and processing technology.
Electric arc furnaces, continuous casting, controlled rolling, heat treatment,
precision forging, and advanced metallurgical processes are allowing
manufacturers to produce more consistent alloy steel grades while improving
material utilization and production efficiency.
At the same
time, the industry faces challenges associated with energy costs, raw-material
price volatility, carbon-emission regulations, trade restrictions, and the
capital intensity of steel production. Steel producers are therefore
increasingly investing in energy efficiency, low-carbon production methods,
recycling, process optimization, and higher-value specialty steel products.
The growing
emphasis on infrastructure durability, lightweighting, high-performance
machinery, and resource efficiency is expected to support demand for long alloy
steel products through 2034.
Long Alloy Steel Market Drivers and
Opportunities
Increasing
Infrastructure Development and Demand for High-Strength Steel Is Driving Market
Growth
The continued
expansion and modernization of infrastructure is one of the primary factors
supporting the long alloy steel market.
Large-scale
investments in bridges, highways, railways, industrial facilities, ports,
airports, power infrastructure, and urban development require steel products
capable of supporting high structural loads and long service lives.
Alloying
elements can improve the mechanical characteristics of steel, allowing
manufacturers to develop products with higher strength, toughness, wear
resistance, and fatigue performance than conventional grades.
Long alloy steel
products are particularly important in applications where components experience
repeated mechanical loading or require dimensional and structural reliability
over extended operating periods.
Railway
infrastructure is a notable example. Rail tracks and related components are
subjected to substantial cyclic loading, friction, and wear. Specialized steel
grades with high hardness, strength, and fatigue resistance can extend service
intervals and improve railway operating reliability.
Infrastructure
developers are also increasingly considering lifecycle performance rather than
focusing exclusively on initial material cost. Higher-performance steel
products can potentially reduce maintenance requirements and replacement
frequency, creating opportunities for alloy steel suppliers.
The continued
expansion of infrastructure investment in Asia Pacific, the Middle East, and
other emerging markets is expected to provide sustained demand for long steel
products.
Expansion of
Automotive and Industrial Manufacturing Is Supporting Market Expansion
The growth of
automotive and industrial manufacturing is another major factor supporting the
market.
Automotive
manufacturers use alloy steel in numerous high-load components because these
materials can deliver a combination of strength, fatigue resistance, toughness,
machinability, and dimensional stability.
Long alloy steel
products are processed into gears, shafts, axles, crankshafts, transmission
components, suspension components, steering components, and other critical
parts.
The increasing
emphasis on vehicle efficiency is also influencing steel selection. Automakers
are seeking materials that allow components to maintain structural performance
while reducing weight or dimensions. Advanced alloy steel grades can support
this objective through higher strength-to-weight performance.
Industrial
machinery represents another important demand center. Mining equipment,
construction machinery, agricultural machinery, machine tools, pumps,
compressors, and heavy mechanical systems require components that can tolerate
high loads, vibration, abrasion, and repeated operating cycles.
The growth of
manufacturing in emerging economies is expanding the addressable market for
these products. Industrialization, factory automation, equipment modernization,
and manufacturing-capacity expansion are increasing requirements for engineered
steel components.
As manufacturers
increasingly automate production and adopt precision machining, consistent
metallurgical properties and dimensional quality are becoming increasingly
important purchasing criteria for alloy steel products.
Advanced
Metallurgy, Recycling, and Low-Carbon Steel Production Present Significant
Opportunities
Technological
advancement and the transition toward lower-carbon steel production present
substantial opportunities for the long alloy steel industry.
Steel producers
are investing in electric arc furnaces, scrap-based production, renewable
electricity integration, energy-efficient furnaces, improved process control,
and digital monitoring to reduce energy consumption and emissions.
The increasing
use of recycled steel is particularly relevant because steel can be repeatedly
recycled while retaining its fundamental material properties. Higher scrap
utilization can support circularity while reducing dependence on virgin raw
materials in suitable production routes.
Advanced
metallurgical technologies are also enabling manufacturers to develop
specialized alloy steel grades with tightly controlled compositions and
performance characteristics.
Demand for
higher-value products can provide steelmakers with opportunities to improve
margins while reducing dependence on commodity-grade steel markets.
The energy
transition creates additional applications. Wind turbines, power-generation
equipment, electric-vehicle manufacturing equipment, transmission
infrastructure, hydrogen systems, and other energy technologies require
specialized steel components.
Manufacturers
capable of supplying low-carbon, high-performance, traceable, and
application-specific alloy steel products are therefore positioned to benefit
from the combination of infrastructure modernization and industrial
decarbonization.
Long Alloy Steel Market Scope
|
Report Attributes |
Description |
|
Market Size in 2026 |
USD 751.14 Billion |
|
Market Forecast in 2034 |
USD 966.4 Billion |
|
CAGR % 2026-2034 |
3.2% |
|
Base Year |
2025 |
|
Historic Data |
2021-2025 |
|
Forecast Period |
2026-2034 |
|
Report USP |
Production, Consumption,
Company Share, Company Heatmap, Company Production, Service Type, Growth
Factors and more |
|
Segments Covered |
• By Product Type • By Alloy Type • By Application • By End User |
|
Regional Scope |
● North America |
|
Country Scope |
U.S. |
Long Alloy Steel Market Report
Segmentation Analysis
The global long
alloy steel market industry analysis is segmented by product type, by alloy
type, by application, by end user, and by region.
The Bars
Segment Is Expected to Dominate the Market During the Forecast Period
The Bars
segment accounted for approximately 39.6% of the global long alloy steel
market in 2026, making it the dominant product-type category.

Alloy steel bars
are extensively used in automotive components, machinery, construction
equipment, industrial tools, shafts, gears, fasteners, and other engineered
applications.
The versatility
of bar products allows manufacturers to supply a broad range of diameters,
grades, surface finishes, and heat-treatment conditions. This makes bars
particularly suitable for machining and forging operations.
Automotive and
mechanical engineering industries represent important consumers because alloy
steel bars can be converted into high-strength components that experience
substantial mechanical loads.
Increasing
demand for precision-engineered components is also encouraging producers to
improve dimensional tolerances, surface quality, metallurgical consistency, and
heat-treatment capabilities.
The broad
application base of alloy steel bars is expected to maintain their leading
position during the forecast period.
The Low Alloy
Steel Segment Is Expected to Lead the Market by Alloy Type
The Low Alloy
Steel segment is expected to hold the largest market share due to its
favorable balance of strength, toughness, manufacturability, availability, and
cost.
Low alloy steels
contain controlled quantities of alloying elements that improve mechanical
performance without reaching the higher alloying levels associated with
specialized high-alloy grades.
These steels are
widely used in automotive components, construction machinery, structural
applications, pipelines, pressure-related equipment, and general industrial
manufacturing.
Their relatively
broad availability and cost advantage make them attractive for applications
requiring improved performance compared with carbon steel without the higher
material cost associated with more heavily alloyed grades.
The
Automotive Segment Is Expected to Dominate the Market by Application
The Automotive
segment is expected to represent the largest application category, supported by
extensive use of alloy steel in drivetrain, transmission, suspension, steering,
and structural components.
Automotive
components are subjected to repeated mechanical stresses, vibration, impact,
and temperature changes. Alloy steel provides the combination of strength,
fatigue resistance, toughness, and machinability required for many of these
applications.
The increasing
emphasis on vehicle efficiency and component optimization is also encouraging
automakers and suppliers to adopt higher-strength grades.
Although
electrification is changing vehicle architectures, alloy steel remains relevant
for numerous mechanical and structural components, including gears, shafts,
bearings, fasteners, axles, and other systems.
The
Industrial Manufacturing Segment Is Expected to Dominate the Market by End User
The Industrial
Manufacturing segment represents a major share of the long alloy steel
market because machinery and equipment manufacturers require high-performance
steel for components subjected to demanding mechanical conditions.
Industrial
equipment, mining machinery, construction equipment, agricultural machinery,
machine tools, pumps, compressors, and material-handling systems all utilize
alloy steel components.
The continued
expansion of manufacturing capacity and machinery modernization in emerging
economies is expected to sustain demand.
Infrastructure
and construction, automotive and transportation, and energy industries also
represent significant end-user categories.
The following segments are part of an in-depth analysis of the global Long Alloy Steel Market:
|
Market Segments |
|
|
By Product Type |
●
Bars ●
Rods ●
Wire Rods ●
Rails ●
Structural Sections ●
Others |
|
By
Alloy Type |
●
Low Alloy Steel ●
Medium Alloy Steel ●
High Alloy Steel |
|
By Application |
●
Construction ●
Automotive ●
Mechanical Engineering ●
Energy & Power ●
Railways ●
Oil & Gas ●
Industrial Equipment ●
Others |
|
By End User |
●
Infrastructure & Construction ●
Automotive & Transportation ●
Industrial Manufacturing ●
Energy ●
Others |
Long Alloy Steel Market Share
Analysis By Region
Asia Pacific is projected to hold the largest share of the global long alloy
steel market over the forecast period.
Asia Pacific
accounted for approximately 48.7% of the global market in 2026,
supported by extensive steel production capacity, large automotive and
manufacturing industries, infrastructure investment, construction activity, and
railway development.
China remains the dominant contributor because of its large steelmaking
industry, automotive manufacturing base, construction sector, machinery
production, and extensive infrastructure network.
India is expected to represent one of the region's important growth
markets as infrastructure investment, manufacturing expansion, automotive
production, railway modernization, and industrial development increase demand
for engineered steel products.
Japan and South Korea are important markets because of their
advanced automotive, machinery, shipbuilding, engineering, and manufacturing
industries. Australia also contributes through infrastructure, mining,
energy, and heavy-equipment applications.
Europe represents a significant market supported by automotive
manufacturing, industrial engineering, railway infrastructure, machinery
production, and investments in energy infrastructure. Germany, the U.K.,
France, Italy, Spain, and Switzerland are important regional markets.
European steel
producers are increasingly focusing on energy efficiency, recycled steel,
low-carbon production, and specialized high-performance grades as the region
moves toward stricter industrial-emissions requirements.
North America is expected to maintain steady growth due to infrastructure
investment, automotive manufacturing, energy development, machinery production,
and reshoring of selected industrial activities. The United States
represents the largest market within the region, followed by Canada and Mexico.
The expansion of
electric-vehicle and battery manufacturing facilities is also creating new
requirements for specialized steel products across industrial equipment and
automotive supply chains.
Latin America is expected to experience moderate growth supported by
construction, automotive manufacturing, mining, energy infrastructure, and
industrial development. Brazil, Mexico, and Argentina represent key
markets.
The Middle
East & Africa is an emerging market supported
by infrastructure development, construction, energy projects, transportation
infrastructure, and industrial diversification. Saudi Arabia, the UAE, and
South Africa are expected to remain important markets as investments in
infrastructure and industrial capacity increase.
Long Alloy
Steel Market Competition Landscape Analysis
The long alloy
steel market is competitive, with major producers focusing on product quality,
metallurgical performance, production efficiency, energy consumption,
sustainability, geographic reach, and customized steel grades.
Steel producers
are increasingly investing in advanced electric arc furnaces, continuous
casting, controlled rolling, heat treatment, and digital process-monitoring
systems to improve product consistency and manufacturing efficiency.
Product
differentiation is becoming increasingly important as automotive, machinery,
energy, and infrastructure customers demand steels with precise mechanical
properties and controlled metallurgical characteristics.
Companies are
also expanding specialty-steel portfolios to serve automotive components,
bearings, gears, shafts, railway applications, construction equipment, and
energy systems.
The industry's
competitive environment is being influenced by decarbonization. Steel producers
are investing in hydrogen-based direct reduced iron, electric arc furnace
production, renewable electricity, carbon-capture technologies, and increased
scrap utilization to lower emissions.
Long-term
competitiveness will increasingly depend on a producer's ability to combine
cost-efficient production with reliable quality, lower-carbon manufacturing,
supply-chain security, and customized product development.
Global Long
Alloy Steel Market Recent Developments News
●
In 2026 – Steel producers continued increasing investments in low-carbon
production technologies, including electric arc furnaces, renewable electricity
integration, and greater scrap utilization to reduce emissions.
●
In 2026 – Automotive and industrial steel suppliers continued developing
higher-strength alloy grades designed to improve component durability while
supporting material and weight optimization.
●
In 2025 – Major steel producers expanded digital manufacturing and
process-monitoring technologies to improve quality consistency, production
efficiency, and predictive maintenance.
●
In 2025 – Infrastructure and railway investment across Asia Pacific
continued supporting demand for high-strength long steel products used in
transportation and construction applications.
●
In 2025 – Steel manufacturers increased focus on specialty and value-added
alloy products as competition in conventional steel markets intensified.
The Global
Long Alloy Steel Market is Dominated by a Few Large Companies, Such As
●
ArcelorMittal
●
Nippon Steel Corporation
●
POSCO Holdings Inc.
●
Tata Steel Limited
●
JFE Steel Corporation
●
ThyssenKrupp AG
●
voestalpine AG
●
Hyundai Steel
●
JSW Steel Limited
●
China Baowu Steel Group
Corporation Limited
●
Nucor Corporation
●
United States Steel Corporation
●
Gerdau S.A.
●
Steel Authority of India
Limited
●
Ovako Group
● Others
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
1.
Global Long Alloy Steel
Market Introduction and Market Overview
1.1. Objectives of the Study
1.2. Global Long Alloy Steel Market Scope and Market Estimation
1.2.1.
Global Long Alloy Steel Market
Market Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
1.2.2.
Global Long Alloy Steel Market
Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
1.3. Market Segmentation
1.3.1.
By Product Type of Global Long
Alloy Steel Market
1.3.2.
By Alloy Type of Global Long
Alloy Steel Market
1.3.3.
By Application of Global Long
Alloy Steel Market
1.3.4.
By End User of Global Long
Alloy Steel Market
1.3.5.
Region of Global Long Alloy
Steel Market
1.4. Competition Coverage List of Market Participants
1.5. Market Definition: Long Alloy Steel Market
2.
Executive Summary
2.1. Demand Side Trends
2.2. Key Market Trends
2.3. Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026
– 2034
2.4. Demand and Opportunity Assessment
2.5. Key Developments
2.6. Overview of Regulatory Landscape, Compliance Framework, and Industry
Standards
2.7. Market Entry Strategies
2.8. Market Dynamics
2.8.1.
Drivers
2.8.2.
Limitations
2.8.3.
Opportunities
2.8.4.
Impact Analysis of Drivers and
Restraints
2.9. Porter's Five Forces Analysis
2.10.
PEST Analysis
3.
Global Long Alloy Steel
Market Estimates & Historical Trend Analysis (2021 - 2025)
4.
Global Long Alloy Steel
Market Estimates & Forecast Trend Analysis, by Product Type
4.1. Global Long Alloy Steel Market Revenue (US$ Million) Estimates and
Forecasts, by Product Type, 2021 - 2034
4.1.1.
Bars
4.1.2.
Rods
4.1.3.
Wire Rods
4.1.4.
Rails
4.1.5.
Structural Sections
4.1.6.
Others
5.
Global Long Alloy Steel
Market Estimates & Forecast Trend Analysis, by Alloy Type
5.1. Global Long Alloy Steel Market Revenue (US$ Million) Estimates and
Forecasts, by Alloy Type, 2021 - 2034
5.1.1.
Low Alloy Steel
5.1.2.
Medium Alloy Steel
5.1.3.
High Alloy Steel
6.
Global Long Alloy Steel
Market Estimates & Forecast Trend Analysis, by Application
6.1. Global Long Alloy Steel Market Revenue (US$ Million) Estimates and
Forecasts, by Application, 2021 - 2034
6.1.1.
Construction
6.1.2.
Automotive
6.1.3.
Mechanical Engineering
6.1.4.
Energy & Power
6.1.5.
Railways
6.1.6.
Oil & Gas
6.1.7.
Industrial Equipment
6.1.8.
Others
7.
Global Long Alloy Steel
Market Estimates & Forecast Trend Analysis, by End User
7.1. Global Long Alloy Steel Market Revenue (US$ Million) Estimates and
Forecasts, by End User, 2021 - 2034
7.1.1.
Infrastructure &
Construction
7.1.2.
Automotive & Transportation
7.1.3.
Industrial Manufacturing
7.1.4.
Energy
7.1.5.
Others
8.
Global Long Alloy Steel
Market Estimates & Forecast Trend Analysis, by Region
8.1. Global Long Alloy Steel Market Revenue (US$ Million) Estimates and
Forecasts, by Region, 2021 - 2034
8.1.1.
North America
8.1.2.
Europe
8.1.3.
Asia Pacific
8.1.4.
Middle East & Africa
8.1.5.
Latin America
9.
North America Long Alloy
Steel Market: Estimates & Forecast Trend Analysis
9.1. North America Long Alloy Steel Market Assessments & Key Findings
9.1.1.
North America Long Alloy Steel
Market Introduction
9.1.2.
North America Long Alloy Steel
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
9.1.2.1.
By Product Type
9.1.2.2.
By Alloy Type
9.1.2.3.
By Application
9.1.2.4.
By End User
9.1.2.5.
By Country
9.1.2.5.1.
The U.S.
9.1.2.5.2.
Canada
10. Europe Long Alloy Steel Market: Estimates & Forecast Trend
Analysis
10.1.
Europe Long Alloy Steel Market
Assessments & Key Findings
10.1.1.
Europe Long Alloy Steel Market
Introduction
10.1.2.
Europe Long Alloy Steel Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
10.1.2.1.
By Product Type
10.1.2.2.
By Alloy Type
10.1.2.3.
By Application
10.1.2.4.
By End User
10.1.2.5.
By Country
10.1.2.5.1.
Germany
10.1.2.5.2.
Italy
10.1.2.5.3.
The U.K.
10.1.2.5.4.
France
10.1.2.5.5.
Spain
10.1.2.5.6.
Switzerland
10.1.2.5.7.
Rest of Europe
11. Asia Pacific Long Alloy Steel Market: Estimates & Forecast Trend
Analysis
11.1.
Asia Pacific Long Alloy Steel
Market Assessments & Key Findings
11.1.1.
Asia Pacific Long Alloy Steel
Market Introduction
11.1.2.
Asia Pacific Long Alloy Steel
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
11.1.2.1.
By Product Type
11.1.2.2.
By Alloy Type
11.1.2.3.
By Application
11.1.2.4.
By End User
11.1.2.5.
By Country
11.1.2.5.1.
China
11.1.2.5.2.
Japan
11.1.2.5.3.
India
11.1.2.5.4.
Australia
11.1.2.5.5.
South Korea
11.1.2.5.6.
Rest of Asia Pacific
12. Middle East & Africa Long Alloy Steel Market: Estimates &
Forecast Trend Analysis
12.1.
Middle East & Africa Long
Alloy Steel Market Assessments & Key Findings
12.1.1.
Middle East & Africa Long
Alloy Steel Market Introduction
12.1.2.
Middle East & Africa Long
Alloy Steel Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
12.1.2.1.
By Product Type
12.1.2.2.
By Alloy Type
12.1.2.3.
By Application
12.1.2.4.
By End User
12.1.2.5.
By Country
12.1.2.5.1.
UAE
12.1.2.5.2.
Saudi Arabia
12.1.2.5.3.
South Africa
12.1.2.5.4.
Rest of Middle East &
Africa
13. Latin America Long Alloy Steel Market: Estimates & Forecast
Trend Analysis
13.1.
Latin America Long Alloy Steel
Market Assessments & Key Findings
13.1.1.
Latin America Long Alloy Steel
Market Introduction
13.1.2.
Latin America Long Alloy Steel
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
13.1.2.1.
By Product Type
13.1.2.2.
By Alloy Type
13.1.2.3.
By Application
13.1.2.4.
By End User
13.1.2.5.
By Country
13.1.2.5.1.
Brazil
13.1.2.5.2.
Mexico
13.1.2.5.3.
Argentina
13.1.2.5.4.
Rest of Latin America
14. Competition Landscape
14.1.
Global Long Alloy Steel Market
Product Mapping
14.2.
Global Long Alloy Steel Market
Concentration Analysis, by Leading Players / Innovators / Emerging Players /
New Entrants
14.3.
Global Long Alloy Steel Market
Tier Structure Analysis
14.4.
Global Long Alloy Steel Market
Concentration & Company Market Shares (%) Analysis, 2026
15. Company Profiles
15.1.
ArcelorMittal
15.1.1.
Company Overview & Key
Stats
15.1.2.
Financial Performance &
KPIs
15.1.3.
Product Portfolio
15.1.4.
SWOT Analysis
15.1.5.
Business Strategy & Recent
Developments
*Similar details would be provided for all
the players mentioned below
15.2.
Nippon Steel Corporation
15.3.
POSCO Holdings Inc.
15.4.
Tata Steel Limited
15.5.
JFE Steel Corporation
15.6.
ThyssenKrupp AG
15.7.
voestalpine AG
15.8.
Hyundai Steel
15.9.
JSW Steel Limited
15.10.
China Baowu Steel Group
Corporation Limited
15.11.
Nucor Corporation
15.12.
United States Steel Corporation
15.13.
Gerdau S.A.
15.14.
Steel Authority of India
Limited
15.15.
Ovako Group
15.16.
Others
16. Research Findings & Conclusion
17. Assumptions & Acronyms Used
18. Research Methodology
18.1.
External Databases
18.2.
Internal Proprietary Database
18.3.
Primary Research
18.4.
Secondary Research
18.5.
Assumptions
18.6.
Limitations
18.7.
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
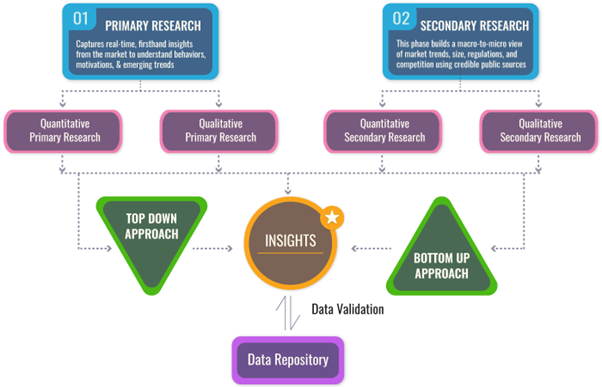
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables