Piston Engine Aircraft Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By Aircraft Type (Single-Engine Piston Aircraft, Multi-Engine Piston Aircraft); By Maximum Take-Off Weight (Less than 1,000 Kg, 1,000–2,000 Kg, More than 2,000 Kg); By Application (Pilot Training, Personal & Recreational Flying, Aerial Surveying, Agriculture & Forestry, Air Taxi & Charter, Special Missions); By End User (Civil/Commercial, Government & Military); and Geography
2026-09-29
Aerospace & Defense
Ekta Chaurasia (Team Lead)
Description
Piston Engine Aircraft Market
Overview
The global Piston
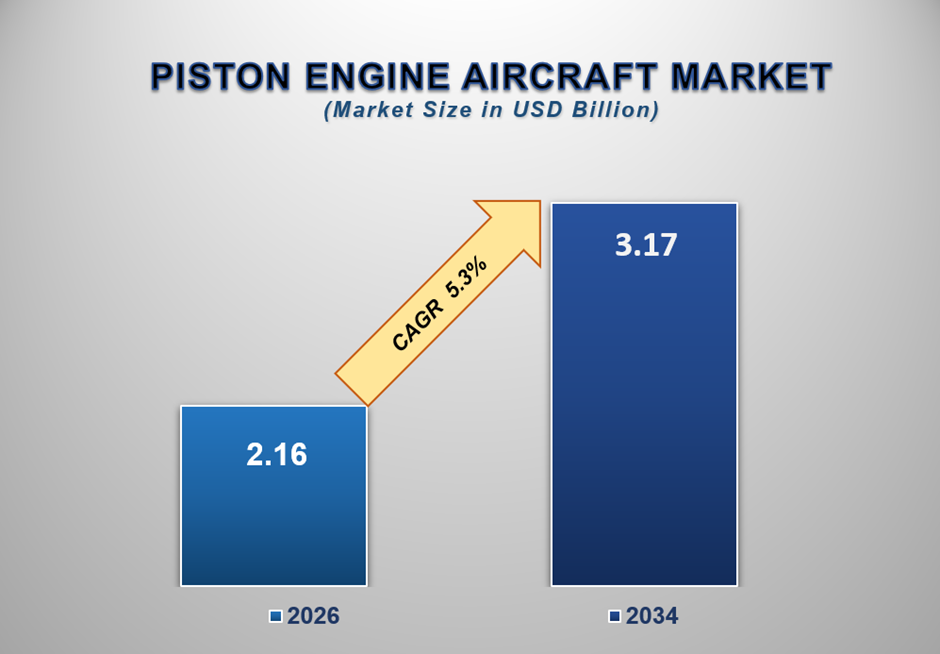
Engine Aircraft Market was valued at USD 2.16 billion in 2026 and is
projected to reach USD 3.17 billion by 2034, expanding at a CAGR of
5.3% during the forecast period. The market is experiencing steady growth
due to increasing demand for pilot training aircraft, expansion of general
aviation infrastructure, rising recreational flying activities, growing demand
for affordable private aviation, replacement of aging aircraft fleets, and
continued improvements in avionics, propulsion efficiency, and aircraft safety
systems.
Piston engine
aircraft are light aircraft powered by reciprocating internal-combustion
engines that convert fuel combustion into mechanical power to drive propellers.
These aircraft are widely used for pilot training, private flying, recreational
aviation, aerial surveying, agricultural operations, charter services, and
specialized missions.
The market
continues to benefit from the comparatively lower acquisition and operating
costs of piston-powered aircraft compared with larger turbine-powered
platforms. Their relatively simple mechanical architecture, smaller airfield
requirements, and suitability for short-distance operations make them
particularly relevant to flight schools, private owners, flying clubs, and
specialized aviation operators.
Pilot training
represents one of the most important demand generators. Flight schools and
aviation academies require aircraft that can withstand frequent flight cycles
while maintaining manageable operating and maintenance costs. Single-engine
piston aircraft are particularly suited to primary flight instruction because
they offer relatively straightforward handling characteristics and lower
operating expenses.
The continuing
global shortage and replacement requirement for qualified pilots is also
supporting investment in training fleets. As airlines and commercial aviation
operators maintain recruitment pipelines, flight schools are expanding or
renewing training fleets, creating recurring demand for new and replacement
piston aircraft.
Technological
improvements are changing the capabilities of modern piston aircraft.
Manufacturers are increasingly integrating glass cockpits, digital flight
displays, advanced navigation systems, autopilot functions, electronic engine
monitoring, enhanced situational-awareness systems, and other avionics
technologies. These systems can improve pilot workload management and
operational awareness while bringing training aircraft closer to the cockpit
environments used in more advanced aviation platforms.
Safety
technology is also becoming an important product differentiator. Modern
aircraft increasingly incorporate enhanced flight-control systems, improved
structural protection, advanced weather information, digital engine monitoring,
and emergency-response technologies. These developments are helping
manufacturers position piston aircraft as technologically capable platforms
rather than basic entry-level aircraft.
The recreational
aviation segment is another source of demand. Private aircraft ownership,
flying clubs, adventure aviation, and personal transportation continue to
create opportunities for manufacturers offering efficient and technologically
advanced piston aircraft.
The expansion of
general aviation infrastructure in emerging markets is also creating
longer-term opportunities. New airports, improved aviation services, growing
pilot-training ecosystems, and rising disposable incomes can increase
accessibility to general aviation and stimulate aircraft demand.
At the same
time, the industry is dealing with several challenges. Aircraft certification
requirements, shortages of skilled aviation labor, supply-chain constraints for
engines and avionics, high aircraft acquisition costs, fuel-price volatility,
and the transition toward lower-emission aviation technologies can affect
purchasing decisions.
Engine
manufacturers and aircraft companies are consequently exploring improvements in
fuel efficiency, electronic ignition, diesel and Jet-A-compatible propulsion,
hybrid-electric technologies, and other approaches that can reduce operating
costs and improve the long-term viability of piston-powered aircraft.
As general
aviation infrastructure expands and manufacturers continue to modernize
aircraft with advanced avionics and more efficient propulsion technologies, the
piston engine aircraft market is expected to maintain moderate and sustained
growth through 2034.
Piston Engine Aircraft Market Drivers
and Opportunities
Growing
Demand for Pilot Training and Replacement Aircraft Is Driving Market Growth
The expansion of
pilot training activities is one of the primary factors supporting the piston
engine aircraft market.
Flight training
organizations require reliable aircraft for ab-initio training, instrument
instruction, commercial pilot preparation, and advanced ratings. Piston-powered
aircraft remain particularly attractive for these applications because of their
relatively manageable acquisition, fuel, maintenance, and operating costs.
The increasing
requirement for qualified pilots is encouraging aviation academies,
universities, independent flight schools, and commercial training organizations
to expand their fleets. Training organizations also need replacement aircraft
as older airframes accumulate flight hours and maintenance requirements.
Single-engine
aircraft are especially important in primary training because students can
develop fundamental flight skills on aircraft that are comparatively simpler to
operate. Multi-engine piston aircraft remain important for advanced training
and multi-engine ratings.
Manufacturers
are responding by introducing updated versions of established training
platforms with modern avionics, improved engine technologies, digital displays,
and enhanced safety features. The continued use of aircraft such as the Cessna
172 and Piper Archer in training environments demonstrates the long-term
importance of piston platforms to aviation education.
The replacement
cycle of aging general aviation fleets provides an additional source of demand.
Owners and operators increasingly consider newer aircraft when maintenance
requirements, component availability, fuel consumption, and avionics
obsolescence make continued operation of older aircraft less economical.
Expansion of
Recreational Aviation and General Aviation Infrastructure Is Supporting Market
Expansion
The growing
interest in recreational flying, personal aviation, flying clubs, and
light-aircraft operations is supporting market development.
Piston aircraft
provide private owners with relatively accessible entry points into aircraft
ownership. Their suitability for short-distance travel, recreational flying,
personal transportation, and weekend aviation activities makes them relevant
across a broad general aviation customer base.
Flying clubs are
also important because they allow multiple users to share aircraft ownership
and operating costs. Increased participation in recreational aviation can
therefore support aircraft utilization and create demand for new aircraft.
Infrastructure
development is particularly important in emerging aviation markets. The
expansion of general aviation airports, maintenance facilities, flight schools,
aviation services, and pilot-training centers can make piston aircraft more
commercially viable.
Asia Pacific
presents an important long-term opportunity as aviation infrastructure develops
and governments and industry participants expand general aviation capabilities.
China's authorization of additional general aviation airports and the expansion
of aviation training activity are examples of developments that can support
future fleet growth.
Aircraft
manufacturers are also benefiting from demand for versatile platforms that can
perform several missions. A single piston aircraft can potentially be used for
training, personal travel, aerial photography, surveying, and recreational
activities, improving utilization and investment value for smaller operators.
Advanced
Avionics, Fuel-Efficient Propulsion, and Specialized Applications Present
Significant Opportunities
Technological
modernization presents significant opportunities for the piston engine aircraft
industry.
Manufacturers
are increasingly integrating advanced avionics, digital cockpits, synthetic
vision, autopilot systems, electronic engine monitoring, and enhanced
navigation capabilities into piston aircraft. These technologies improve
situational awareness and can reduce pilot workload while supporting safer and
more efficient operations.
Propulsion
technology is also evolving. Diesel and Jet-A-compatible piston engines are
attracting interest in markets where aviation gasoline is expensive, difficult
to source, or undergoing fuel-transition changes. These engines can provide
operators with additional fuel flexibility and potentially improve operating
economics.
The emergence of
electronic ignition and other engine-control technologies is creating
additional opportunities for improving reliability, efficiency, and maintenance
performance.
Specialized
applications such as aerial surveying, agriculture, environmental monitoring,
mapping, patrol, medical transport, and light utility operations can further
broaden the market beyond traditional private aviation and training.
Manufacturers
that combine low operating costs with advanced avionics, mission flexibility,
improved safety, and efficient propulsion are therefore positioned to capture
demand from both traditional general aviation users and newer specialized
operators.
Piston Engine Aircraft Market Scope
|
Report Attributes |
Description |
|
Market Size in 2026 |
USD 2.16 Billion |
|
Market Forecast in 2034 |
USD 3.17 Billion |
|
CAGR % 2026-2034 |
5.3% |
|
Base Year |
2025 |
|
Historic Data |
2021-2025 |
|
Forecast Period |
2026-2034 |
|
Report USP |
Production, Consumption,
Company Share, Company Heatmap, Company Production, Service Type, Growth
Factors and more |
|
Segments Covered |
• By Aircraft Type |
|
Regional Scope |
● North America |
|
Country Scope |
U.S. |
Piston Engine Aircraft Market Report
Segmentation Analysis
The global
piston engine aircraft market industry analysis is segmented by aircraft type,
by maximum take-off weight, by application, by end user, and by region.
The
Single-Engine Piston Aircraft Segment Is Expected to Dominate the Market During
the Forecast Period
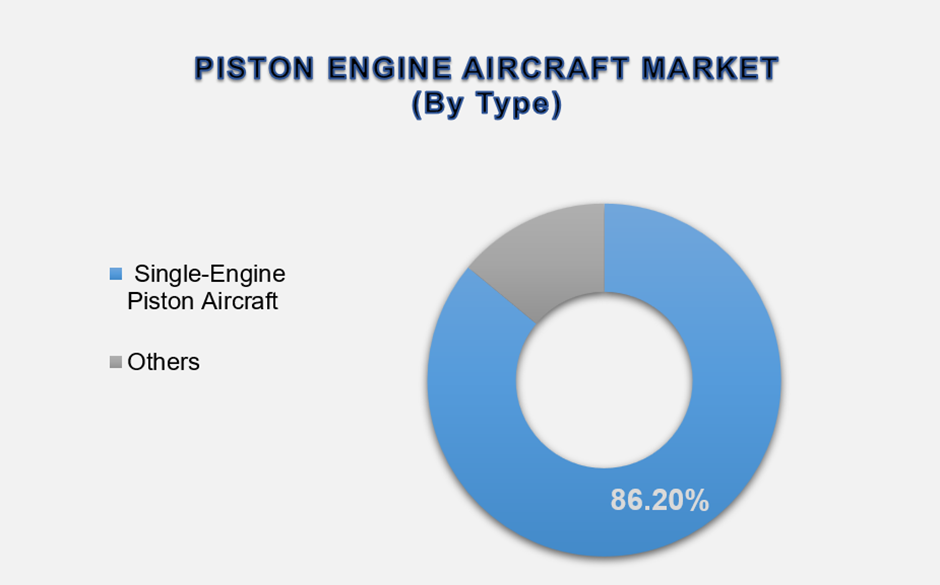
The Single-Engine
Piston Aircraft segment accounted for approximately 86.2% of the
global market in 2025, making it the dominant aircraft-type category.
Single-engine
piston aircraft are widely used for pilot training, personal flying,
recreational aviation, aerial surveying, and light utility operations.
Their
comparatively lower purchase price, simpler mechanical architecture, reduced
fuel consumption, and lower maintenance requirements make them attractive to
flight schools and private owners.
Flight-training
organizations particularly favor single-engine platforms for primary
instruction because students can develop fundamental flying skills without the
higher operating costs associated with multi-engine aircraft.
Modern
single-engine aircraft are also increasingly equipped with advanced avionics,
autopilot systems, digital displays, and enhanced safety technologies, allowing
manufacturers to combine traditional piston propulsion with modern cockpit
capabilities.
The segment is
expected to maintain its leading position because of its broad application base
and strong demand from training organizations and private aviation users.
The More than
2,000 Kg Segment Is Expected to Lead the Market by Maximum Take-Off Weight
The more than
2,000 kg segment is expected to hold a significant share of the market
because aircraft within this category provide higher payload capacity, greater
range, and increased capability for specialized and multi-engine operations.
These aircraft
can serve advanced training, charter, utility, special missions, and other
operations where greater payload and performance are required.
Higher-weight
aircraft can accommodate more passengers, equipment, fuel, and specialized
mission systems, making them valuable for commercial operators and government
agencies.
Demand for these
aircraft is also supported by operators requiring greater operational
flexibility and redundancy, particularly for specialized missions and advanced
flight training.
The
Commercial Segment Is Expected to Dominate the Market by End User
The Civil/Commercial
segment represents a major share of the piston engine aircraft market because
flight schools, charter operators, aerial-work companies, flying clubs, and
other commercial aviation organizations account for substantial aircraft
utilization.
Pilot-training
organizations remain particularly important because piston aircraft are widely
used for primary and advanced training. Commercial operators also use piston
platforms for aerial surveying, agricultural activities, tourism,
short-distance charter operations, and specialized services.
The
comparatively lower operating costs of piston aircraft make them suitable for
organizations that require frequent short-duration flights and do not require
the performance capabilities of turbine aircraft.
Government and
military organizations also represent an important customer group, particularly
for surveillance, liaison, training, observation, and specialized missions.
The following segments are part of an in-depth analysis of the global Piston Engine Aircraft Market:
|
Market Segments |
|
|
By Aircraft
Type |
●
Single-Engine Piston Aircraft ●
Multi-Engine Piston Aircraft |
|
By
Maximum
Take-Off Weight |
●
Less than 1,000 Kg ●
1,000–2,000 Kg ●
More than 2,000 Kg |
|
By Application |
●
Pilot Training ●
Personal & Recreational Flying ●
Aerial Surveying ●
Agriculture & Forestry ●
Air Taxi & Charter ●
Special Missions |
|
By End User |
●
Civil/Commercial ●
Government & Military |
Piston Engine Aircraft Market Share
Analysis By Region
North America is projected to hold the largest share of the global piston engine
aircraft market over the forecast period.
North America
accounted for approximately 38.4% of the global market in 2025,
supported by its extensive general aviation infrastructure, large installed
aircraft fleet, established flight-training ecosystem, developed maintenance
network, and strong recreational aviation culture.
The United
States remains the dominant contributor within the region. The country has
a highly developed network of general aviation airports, flight schools,
aircraft maintenance providers, aircraft manufacturers, and aviation service
companies.
The large number
of private aircraft owners and flying clubs also supports demand for piston
aircraft. Pilot-training organizations represent an especially important source
of recurring demand as aviation schools renew and expand their training fleets.
Europe represents a significant market supported by flight training,
recreational aviation, aircraft replacement, aerial surveying, and specialized
general aviation activities. Germany, the U.K., France, Italy, Spain, and
Switzerland are important regional markets.
European
manufacturers also have strong capabilities in light aircraft and advanced
piston aviation. Demand is increasingly influenced by aircraft efficiency,
modern avionics, safety technologies, and the transition toward lower-carbon
aviation.
Asia Pacific is expected to register strong growth during the forecast period.
Expanding aviation infrastructure, increasing pilot-training activity, rising
disposable incomes, development of general aviation airports, and growing
interest in recreational aviation are supporting regional demand.
China, India,
Japan, South Korea, and Australia represent
important markets. China has significant long-term potential because of its
expanding general aviation infrastructure, while Australia maintains strong
demand for light aircraft across training, recreational flying, agriculture,
and remote-area operations.
Latin America is expected to experience steady growth due to the extensive use of
light aircraft for agriculture, surveying, regional connectivity, pilot
training, and private aviation. Brazil, Mexico, and Argentina represent
key markets.
The region's
large agricultural sector creates additional opportunities for piston aircraft
used in crop monitoring, aerial surveying, and agricultural support activities.
Middle East
& Africa represents an emerging market
supported by pilot training, private aviation, government operations,
surveillance, aerial surveying, and specialized missions. Saudi Arabia, the
UAE, and South Africa are expected to remain important markets as aviation
infrastructure and general aviation activities develop.
Piston Engine
Aircraft Market Competition Landscape Analysis
The piston
engine aircraft market is competitive, with manufacturers focusing on aircraft
performance, acquisition cost, operating economics, safety, avionics, cabin
comfort, range, and mission flexibility.
Companies are
increasingly differentiating aircraft through advanced glass cockpits, digital
navigation systems, autopilot capabilities, improved engine monitoring,
enhanced safety systems, and more efficient propulsion technologies.
The competitive
environment includes established aircraft manufacturers as well as specialized
general aviation companies. Key players such as Textron Aviation, Piper
Aircraft, Cirrus Aircraft, and Diamond Aircraft maintain strong positions
across training, private aviation, and general aviation applications.
Engine
manufacturers and suppliers are also important to the competitive ecosystem.
Companies are investing in electronic ignition, fuel-efficient engines, diesel
and Jet-A-compatible propulsion, improved reliability, and longer maintenance
intervals.
Manufacturers
are also increasingly targeting flight schools with aircraft designed around
lower hourly operating costs, simplified maintenance, durable airframes, and
modern training avionics.
Strategic
differentiation is therefore shifting beyond aircraft design alone. Companies
that can provide strong after-sales support, spare-parts availability,
maintenance networks, pilot-training solutions, financing options, and digital
fleet-management capabilities can strengthen customer retention.
Global Piston
Engine Aircraft Market Recent Developments News
●
In August 2026 – Industry market analysis highlighted continued growth in advanced
avionics integration, including glass cockpits, synthetic vision, and digital
autopilot systems across modern piston aircraft.
●
In 2026 – Piper's continued development of Jet-A-compatible diesel piston
propulsion highlighted the industry's movement toward fuel flexibility and
potentially lower operating costs for training fleets.
●
In 2026 – Manufacturers continued to target the expanding flight-training
market with updated single-engine and multi-engine aircraft designed around
lower operating costs and modern cockpit systems.
●
In 2025 – Single-engine piston aircraft remained the dominant aircraft-type
category, supported by their widespread use in pilot training, private
aviation, and recreational flying.
●
In 2025 – North America maintained its position as the leading regional
market, supported by extensive general aviation infrastructure and high
piston-aircraft utilization.
The Global
Piston Engine Aircraft Market is Dominated by a Few Large Companies, Such As
●
Textron Aviation Inc.
●
Piper Aircraft, Inc.
●
Cirrus Aircraft
●
Diamond Aircraft Industries
GmbH
●
Lycoming Engines
●
Continental Aerospace
Technologies
●
Tecnam S.p.A.
●
Flight Design GmbH
●
Mooney International
Corporation
●
Vulcanair S.p.A.
●
BRM Aero
●
American Champion Aircraft
Corporation
●
Van's Aircraft
●
Daher
● Others
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
1.
Global Piston Engine
Aircraft Market Introduction and Market Overview
1.1. Objectives of the Study
1.2. Global Piston Engine Aircraft Market Scope and Market Estimation
1.2.1.
Global Piston Engine Aircraft
Market Size (US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
1.2.2.
Global Piston Engine Aircraft
Market Revenue Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
1.3. Market Segmentation
1.3.1.
Aircraft Type of Global Piston
Engine Aircraft Market
1.3.2.
Maximum Take-Off Weight of
Global Piston Engine Aircraft Market
1.3.3.
Application of Global Piston
Engine Aircraft Market
1.3.4.
End User of Global Piston
Engine Aircraft Market
1.3.5.
Region of Global Piston Engine
Aircraft Market
1.4. Competition Coverage List of Market Participants
1.5. Market Definition: Piston Engine Aircraft Market
2.
Executive Summary
2.1. Demand Side Trends
2.2. Key Market Trends
2.3. Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026
– 2034
2.4. Demand and Opportunity Assessment
2.5. Key Developments
2.6. Overview of Regulatory Landscape, Compliance Framework, and Industry
Standards
2.7. Market Entry Strategies
2.8. Market Dynamics
2.8.1.
Drivers
2.8.2.
Limitations
2.8.3.
Opportunities
2.8.4.
Impact Analysis of Drivers and
Restraints
2.9. Porter's Five Forces Analysis
2.10.
PEST Analysis
3.
Global Piston Engine
Aircraft Market Estimates & Historical Trend Analysis (2021 - 2025)
4.
Global Piston Engine
Aircraft Market Estimates & Forecast Trend Analysis, by Aircraft Type
4.1. Global Piston Engine Aircraft Market Revenue (US$ Million) Estimates
and Forecasts, by Aircraft Type, 2021 - 2034
4.1.1.
Single-Engine Piston Aircraft
4.1.2.
Multi-Engine Piston Aircraft
5.
Global Piston Engine
Aircraft Market Estimates & Forecast Trend Analysis, by Maximum Take-Off
Weight
5.1. Global Piston Engine Aircraft Market Revenue (US$ Million) Estimates
and Forecasts, by Maximum Take-Off Weight, 2021 - 2034
5.1.1.
Less than 1,000 Kg
5.1.2.
1,000–2,000 Kg
5.1.3.
More than 2,000 Kg
6.
Global Piston Engine
Aircraft Market Estimates & Forecast Trend Analysis, by Application
6.1. Global Piston Engine Aircraft Market Revenue (US$ Million) Estimates
and Forecasts, by Application, 2021 - 2034
6.1.1.
Pilot Training
6.1.2.
Personal & Recreational
Flying
6.1.3.
Aerial Surveying
6.1.4.
Agriculture & Forestry
6.1.5.
Air Taxi & Charter
6.1.6.
Special Missions
7.
Global Piston Engine
Aircraft Market Estimates & Forecast Trend Analysis, by End User
7.1. Global Piston Engine Aircraft Market Revenue (US$ Million) Estimates
and Forecasts, by End User, 2021 - 2034
7.1.1.
Civil/Commercial
7.1.2.
Government & Military
8.
Global Piston Engine
Aircraft Market Estimates & Forecast Trend Analysis, by Region
8.1. Global Piston Engine Aircraft Market Revenue (US$ Million) Estimates
and Forecasts, by Region, 2021 - 2034
8.1.1.
North America
8.1.2.
Europe
8.1.3.
Asia Pacific
8.1.4.
Middle East & Africa
8.1.5.
Latin America
9.
North America Piston
Engine Aircraft Market: Estimates & Forecast Trend Analysis
9.1. North America Piston Engine Aircraft Market Assessments & Key
Findings
9.1.1.
North America Piston Engine
Aircraft Market Introduction
9.1.2.
North America Piston Engine
Aircraft Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
9.1.2.1.
By Aircraft Type
9.1.2.2.
By Maximum Take-Off Weight
9.1.2.3.
By Application
9.1.2.4.
By End User
9.1.2.5.
By Country
9.1.2.5.1.
The U.S.
9.1.2.5.2.
Canada
10. Europe Piston Engine Aircraft Market: Estimates & Forecast Trend
Analysis
10.1.
Europe Piston Engine Aircraft
Market Assessments & Key Findings
10.1.1.
Europe Piston Engine Aircraft
Market Introduction
10.1.2.
Europe Piston Engine Aircraft
Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
10.1.2.1.
By Aircraft Type
10.1.2.2.
By Maximum Take-Off Weight
10.1.2.3.
By Application
10.1.2.4.
By End User
10.1.2.5.
By Country
10.1.2.5.1.
Germany
10.1.2.5.2.
Italy
10.1.2.5.3.
The U.K.
10.1.2.5.4.
France
10.1.2.5.5.
Spain
10.1.2.5.6.
Switzerland
10.1.2.5.7.
Rest of Europe
11. Asia Pacific Piston Engine Aircraft Market: Estimates & Forecast
Trend Analysis
11.1.
Asia Pacific Piston Engine
Aircraft Market Assessments & Key Findings
11.1.1.
Asia Pacific Piston Engine
Aircraft Market Introduction
11.1.2.
Asia Pacific Piston Engine
Aircraft Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
11.1.2.1.
By Aircraft Type
11.1.2.2.
By Maximum Take-Off Weight
11.1.2.3.
By Application
11.1.2.4.
By End User
11.1.2.5.
By Country
11.1.2.5.1.
China
11.1.2.5.2.
Japan
11.1.2.5.3.
India
11.1.2.5.4.
Australia
11.1.2.5.5.
South Korea
11.1.2.5.6.
Rest of Asia Pacific
12. Middle East & Africa Piston Engine Aircraft Market: Estimates
& Forecast Trend Analysis
12.1.
Middle East & Africa Piston
Engine Aircraft Market Assessments & Key Findings
12.1.1.
Middle East & Africa Piston
Engine Aircraft Market Introduction
12.1.2.
Middle East & Africa Piston
Engine Aircraft Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
12.1.2.1.
By Aircraft Type
12.1.2.2.
By Maximum Take-Off Weight
12.1.2.3.
By Application
12.1.2.4.
By End User
12.1.2.5.
By Country
12.1.2.5.1.
UAE
12.1.2.5.2.
Saudi Arabia
12.1.2.5.3.
South Africa
12.1.2.5.4.
Rest of Middle East &
Africa
13. Latin America Piston Engine Aircraft Market: Estimates &
Forecast Trend Analysis
13.1.
Latin America Piston Engine
Aircraft Market Assessments & Key Findings
13.1.1.
Latin America Piston Engine
Aircraft Market Introduction
13.1.2.
Latin America Piston Engine
Aircraft Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
13.1.2.1.
By Aircraft Type
13.1.2.2.
By Maximum Take-Off Weight
13.1.2.3.
By Application
13.1.2.4.
By End User
13.1.2.5.
By Country
13.1.2.5.1.
Brazil
13.1.2.5.2.
Mexico
13.1.2.5.3.
Argentina
13.1.2.5.4.
Rest of Latin America
14. Competition Landscape
14.1.
Global Piston Engine Aircraft
Market Product Mapping
14.2.
Global Piston Engine Aircraft
Market Concentration Analysis, by Leading Players / Innovators / Emerging
Players / New Entrants
14.3.
Global Piston Engine Aircraft
Market Tier Structure Analysis
14.4.
Global Piston Engine Aircraft
Market Concentration & Company Market Shares (%) Analysis, 2026
15. Company Profiles
15.1.
Textron Aviation Inc.
15.1.1.
Company Overview & Key
Stats
15.1.2.
Financial Performance &
KPIs
15.1.3.
Product Portfolio
15.1.4.
SWOT Analysis
15.1.5.
Business Strategy & Recent
Developments
*Similar details would be provided for all
the players mentioned below
15.2.
Piper Aircraft, Inc.
15.3.
Cirrus Aircraft
15.4.
Diamond Aircraft Industries
GmbH
15.5.
Lycoming Engines
15.6.
Continental Aerospace
Technologies
15.7.
Tecnam S.p.A.
15.8.
Flight Design GmbH
15.9.
Mooney International
Corporation
15.10.
Vulcanair S.p.A.
15.11.
BRM Aero
15.12.
American Champion Aircraft
Corporation
15.13.
Van's Aircraft
15.14.
Daher
15.15.
Others
16. Research Findings & Conclusion
17. Assumptions & Acronyms Used
18. Research Methodology
18.1.
External Databases
18.2.
Internal Proprietary Database
18.3.
Primary Research
18.4.
Secondary Research
18.5.
Assumptions
18.6.
Limitations
18.7.
Report FAQs
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
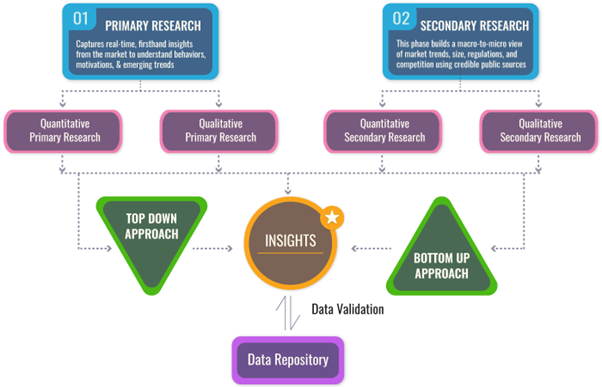
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables