Silo Bags Market Size and Forecast (2026–2034), Global and Regional Growth, Trend, Share and Industry Analysis Report Coverage; By Type (Grain Silo Bags, Silage Silo Bags, Forage Silo Bags, Others); By Capacity (Small, Medium, Large); By Application (Grains, Maize, Wheat, Soybean, Animal Feed, Forage, Others); and Geography
2026-10-22
Consumer Products
Aishwarya Panbude (Research Analyst)
Description
Silo Bags Market Overview
The global Silo
Bags Market was valued at USD 0.3719 billion in 2026 and is
projected to reach USD 0.585 billion by 2034, expanding at a CAGR of
5.8% during the forecast period. The market is benefiting from increasing
agricultural production, rising demand for on-farm grain storage, growing
concerns regarding post-harvest losses, expansion of commercial farming, and
the need for flexible and cost-efficient alternatives to conventional
grain-storage infrastructure.
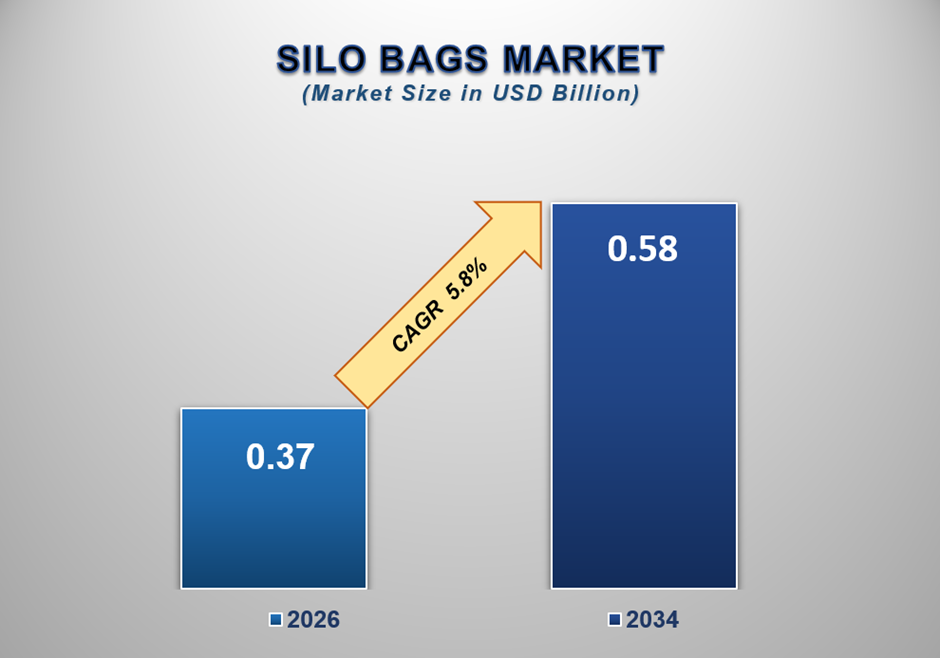
Silo bags are
large, flexible plastic storage systems used primarily for preserving harvested
grains, silage, forage, and other agricultural commodities. These bags are
generally manufactured using multilayer polyethylene films that provide
strength, flexibility, moisture resistance, and protection from external
environmental conditions.
The growing
requirement for temporary and decentralized grain-storage solutions is one of
the major factors supporting market development. Farmers and agricultural
businesses can deploy silo bags close to harvesting locations, reducing the
immediate need to transport crops to distant storage facilities.
Silo bags are
particularly valuable during periods of high harvest volumes when conventional
storage infrastructure may have insufficient capacity. Farmers can use flexible
storage systems to temporarily hold grains and other agricultural commodities
until they can be sold, processed, or transported to permanent storage
facilities.
The increasing
production of wheat, maize, soybeans, barley, and other major crops is creating
additional demand for flexible agricultural storage solutions. Expansion of
commercial agriculture and mechanized harvesting is also encouraging farmers to
adopt storage systems capable of handling large quantities of harvested crops.
Another
important factor is the ability of silo bags to provide a relatively flexible
storage option compared with permanent structures. Their installation does not
require the same level of fixed infrastructure associated with traditional
silos, making them useful for farms and agricultural operations where storage
capacity needs fluctuate seasonally.
Silo bags also
support decentralized agricultural logistics. Harvested crops can be stored
near production areas, allowing farmers to manage transportation schedules and
market timing more efficiently. This characteristic can be particularly useful
in regions with large agricultural areas and seasonal harvest concentrations.
Advancements in
polyethylene film technology are further improving the performance of silo
bags. Manufacturers are developing multilayer structures with greater puncture
resistance, ultraviolet protection, mechanical strength, and barrier
performance to help protect stored commodities.
Growing
attention toward food security and post-harvest management is expected to
create additional opportunities for the market. Governments, agricultural
organizations, cooperatives, and commercial farmers are increasingly focused on
reducing losses between harvesting and consumption.
As agricultural
producers continue seeking flexible storage capacity, efficient post-harvest
management, and alternatives to conventional storage infrastructure, the global
silo bags market is expected to maintain steady growth through 2034.
Silo Bags Market Drivers and
Opportunities
Rising
Agricultural Production and Increasing Need for On-Farm Storage Are Driving
Market Growth
The expansion of
global agricultural production is one of the key factors supporting demand for
silo bags.
Increasing
cultivation of maize, wheat, soybean, barley, rice, and other grains is
creating a greater requirement for storage capacity following harvesting. In
many agricultural regions, available permanent storage facilities may not be
sufficient to accommodate peak seasonal production.
Silo bags
provide farmers with an additional storage option that can be deployed during
harvest periods without requiring the construction of permanent storage
structures. This flexibility allows producers to increase temporary storage
capacity according to seasonal requirements.
The growing use
of combine harvesters and other high-capacity agricultural machinery is also
increasing the volume of crops harvested within shorter periods. As harvesting
becomes more efficient, farmers require storage systems capable of
accommodating large quantities of crops without causing significant
interruptions to harvesting operations.
Silo bags can be
positioned near farms and harvesting areas, reducing the need to immediately
transport crops to centralized storage facilities. This can support more
flexible post-harvest logistics and help farmers manage crop inventories
according to market conditions.
The increasing
scale of commercial farming and agricultural cooperatives is therefore expected
to contribute to continued demand for flexible grain-storage solutions.
Growing
Concern Regarding Post-Harvest Losses Is Supporting Market Expansion
Post-harvest
losses remain an important concern for agricultural producers, particularly in
regions where storage infrastructure is limited or unevenly distributed.
Improperly
stored grains can be exposed to moisture, insects, oxygen, temperature
fluctuations, and other factors that can reduce quality and market value.
Effective storage systems can help farmers protect harvested commodities until
they are ready for sale or processing.
Silo bags
provide an enclosed storage environment that can help limit exposure to
external conditions when the bags are correctly installed, sealed, monitored,
and managed. The controlled storage environment can support preservation of
grain quality during the intended storage period.
The increasing
focus on food security is encouraging governments and agricultural
organizations to improve post-harvest management. Flexible storage systems can
play a role in regions where permanent storage facilities are insufficient or
where farmers need additional seasonal capacity.
Silo bags can
also help producers avoid immediate crop sales during harvest periods when
local supply is high. By creating additional storage capacity, farmers may have
greater flexibility in determining when to market their stored commodities.
These factors
are increasing awareness of flexible grain-storage technologies and supporting
adoption among agricultural producers.
Expansion of
Agricultural Storage Infrastructure and Emerging-Market Adoption Present
Significant Opportunities
The development
of agricultural infrastructure in emerging economies is creating considerable
opportunities for silo bag manufacturers.
Countries with
expanding grain production and insufficient permanent storage capacity can
benefit from flexible storage systems that can be deployed relatively quickly.
Silo bags can supplement existing warehouses, grain elevators, and permanent
silos during peak harvesting seasons.
The technology
is particularly relevant to agricultural regions where producers require
decentralized storage capacity across geographically dispersed farms. Flexible
storage can allow commodities to remain closer to production locations rather
than requiring immediate movement to centralized facilities.
Increasing
investment in food-security programs and agricultural modernization is also
creating opportunities for large-scale deployment. Agricultural cooperatives,
grain traders, livestock producers, and government-supported farming programs
can use silo bags as part of broader post-harvest management strategies.
Technological
improvements represent another opportunity. Manufacturers are developing
stronger multilayer films with enhanced puncture resistance, UV protection,
sealing performance, and barrier properties. Improvements in manufacturing
quality and storage monitoring technologies can further increase confidence in
flexible grain-storage systems.
As agricultural
producers increasingly focus on minimizing post-harvest losses, improving
storage flexibility, and expanding effective capacity without extensive
permanent construction, demand for silo bags is expected to increase.
Silo Bags Market Scope
|
Report Attributes |
Description |
|
Market Size in 2026 |
USD 0.37 Billion |
|
Market Forecast in 2034 |
USD 0.58 Billion |
|
CAGR % 2026-2034 |
5.8% |
|
Base Year |
2025 |
|
Historic Data |
2021-2025 |
|
Forecast Period |
2026-2034 |
|
Report USP |
Production, Consumption,
Company Share, Company Heatmap, Company Production, Service Type, Growth
Factors and more |
|
Segments Covered |
• By Type • By Capacity • By Application |
|
Regional Scope |
● North America |
|
Country Scope |
U.S. |
Silo Bags Market Report Segmentation
Analysis
The global silo
bags market industry analysis is segmented by type, by capacity, by
application, and by region.
The Grain
Silo Bags Segment Is Expected to Dominate the Market During the Forecast Period
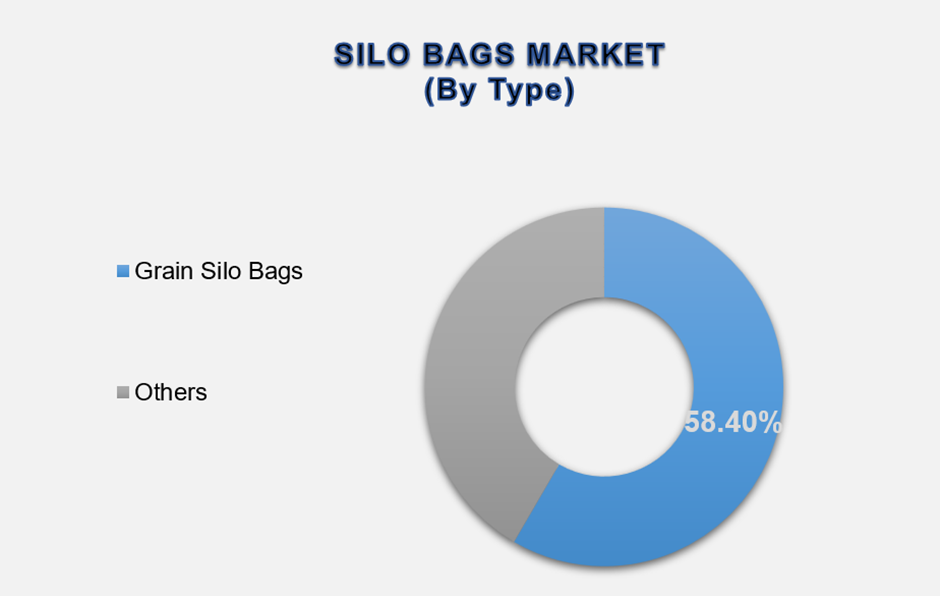
The Grain
Silo Bags segment accounted for approximately 58.4% of the global
market, making it the leading product category.
Grain silo bags
maintain a dominant position because of their extensive use for storing
commodities such as wheat, maize, soybean, barley, and other grains.
These storage
systems allow agricultural producers to create additional capacity during
harvesting seasons and store commodities close to production areas. The
flexible construction of silo bags also allows storage capacity to be expanded
or reduced according to seasonal requirements.
The growing
production of grains and increasing focus on minimizing post-harvest losses are
supporting demand for grain silo bags across major agricultural regions.
Advancements in
multilayer polyethylene films are further improving the strength and durability
of grain storage bags. Better resistance to punctures, environmental exposure,
and handling-related damage is helping manufacturers develop storage solutions suitable
for large-scale agricultural operations.
The Large
Capacity Segment Is Expected to Lead the Market by Capacity
The Large
Capacity segment is expected to hold a leading position in the silo bags
market because commercial farms, agricultural cooperatives, grain traders, and
large-scale producers increasingly require storage systems capable of
accommodating substantial harvest volumes.
Large-capacity
silo bags allow producers to store significant quantities of commodities in a
single flexible storage unit, reducing the need for multiple smaller storage
structures.
The segment
benefits from the expansion of mechanized agriculture and commercial farming
operations, where harvesting volumes can increase rapidly over short periods.
Large-capacity
storage is also particularly useful when permanent storage infrastructure is
temporarily insufficient during peak harvest seasons.
The Grains
Segment Is Expected to Dominate the Market by Application
The Grains
segment represents the largest application area for silo bags due to the
widespread use of flexible storage systems for wheat, maize, soybean, barley,
and other agricultural commodities.
Grain producers
require dependable post-harvest storage to maintain commodity quality and
manage the timing of sales and transportation. Silo bags can provide additional
storage capacity near farms and harvesting locations.
The increasing
production of cereals and oilseeds is expanding the volume of commodities
requiring temporary or supplemental storage. Farmers are also increasingly
seeking storage systems that can be deployed without major permanent
infrastructure investment.
Growing concerns
surrounding post-harvest losses and food security are expected to maintain
strong demand for grain storage solutions through 2034.
The following
segments are part of an in-depth analysis of the global Silo Bags Market:
|
Market Segments |
|
|
By Type |
● Grain Silo Bags ● Silage Silo Bags ● Forage Silo Bags ● Others |
|
By
Capacity |
● Small ● Medium ● Large |
|
By Application |
● Grains ● Maize ● Wheat ● Soybean ● Animal Feed ● Forage ● Others |
Silo Bags Market Share Analysis By
Region
Latin America is expected to maintain a significant position in the global silo
bags market over the forecast period due to the region's large agricultural
production base, extensive grain cultivation, and increasing use of flexible
post-harvest storage technologies.
Argentina is particularly important for silo bag adoption because of its
substantial grain and oilseed production and established use of flexible
grain-storage systems. Brazil is another important market, supported by
large-scale soybean, maize, and other crop production.
The region's
extensive agricultural areas and seasonal harvest volumes create strong
requirements for decentralized storage capacity. Silo bags can provide farmers
and agricultural businesses with additional storage close to production areas.
North America represents a significant market due to its highly mechanized
agricultural sector, large grain production, and established post-harvest
infrastructure. The United States accounts for a major portion of
regional demand, supported by extensive production of maize, wheat, soybean,
and other commodities.
Although North
America has substantial permanent grain-storage infrastructure, flexible silo
bags can provide supplemental capacity during high-yield harvest periods and
support specialized storage requirements.
Europe maintains a substantial market share due to its established
agricultural sector and increasing attention toward efficient post-harvest
management. Germany, France, Italy, Spain, and the U.K. are important
agricultural markets within the region.
Demand is
supported by grain production, livestock farming, forage storage, and the need
for flexible storage capacity among farms and agricultural cooperatives.
Asia Pacific is expected to register steady growth during the forecast period.
The region has a large agricultural population and substantial production of
rice, wheat, maize, soybean, and other crops.
China and
India represent major markets because of their
large agricultural sectors and significant grain production. Increasing
agricultural modernization and investments in post-harvest infrastructure are
creating additional opportunities for flexible storage solutions.
Japan, South
Korea, and Australia also contribute to regional
demand through their developed agricultural industries and adoption of modern
farming and storage technologies.
Middle East
& Africa represents an emerging market for silo
bags. Agricultural modernization, food-security initiatives, increasing grain
production, and the need to reduce post-harvest losses are supporting interest
in flexible storage technologies.
Countries such
as Saudi Arabia, the UAE, and South Africa are expected to provide
opportunities for manufacturers as agricultural producers and food-security
programs increasingly focus on improving storage capabilities.
Silo Bags
Market Competition Landscape Analysis
The silo bags
market is characterized by competition among agricultural film manufacturers,
flexible packaging companies, agricultural storage solution providers, and
specialized silo bag producers.
Companies are
focusing on developing high-strength polyethylene films capable of withstanding
transportation, installation, filling, storage, and unloading requirements.
Film thickness, multilayer construction, puncture resistance, ultraviolet
protection, sealing performance, and durability are important areas of product
differentiation.
Manufacturers
are also focusing on improving the storage performance of silo bags through
better barrier characteristics and film formulations. These improvements can
help maintain the intended storage environment and protect commodities during
the storage period.
Product
customization represents another important competitive strategy. Companies
offer silo bags in different diameters, lengths, capacities, and material
specifications to accommodate varying farm sizes and commodity-storage
requirements.
Geographic
expansion is also important because agricultural production is highly
distributed across regions. Companies with local distribution networks and
technical support capabilities can improve access to farmers and agricultural
cooperatives.
Strategic
partnerships with agricultural distributors, machinery suppliers, cooperatives,
and grain-handling companies can also strengthen market reach.
As agricultural
producers increasingly seek flexible storage capacity and governments focus on
reducing post-harvest losses, manufacturers are expected to continue investing
in stronger materials, improved storage solutions, distribution networks, and
agricultural support services.
Global Silo
Bags Market Recent Developments News
●
In 2026 – Agricultural storage solution providers continued focusing on
higher-strength polyethylene films designed to improve puncture resistance,
durability, and storage performance.
●
In 2026 – Silo bag manufacturers expanded distribution and
technical-support capabilities across major grain-producing regions to meet
growing demand for flexible on-farm storage.
●
In 2025 – Manufacturers increasingly emphasized multilayer film
technologies offering improved mechanical strength and resistance to
environmental exposure.
●
In 2025 – Agricultural organizations and producers continued evaluating
flexible grain-storage systems as supplemental capacity during periods of high
crop production and limited permanent storage availability.
●
In 2025 – Producers expanded the use of flexible storage solutions for
grains, forage, and animal feed as agricultural businesses sought more
adaptable post-harvest management options.
The Global
Silo Bags Market is Dominated by a Few Large Companies, Such As
●
RKW Group
●
Grain Bags International
●
Plastika Kritis S.A.
●
IPESA S.A.
●
Agrinplex
●
BagMan LLC
●
Polywest Ltd.
●
Silo Bag Argentina
●
Bodegueros S.A.
●
Silobolsa
●
GrainPro, Inc.
●
Berry Global Group, Inc.
●
Ab Rani Plast Oy
●
Klerks Plastic Industries
● Others
Frequently Asked Questions
Aishwarya Panbude (Research Analyst)
Aishwarya Panbude is a skilled Research Analyst with 4+ years of experience in market intelligence, consumer insights, competitive analysis, and industry forecasting across the consumer goods, agriculture, and food & beverage sectors. She specializes in market sizing, trend analysis, growth opportunity mapping, and strategic secondary research for global and regional markets.
Her expertise lies in transforming complex industry data into actionable business strategies that help organizations identify emerging trends, understand customer behavior, and gain a competitive edge. With a strong focus on data-driven insights, business intelligence, and future market trends, Jaya delivers high-quality research solutions aligned with evolving industry demands and market dynamics.
1.
Global Silo Bags Market
Introduction and Market Overview
1.1. Objectives of the Study
1.2. Global Silo Bags Market Scope and Market Estimation
1.2.1.
Global Silo Bags Market Size
(US$ Million), Market CAGR (%), Market Forecast (2026 - 2034)
1.2.2.
Global Silo Bags Market Revenue
Share (%) and Growth Rate (Y-o-Y) Analysis (2021 - 2034)
1.3. Market Segmentation
1.3.1.
By Type of Global Silo Bags
Market
1.3.2.
By Capacity of Global Silo Bags
Market
1.3.3.
By Application of Global Silo
Bags Market
1.3.4.
Region of Global Silo Bags
Market
1.4. Competition Coverage List of Market Participants
1.5. Market Definition: Silo Bags Market
2.
Executive Summary
2.1. Demand Side Trends
2.2. Key Market Trends
2.3. Market Demand (US$ Million) Analysis 2021 – 2025 and Forecast, 2026
– 2034
2.4. Demand and Opportunity Assessment
2.5. Key Developments
2.6. Overview of Regulatory Landscape, Compliance Framework, and Industry
Standards
2.7. Market Entry Strategies
2.8. Market Dynamics
2.8.1.
Drivers
2.8.2.
Limitations
2.8.3.
Opportunities
2.8.4.
Impact Analysis of Drivers and
Restraints
2.9. Porter's Five Forces Analysis
2.10.
PEST Analysis
3.
Global Silo Bags Market
Estimates & Historical Trend Analysis (2021 – 2025)
4.
Global Silo Bags Market
Estimates & Forecast Trend Analysis, by Type
4.1. Global Silo Bags Market Revenue (US$ Million) Estimates and
Forecasts, by Type, 2021 - 2034
4.1.1.
Grain Silo Bags
4.1.2.
Silage Silo Bags
4.1.3.
Forage Silo Bags
4.1.4.
Others
5.
Global Silo Bags Market
Estimates & Forecast Trend Analysis, by Capacity
5.1. Global Silo Bags Market Revenue (US$ Million) Estimates and
Forecasts, by Capacity, 2021 - 2034
5.1.1.
Small
5.1.2.
Medium
5.1.3.
Large
6.
Global Silo Bags Market
Estimates & Forecast Trend Analysis, by Application
6.1. Global Silo Bags Market Revenue (US$ Million) Estimates and
Forecasts, by Application, 2021 - 2034
6.1.1.
Grains
6.1.2.
Maize
6.1.3.
Wheat
6.1.4.
Soybean
6.1.5.
Animal Feed
6.1.6.
Forage
6.1.7.
Others
7.
Global Silo Bags Market
Estimates & Forecast Trend Analysis, by Region
7.1. Global Silo Bags Market Revenue (US$ Million) Estimates and
Forecasts, by Region, 2021 - 2034
7.1.1.
North America
7.1.2.
Europe
7.1.3.
Asia Pacific
7.1.4.
Middle East & Africa
7.1.5.
Latin America
8.
North America Silo Bags
Market: Estimates & Forecast Trend Analysis
8.1. North America Silo Bags Market Assessments & Key Findings
8.1.1.
North America Silo Bags Market
Introduction
8.1.2.
North America Silo Bags Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
8.1.2.1.
By Type
8.1.2.2.
By Capacity
8.1.2.3.
By Application
8.1.2.4.
By Country
8.1.2.4.1.
The U.S.
8.1.2.4.2.
Canada
9.
Europe Silo Bags Market:
Estimates & Forecast Trend Analysis
9.1. Europe Silo Bags Market Assessments & Key Findings
9.1.1.
Europe Silo Bags Market
Introduction
9.1.2.
Europe Silo Bags Market Size
Estimates and Forecast (US$ Million) (2021 - 2034)
9.1.2.1.
By Type
9.1.2.2.
By Capacity
9.1.2.3.
By Application
9.1.2.4.
By Country
9.1.2.4.1.
Germany
9.1.2.4.2.
Italy
9.1.2.4.3.
The U.K.
9.1.2.4.4.
France
9.1.2.4.5.
Spain
9.1.2.4.6.
Switzerland
9.1.2.4.7.
Rest of Europe
10. Asia Pacific Silo Bags Market: Estimates & Forecast Trend
Analysis
10.1.
Asia Pacific Silo Bags Market Assessments
& Key Findings
10.1.1.
Asia Pacific Silo Bags Market
Introduction
10.1.2.
Asia Pacific Silo Bags Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
10.1.2.1.
By Type
10.1.2.2.
By Capacity
10.1.2.3.
By Application
10.1.2.4.
By Country
10.1.2.4.1.
China
10.1.2.4.2.
Japan
10.1.2.4.3.
India
10.1.2.4.4.
Australia
10.1.2.4.5.
South Korea
10.1.2.4.6.
Rest of Asia Pacific
11. Middle East & Africa Silo Bags Market: Estimates & Forecast
Trend Analysis
11.1.
Middle East & Africa Silo
Bags Market Assessments & Key Findings
11.1.1.
Middle East & Africa Silo
Bags Market Introduction
11.1.2.
Middle East & Africa Silo
Bags Market Size Estimates and Forecast (US$ Million) (2021 - 2034)
11.1.2.1.
By Type
11.1.2.2.
By Capacity
11.1.2.3.
By Application
11.1.2.4.
By Country
11.1.2.4.1.
UAE
11.1.2.4.2.
Saudi Arabia
11.1.2.4.3.
South Africa
11.1.2.4.4.
Rest of Middle East &
Africa
12. Latin America Silo Bags Market: Estimates & Forecast Trend
Analysis
12.1.
Latin America Silo Bags Market Assessments
& Key Findings
12.1.1.
Latin America Silo Bags Market
Introduction
12.1.2.
Latin America Silo Bags Market
Size Estimates and Forecast (US$ Million) (2021 - 2034)
12.1.2.1.
By Type
12.1.2.2.
By Capacity
12.1.2.3.
By Application
12.1.2.4.
By Country
12.1.2.4.1.
Brazil
12.1.2.4.2.
Mexico
12.1.2.4.3.
Argentina
12.1.2.4.4.
Rest of Latin America
13. Competition Landscape
13.1.
Global Silo Bags Market Product
Mapping
13.2.
Global Silo Bags Market
Concentration Analysis, by Leading Players / Innovators / Emerging Players /
New Entrants
13.3.
Global Silo Bags Market Tier
Structure Analysis
13.4.
Global Silo Bags Market
Concentration & Company Market Shares (%) Analysis, 2026
14. Company Profiles
14.1.
RKW Group
14.1.1.
Company Overview & Key
Stats
14.1.2.
Financial Performance &
KPIs
14.1.3.
Product Portfolio
14.1.4.
SWOT Analysis
14.1.5.
Business Strategy & Recent
Developments
*Similar details would be provided for all
the players mentioned below
14.2.
Grain Bags International
14.3.
Plastika Kritis S.A.
14.4.
IPESA S.A.
14.5.
Agrinplex
14.6.
BagMan LLC
14.7.
Polywest Ltd.
14.8.
Silo Bag Argentina
14.9.
Bodegueros S.A.
14.10.
Silobolsa
14.11.
GrainPro, Inc.
14.12.
Berry Global Group, Inc.
14.13.
Ab Rani Plast Oy
14.14.
Klerks Plastic Industries
14.15.
Others
15. Research Findings & Conclusion
16. Assumptions & Acronyms Used
17. Research Methodology
17.1.
External Databases
17.2.
Internal Proprietary Database
17.3.
Primary Research
17.4.
Secondary Research
17.5.
Assumptions
17.6.
Limitations
17.7.
Report FAQ
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
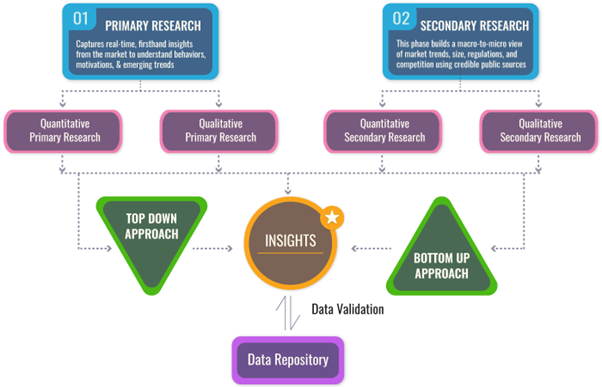
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables