UK Cloud Kitchen Market Size and Forecast (2026–2034), Regional Growth, Trend, Share and Industry Analysis Report Coverage: By Source of Order (Web and Mobile App), By Payment Method (Cash on Delivery, Mobile Wallet, Card Transaction and Others)
2026-09-15
ICT
Ekta Chaurasia (Team Lead)
Description
UK Cloud Kitchen
Market Overview
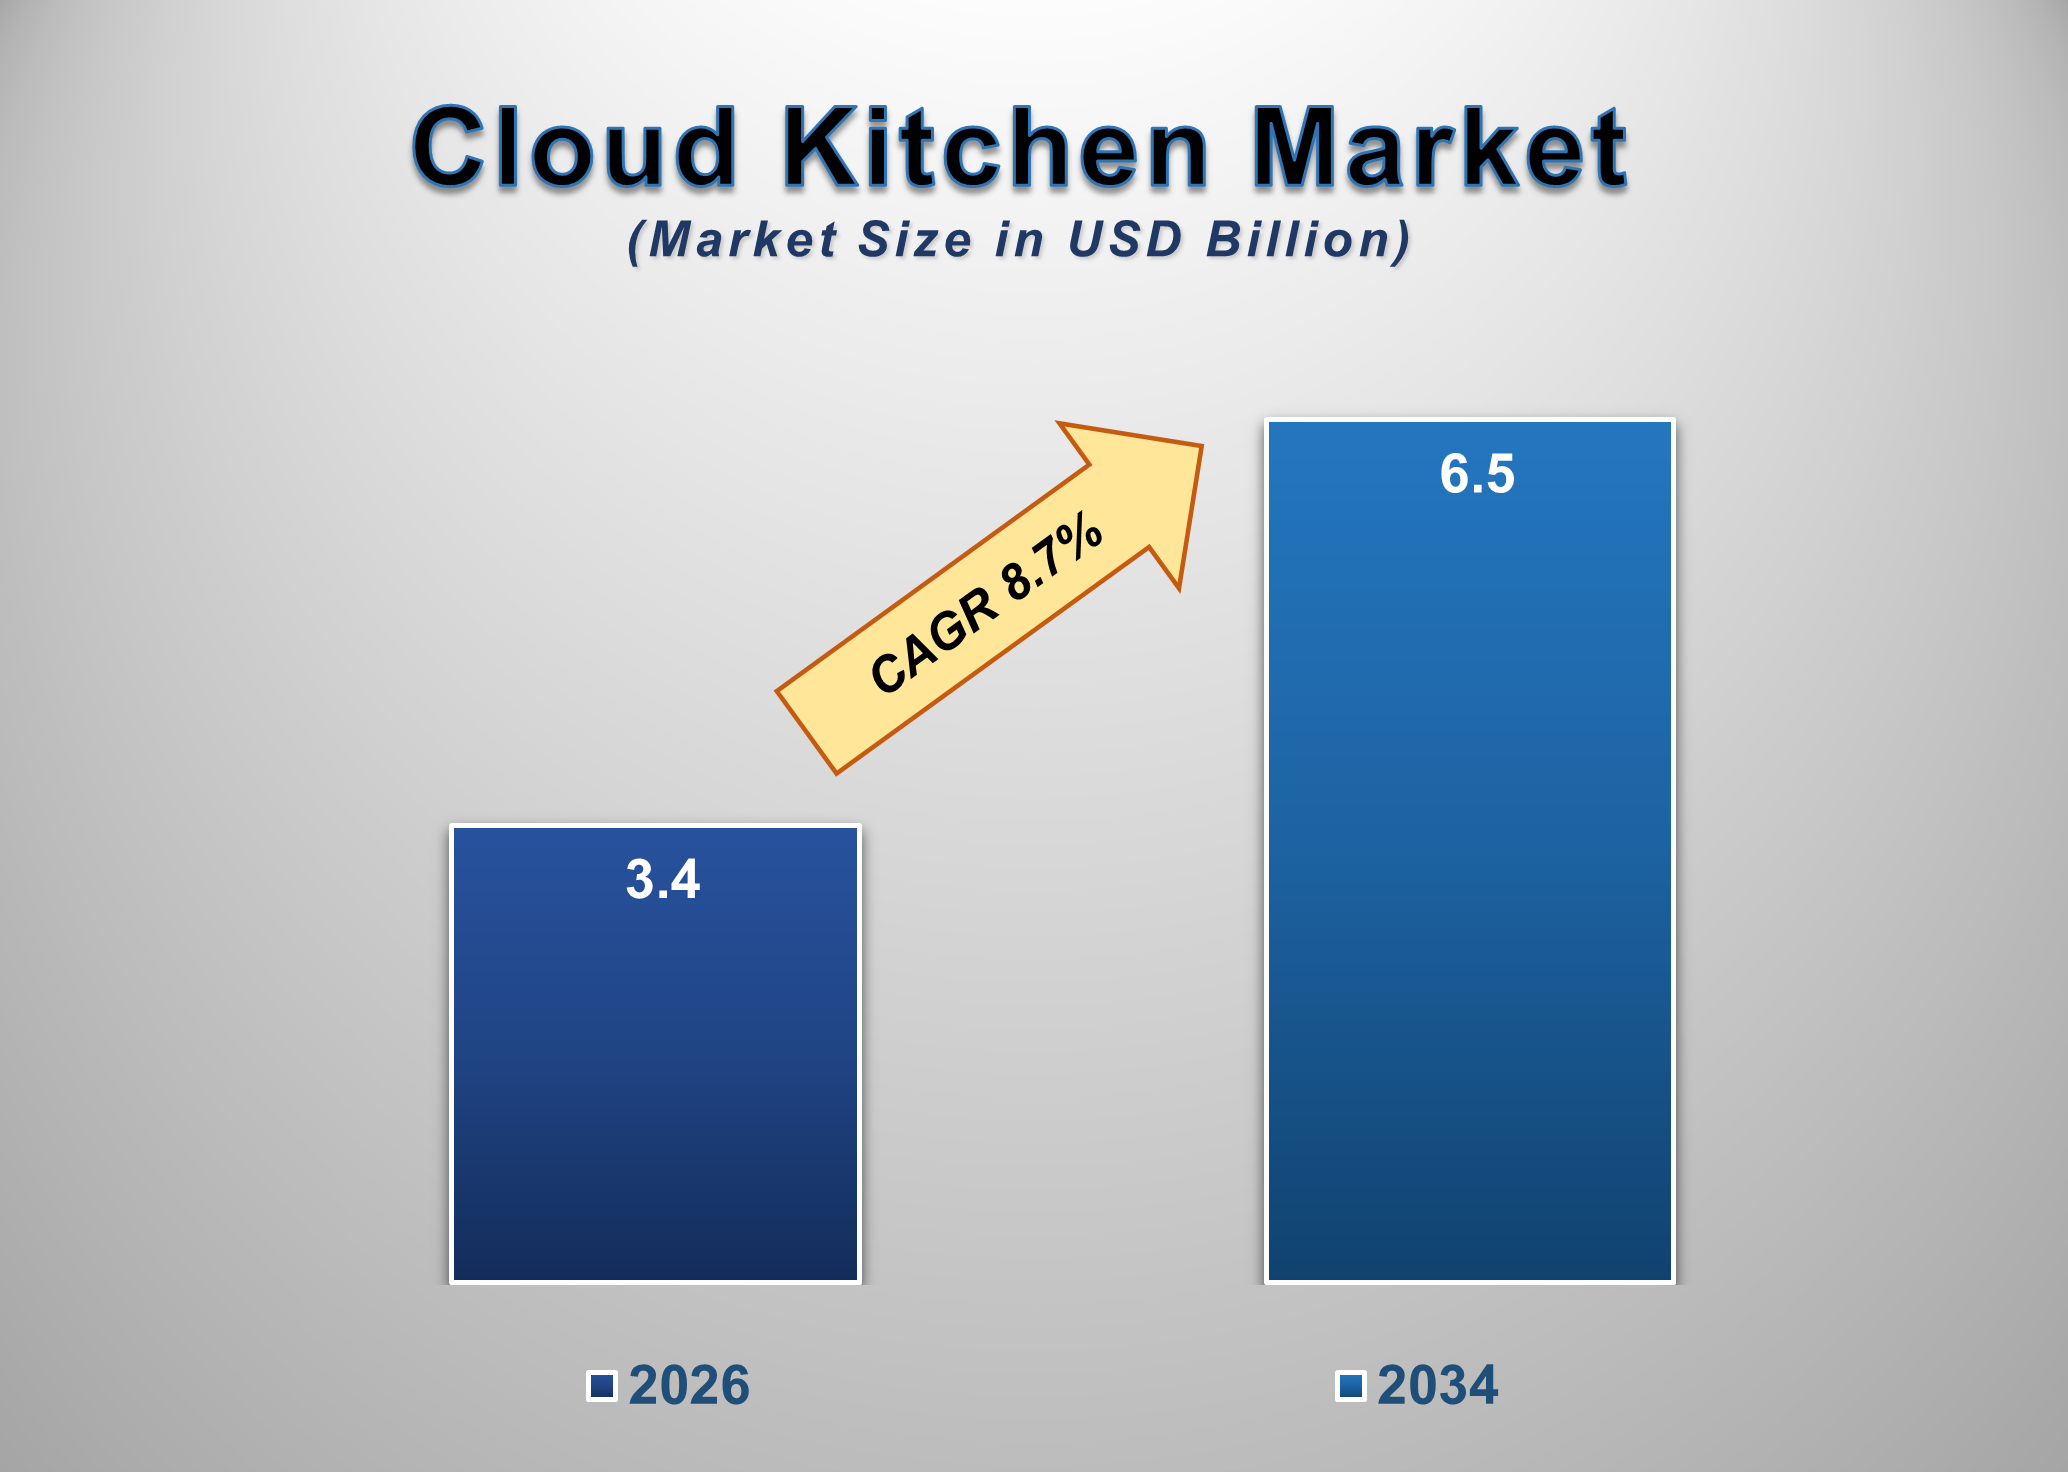
The United Kingdom Cloud Kitchen Market is valued at USD 3.4 billion in 2026 and is projected to reach USD 6.5 billion by 2034, registering a CAGR of 8.7% during the forecast period. The UK represents one of the more developed and distinctive cloud kitchen markets globally, supported by a mature online food-delivery ecosystem, widespread digital ordering, and the growing adoption of delivery-focused foodservice formats. The market has also gained greater institutional and academic recognition, reflecting the increasing importance of dark kitchens within the country's broader foodservice landscape.
A significant development occurred in early 2026 when an NIHR-funded research consortium led by the University of Sheffield, together with several leading UK universities, established an academically agreed definition of a dark kitchen. The research characterized dark kitchens as technology-enabled commercial kitchen facilities primarily designed to fulfill remotely placed, on-demand food orders for immediate consumption. The study also highlighted the growing presence of these facilities across England's major food-delivery platforms, demonstrating that delivery-only food businesses have become an increasingly significant component of the country's digital foodservice ecosystem.
The expansion of cloud kitchens is
being supported by changing consumer preferences for convenience, rapid
delivery, and access to a diverse range of cuisines through digital platforms.
Unlike conventional restaurants, cloud kitchens can operate without large
customer-facing dining areas and can therefore reduce expenditure related to
high-street locations, front-of-house operations, and associated staffing. This
operating model enables foodservice companies to establish smaller,
strategically located production facilities and improve their coverage across
high-demand delivery zones.
The UK's cloud kitchen landscape has
also experienced increasing consolidation and investment activity. In 2025,
US-based DoorDash announced its acquisition of Deliveroo, one of the UK's most
prominent online food-delivery platforms. Deliveroo had played an important
role in developing delivery-focused restaurant infrastructure through
initiatives such as its Editions model, which enabled multiple food brands to
operate from centralized kitchen facilities. The transaction reflects the
strategic importance of the UK food-delivery ecosystem and the continued
interest of international companies in expanding their presence within the
market.
UK
Cloud Kitchen Market Growth Drivers
Increasing Recognition and
Institutional Understanding of Dark Kitchens Is Supporting Market Development
The growing recognition of dark
kitchens by academic institutions, industry stakeholders, and policymakers is
supporting the development of the UK's cloud kitchen market. Research into
delivery-only foodservice models has helped establish a clearer understanding
of how dark kitchens operate and their growing role within the broader
foodservice ecosystem. Greater clarity regarding the definition and
characteristics of these facilities can support more consistent regulation,
inspection, and industry practices. This increasing institutional recognition
also improves the credibility of the cloud kitchen model among investors,
restaurant operators, and other stakeholders. As the sector becomes more
clearly defined and better understood, cloud kitchens are expected to gain
wider acceptance as a long-term component of the UK's evolving foodservice
industry.
International Investment and
Food-Delivery Platform Expansion Are Strengthening Cloud Kitchen Infrastructure
Continued investment and consolidation
within the UK's online food-delivery industry are supporting the development of
cloud kitchens and other delivery-focused foodservice formats. Large
international technology and delivery companies are increasingly investing in
established UK platforms, bringing additional financial resources, technology
capabilities, logistics expertise, and operational scale to the market. This
development can strengthen the wider ecosystem on which cloud kitchens depend,
including digital ordering, delivery networks, customer acquisition, and
data-driven operations. The growing scale of major delivery platforms is also
expected to support the expansion of multi-brand and shared-kitchen concepts,
enabling food businesses to reach consumers more efficiently. Increasing
international participation is therefore contributing to the long-term
development and professionalization of the UK's cloud kitchen ecosystem.
UK Cloud Kitchen Market Restraint
Consumer Trust and Transparency
Concerns May Limit the Adoption of Delivery-Only Food Concepts
Despite the growing popularity of food
delivery, consumer awareness and understanding of dark kitchens remain
relatively limited. Some consumers may be unfamiliar with delivery-only
restaurant concepts and may have concerns regarding food preparation, hygiene,
transparency, and the physical location from which their meals are prepared.
Unlike traditional restaurants, cloud kitchens generally do not provide
consumers with a visible dining space or direct physical interaction with the
foodservice establishment. This can make brand trust, food-safety
communication, customer reviews, and transparency particularly important. In
addition, concerns regarding the reliability of online ratings and reviews can
influence consumer confidence in unfamiliar food brands. Unless operators
effectively address these transparency and trust-related concerns, consumer
hesitation may continue to create challenges for the wider adoption of cloud
kitchen concepts.
UK Cloud Kitchen Market Opportunities
A Competitive Multi-Platform Delivery
Ecosystem Creates Greater Market Access for Cloud Kitchen Operators
The presence of multiple established
food-delivery platforms in the United Kingdom provides cloud kitchen operators
with several channels for accessing consumers. Rather than depending entirely
on a single marketplace, operators can distribute their offerings across
multiple platforms and expand their customer reach. A multi-platform approach
can help reduce dependence on individual delivery providers while improving
visibility and access to different consumer segments. Competition among
delivery platforms can also encourage continued investment in technology,
logistics, customer experience, and restaurant partnerships. For cloud kitchen
businesses, the ability to maintain relationships across multiple digital
marketplaces offers greater operational flexibility and can support a more
diversified customer-acquisition strategy.
Improving Transparency and Food-Safety
Communication Represents a Significant Opportunity for Brand Differentiation
Increasing consumer interest in food
quality, hygiene, and transparency presents a significant opportunity for cloud
kitchen operators to differentiate their brands. Businesses that clearly
communicate where and how food is prepared can strengthen consumer confidence
in delivery-only concepts. Prominently displaying food hygiene ratings,
certifications, quality-control procedures, and food-safety practices can help
address concerns associated with the limited physical visibility of cloud
kitchens. Operators can also use digital channels, social media, and online
content to provide greater insight into kitchen operations and food preparation
processes. As consumers become increasingly conscious of food safety and brand
authenticity, proactive transparency can become an important competitive
advantage and support stronger customer loyalty within the UK's cloud kitchen
market.
UK Cloud Kitchen Market Scope
|
Report
Attributes |
Description |
|
Market Size |
USD 3.4
Billion (2026) |
|
Market Forecast |
USD
6.5 Billion (2034) |
|
CAGR % |
8.7% |
|
Base Year |
2025 |
|
Historic
Data |
2020–2025 |
|
Forecast Period |
2026–2034 |
|
Report USP |
Production,
Consumption, company share, company heatmap, company production capacity,
growth factors and more |
|
Geography |
U.K. |
|
By Source of
Order |
Web, Mobile
App |
|
By Payment Method |
Cash
on Delivery, Mobile Wallet, Card Transaction, Others |
|
Key Players |
Deliveroo
plc Karma
Kitchen Foodstars Kbox Global Taster Sessions
Market Dephna Group Encore
Kitchens Rebel Foods Kitopi CloudKitchens The Kitchen
Cloud |
UK Cloud Kitchen Market Report Segmentation
Analysis
Mobile App Ordering Leads, Supported
by the UK's App-Based Food-Delivery Ecosystem
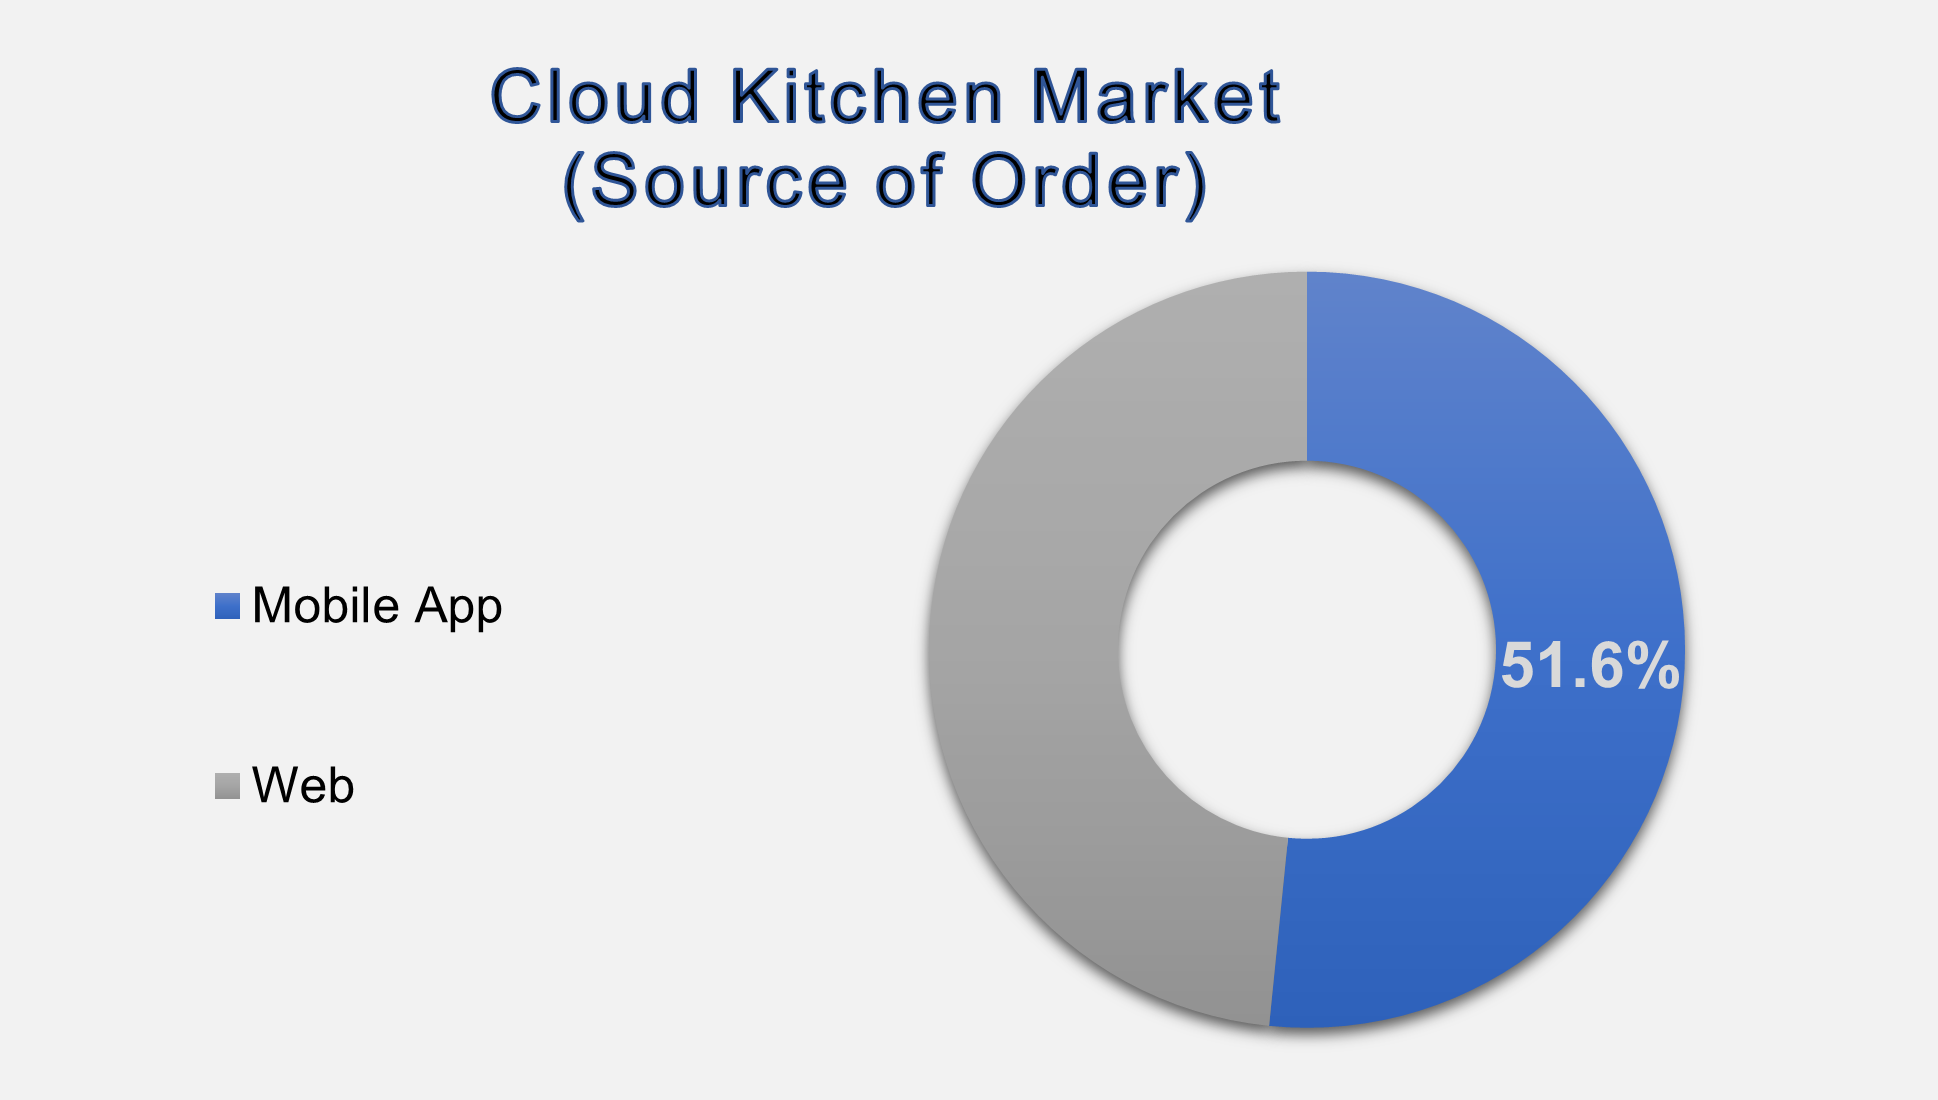
By source of order, the market is
segmented into Web and Mobile App. Mobile app ordering holds the leading
position in the UK cloud kitchen market, supported by the widespread use of smartphones
and the app-first operating models of major food-delivery platforms. Mobile
applications provide consumers with convenient access to restaurant listings,
menus, customer reviews, promotional offers, real-time delivery tracking, and
integrated payment options. These features make mobile applications the
preferred channel for discovering and ordering from both established
restaurants and delivery-only food brands. Web-based ordering remains relevant
through browser platforms and restaurant-owned websites; however, the
convenience and functionality offered by mobile applications continue to
support their dominant position.
Card and Digital Payment Methods Dominate as Online Food Ordering Continues to
Expand
By payment method, the market is
segmented into Cash on Delivery, Mobile Wallet, Card Transaction, and Others.
Card transactions and integrated digital payment methods account for a
significant share of online food-delivery purchases in the United Kingdom. The
country's well-developed digital payments infrastructure enables consumers to
complete transactions quickly through delivery applications and online ordering
platforms. Mobile wallets and other digital payment solutions are also gaining
traction, supported by the increasing integration of contactless and app-based
payment technologies. Although online food ordering represents only a portion
of overall consumer food expenditure, the continued expansion of digital
commerce and changing preferences for convenience provide substantial
opportunities for further growth in delivery-based foodservice. As consumers
increasingly adopt digital channels for food purchases, electronic payment
methods are expected to remain central to the expansion of the UK cloud kitchen
market.
The
following segments are part of an in-depth analysis of the U.K. Cloud Kitchen
Market:
|
Market Segments |
|
|
By
Source of Order |
· Web
· Mobile
App |
|
By
Payment Method |
· Cash
on Delivery · Mobile
Wallet · Card
Transaction · Others |
United Kingdom Cloud Kitchen Market
Regulatory Landscape
Cloud kitchens in the United Kingdom
are subject to the same fundamental food safety, hygiene, registration, and labeling
requirements that apply to other commercial foodservice establishments.
Operators must comply with applicable Food Standards Agency (FSA) requirements
and local authority regulations relating to food handling, hygiene standards,
allergen management, food traceability, and consumer information. Food
businesses are also subject to inspection and hygiene-rating requirements,
while Scotland operates its own food safety and regulatory framework through
the relevant national authorities.
The regulatory environment surrounding
dark kitchens is continuing to evolve as the delivery-only foodservice model
becomes more established. Increasing academic and institutional attention has
contributed to a clearer understanding of dark kitchens and their operating
characteristics. The development of more consistent definitions and
classifications can support improved regulatory oversight, inspection
procedures, and communication between foodservice operators, delivery
platforms, and regulatory authorities. Greater clarity is particularly
important because cloud kitchens often operate without the physical visibility
associated with conventional restaurants.
U.K. Cloud Kitchen Market Competition
Landscape Analysis
The UK cloud kitchen competitive
landscape is increasingly shaped by consolidation within the online
food-delivery industry and heightened regulatory attention toward digital
platform practices, rather than competition solely among dedicated kitchen-space
providers. Deliveroo, operating under the DoorDash Group, Just Eat Takeaway.com
N.V., Uber Eats UK, and DoorDash, Inc. represent key participants in the
broader ecosystem supporting cloud kitchens and delivery-only food brands.
Deliveroo (DoorDash Group)
Deliveroo has historically been one of
the UK's leading online food-delivery platforms and a significant contributor
to the development of delivery-focused foodservice infrastructure. The company
was acquired by DoorDash in a transaction announced in May 2025, with the
business valued at approximately USD 3.0 billion. The acquisition strengthened
Deliveroo's access to DoorDash's international technology, logistics, and
operational capabilities while maintaining its established presence in the UK
market. Deliveroo's Editions format remains one of the most widely recognized
dark-kitchen operating models, enabling multiple food brands to operate through
centralized, delivery-focused kitchen facilities.
Just Eat Takeaway.com N.V.
Just Eat Takeaway.com N.V. remains a
major participant in the UK online food-delivery market and an important
demand-generation platform for restaurants and cloud kitchen operators. The
company provides digital ordering, customer access, payment integration, and
delivery-related services across its platform. Regulatory scrutiny of online
business practices, including the management of consumer reviews and ratings,
has increased the importance of transparency and consumer protection across the
digital food-delivery ecosystem. Such developments may influence platform
operating practices and the way delivery-only food businesses manage their
online presence and customer engagement.
Uber Eats UK
Uber Eats UK is another major
food-delivery platform and serves as an important digital channel for
restaurants, virtual brands, and cloud kitchen operators. The platform supports
customer discovery, online ordering, payment processing, and delivery fulfillment,
allowing delivery-only food businesses to access a large consumer base. Its
presence alongside other major platforms contributes to a competitive
multi-platform environment, enabling cloud kitchen operators to diversify their
customer acquisition and distribution strategies.
DoorDash, Inc.
DoorDash, Inc. has strengthened its
strategic position in the UK food-delivery market through the acquisition of
Deliveroo. The transaction provides DoorDash with an established platform and
customer base in one of Europe's major food-delivery markets while bringing
additional international technology and logistics capabilities to Deliveroo's
operations. The acquisition also reflects the growing consolidation of the
global food-delivery industry. Going forward, the integration of major delivery
platforms and continued regulatory oversight of competition and digital market
practices are expected to influence the competitive environment for cloud
kitchens and delivery-only foodservice operators in the United Kingdom.
U.K. Cloud
Kitchen Market Recent Developments News:
·
February 2026: An NIHR-funded academic
research consortium led by the University of Sheffield, in collaboration with
several UK universities, published the country's first academically agreed
definition of a dark kitchen. The research also highlighted the growing
importance of delivery-only foodservice models within England's online food
ecosystem.
·
March 2026: The Competition and Markets
Authority (CMA) initiated a formal investigation into several UK companies,
including a major food-delivery platform, concerning suspected fake or
misleading online reviews. The investigation reflects increasing regulatory
scrutiny of digital consumer information, online ratings, and review practices
under the UK's evolving consumer protection framework.
·
May 2025: DoorDash announced its acquisition
of Deliveroo in a transaction valued at approximately USD 3.7 billion. The
acquisition represented a major consolidation development within the UK
food-delivery industry and strengthened the role of international delivery
companies in the country's digital foodservice ecosystem.
·
December 2025: UK retail data indicated that
internet-based food sales continued to represent a meaningful but comparatively
smaller portion of overall food spending. The continued growth and
stabilization of online purchasing highlight further opportunities for digital
food ordering and delivery-focused foodservice models, including cloud
kitchens.
The
U.K. Cloud Kitchen Market is dominated by a few large companies, such
as
·
Deliveroo plc (Deliveroo Editions)
·
Karma Kitchen
·
Foodstars
·
Kbox Global
·
Taster
·
Sessions Market
·
Dephna Group
·
Encore Kitchens
·
Rebel Foods
·
Kitopi
·
CloudKitchens
·
The Kitchen Cloud
· Others
Frequently Asked Questions
Ekta Chaurasia (Team Lead)
Ekta Chaurasia is a highly experienced Team Lead at M2Square Consultancy with over 7 years of expertise in market research, strategic consulting, competitive benchmarking, and business intelligence solutions. She specializes in ICT, semiconductors & electronics, automotive & transportation, and industrial machinery markets.
She leads end-to-end global research projects focused on market trends, industry analysis, growth forecasting, customer insights, and strategic decision-making. Known for her analytical leadership and industry expertise, Ekta helps businesses uncover growth opportunities, evaluate competitive landscapes, and stay ahead in rapidly evolving markets through accurate and insight-driven research.
Test
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
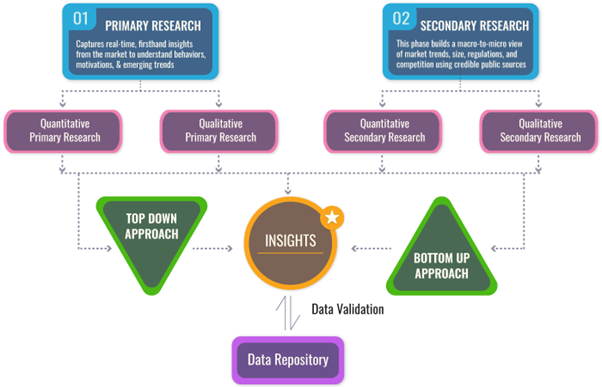
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables