United States Biochip Market Size and Forecast (2026–2034), Regional Growth, Trend, Share and Industry Analysis Report Coverage: By Type (DNA Chips, Protein Chips, Lab-on-a-Chip (LOC), Cell Arrays, Others); By Product (Consumables, Instruments, Software and Services); By Application (Disease Diagnostics, Drug Discovery and Development, Genomics, Agricultural Biotechnology, Others); By End User (Biotechnology and Pharmaceutical Companies, Hospitals and Diagnostic Centers, Academic and Research Institutes, Others)
2026-11-18
Healthcare
Swetal (Research Analyst)
Description
United States Biochip Market Overview
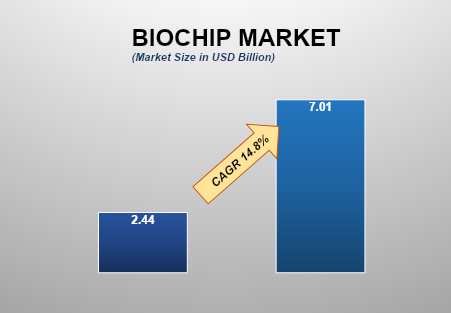
The United States biochip market is projected to expand from USD 2.44 billion in 2026 to USD 7.01 billion by 2034, registering a CAGR of 14.8% during 2026–2034. Drivers of the US biochip market include the presence of a developed biotechnology and pharmaceutical industry, a well-developed health care infrastructure, and significant investments made in genomics, proteomics, and molecular diagnostics research. The increased use of DNA chips, protein chips, lab-on-a-chip systems, and cell arrays helps in the application of these products in the areas of disease diagnostics, drug discovery and development, genetic profiling, and personalized medicine. Biotechnology and pharmaceutical companies constitute one of the important demand pools, which is due to the increasing need for high-throughput screening, biomarker discovery, target validation, and drug development. An increased adoption of biochip technologies in hospitals and diagnostic centers for improving diagnostics, reducing sample volume, and faster clinical testing is observed. Technological innovations in the fields of microfluidics, automation, and miniaturization of analytical platforms, along with an increasing demand for point-of-care testing and precision medicine, are opening up new business prospects. The presence of large companies like Agilent Technologies, Illumina, Thermo Fisher Scientific, and Bio-Rad Laboratories creates a competitive market environment.
United States Biochip Market Growth Drivers
Increasing Demand for Precision Medicine and Molecular Diagnostics
Precision medicine and molecular diagnostics are increasingly gaining popularity in the United States. As a result, demand is growing for cutting-edge biochip technologies that can detect genetic variations, identify molecular biomarkers, and analyze biological samples with high precision. The increasing preference for personalized medicine is making healthcare facilities, diagnostic laboratories, and biotech firms embrace DNA chips, protein chips, and lab-on-a-chip platforms for gene expression profiling, genetic testing, disease detection, and biomarker analysis. Increasing demand for disease diagnosis in the early stages, especially in oncology, infectious diseases, and inherited genetic disorders, is increasing the demand for technologies that allow for multiplexing of biological targets with reduced sample consumption and testing times. Biochips are also being used to integrate genomics and proteomics information in clinical research and drug development. This helps pharmaceutical companies to understand the underlying mechanisms of diseases and explore potential treatment pathways. With the emergence of precision healthcare in the US healthcare system, demand for high-throughput, miniaturized, and application-specific biochips is expected to increase further.
Increasing Pharmaceutical R&D and Drug Discovery Investments
Rising investments in pharmaceutical research and development (R&D) activities in oncology, immunotherapy, and targeted treatments are fueling the growing demand for sophisticated biochip technologies in the U.S. Pharmaceutical and biotech firms are growing their drug discovery initiatives and clinical development pipelines, thereby generating increasing demand for high-throughput screening, molecular profiling, biomarker discovery, gene expression studies, and drug response assessment. Biochips such as DNA microarrays, protein arrays, cell-based biochips, and microfluidic systems help researchers analyze several biological targets at once, increase efficiency of experiments, and decrease sample and reagent usage in early-stage drug development. This investment trend can be seen in the third-quarter 2026 financial performance of BioNTech, which reported total year-to-date R&D expenditure of €1,856.1 million, as compared to €1,599.5 million in the same period in 2025. The company cited the rise as mainly due to increased development expenses related to its late-stage immuno-oncology and antibody-drug conjugate programs. BioNTech also launched five global clinical trials for its investigational oncology drug candidate in 2026.
United States Biochip Market Restraint
High Development Costs and Technical Complexity of Biochip Technologies
Higher costs incurred in the development and manufacturing of the biochips continue to be one of the major factors restraining the growth of the market in the United States. Biochips require specialized skills and heavy investment in microfabrication, microfluidics, surface functionalization, biomaterial integration, and sophisticated analytical tools. High quality control and reproducibility are essential aspects in their development, especially when applied in the diagnosis, discovery of drugs, and molecular analysis. In addition, incorporation of biological parts in electronic, optical, or fluidic systems further increases design complexity. As a result, testing, calibration, and validation are necessary prior to commercial use of the product. This makes the advanced biochip platform unattainable for small biotech firms, research laboratories, and diagnostic centers due to budget constraints. Moreover, there might arise compatibility issues with other instruments, supplies, and software used in analysis. Higher cost involved in the development and manufacturing process can result in delays in commercialization of products. It can also hinder the adoption of the technology by cost-sensitive customers and the entry of new manufacturers in the US biochip market.
United States Biochip Market Opportunities
Expansion of Organ-on-a-Chip and Advanced Microfluidic Platforms
The continuous innovation and development in the field of organ-on-a-chip technology and advanced microfluidics technology is creating numerous opportunities in the United States Biochip Market, especially in areas such as pharmaceutical research, drug discovery, and pre-clinical safety testing. The technologies mimic certain functionality of the organs in the lab environment, allowing researchers to test how drugs react to these models along with various disease mechanisms. Due to the increase in demand to find alternatives to animal testing as well as making pre-clinical testing more accurate, the pharma and biotech organizations are finding interest in these platforms. The opportunity is further emphasized by the news released by Emulate, Inc. on 9th September 2026, stating that they have submitted a complete package for their Human Liver-Chip under the FDA's ISTAND Program. The submission contained the performance metrics of both the Zoë Culture Module and the AVA Emulation System, proving reproducibility in three independent laboratories, the ability to identify different compounds by their respective liver toxicity profiles, as well as scalability to as many as 96 independent Organ-Chip samples per run. Regardless of whether FDA qualification is attached or not, it’s an important step toward making organ-on-a-chip technology a standard tool for drug development. Thus, manufacturers of biochip devices can now expand their portfolios of organ-specific chips, microfluidics, integrated sensors, automated testing systems, as well as consumables and business partnerships with pharmaceutical companies and other research institutions.
United States Biochip Market Scope
United States Biochip Market Report Segmentation Analysis
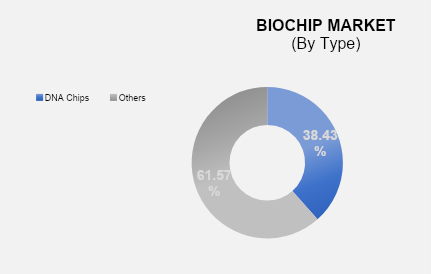
DNA Chips Segment Is Expected to Dominate the United States Biochip Market During the Forecast Period
The submission contained the performance metrics of both the Zoë Culture Module and the AVA Emulation System, proving reproducibility in three independent laboratories, the ability to identify different compounds by their respective liver toxicity profiles, as well as scalability to as many as 96 independent Organ-Chip samples per run. Regardless of whether FDA qualification is attached or not, it’s an important step toward making organ-on-a-chip technology a standard tool for drug development. Thus, manufacturers of biochip devices can now expand their portfolios of organ-specific chips, microfluidics, integrated sensors, automated testing systems, as well as consumables and business partnerships with pharmaceutical companies and other research institutions. The focus of the collaboration is to create methods for producing antibiotic-free products, as well as improving the scalability, efficiency, and cost-effectiveness of producing pDNA sequences. WACKER has also designated its facility in San Diego, which contains fermentation lines that can handle up to 650 liters of pDNA, as a possible site for contract manufacturing once its functionality is well-established. Despite being about pDNA production only, this announcement points to the growth of the US nucleic acid biotechnology sector, which creates favorable market conditions for the rise of demand for advanced products in this area.
Consumables Segment Is Expected to Dominate the United States Biochip Market During the Forecast Period
According to predictions, the Consumables segment of the Biochip Market in the United States will be the largest market segment, given the frequent usage of reagents, assay kits, microarray slides, sample prep materials, cartridges, and other disposable items used for biochip testing. Contrary to instruments that are bought and termed as capital goods and used for several years, consumables must be bought repeatedly for each new experiment, diagnostic test, or sample processing cycle. The increasing use of DNA chips, protein chips, and lab-on-chip technologies in genomics, molecular diagnostics, drug discovery, and pharmaceuticals leads therefore to a continuous demand for their products. The increased installed base of the biochip instruments promotes the sales of consumables as well, since many laboratories still use the reagents and materials specific to the platforms for the sake of reproducibility and efficiency of the testing processes. This proposal of recurring revenue is also evident in Bio-Rad Laboratories’ 2025 annual report as this report states that introduced procedures for laboratory operations and facilities are resultant for multiple purchases of test kits and consumables, whenever testing is carried out. Similarly, QIAGEN also reported growing sales in 2025 in multiple product areas, due to increased demand for automated kits and other consumables. In conclusion, it can be said that increasing the use of biochips for research and diagnostics will continue to promote recurring purchases and strong ties between suppliers and clients.
Disease Diagnostics Segment Is Expected to Dominate the United States Biochip Market During the Forecast Period
It is anticipated that the disease diagnostics category is set to capture a large share of its designated market in the United States due to heightened need for early detection of illnesses and advancements in molecular test development, genetic diagnosis, and individualized treatment procedures. Biochip technologies allow for analyzing multiple genetic sequences, proteins, and disease-indicating substances in tiny samples of patients, thereby enabling diagnosis of complicated diseases including cancers, infectious diseases, and genetic disorders. The ability of biochip technologies to simplify operations, enhance test efficiency, and produce informative molecular profiles increases the incentives for hospitals, testing laboratories, and clinical testing facilities to apply these technologies. The continuing use of companion diagnostics has also helped boost the demand because targeted cancer treatments, in their majority, necessitate biomarker testing to enable the detection of patients who are likely to get the maximum benefits from such procedures. Developing precision medicine and pharmacogenomic testing should also facilitate the usage of DNA chips, protein chips, and microfluidic platforms in clinical practices. Thus, increasing focus on precise diagnoses, timely diagnosis, and personalization in medicine should benefit the standing of the disease diagnostics segment.
Biotechnology and Pharmaceutical Companies Segment Is Expected to Dominate the United States Biochip Market During the Forecast Period
In terms of the United States biochip market, the biotechnology and pharmaceutical companies segment is likely to lead this market due to improved investments in drug discovery, genomics, molecular profiling, and advanced therapeutics. These companies serve as one of the important end-user sectors of biochip technologies, with various biochip applications including DNA chips, protein chips, cell arrays, and lab-on-chip methods for different tasks such as high-throughput screening, biomarker identification, gene expression analysis, target validation, and drug response evaluation. The increase in complexity of pharmaceutical market pipelines, especially in such specific areas as oncology, biologics, gene therapies, and personalized medicine, has given rise to the demand for advanced analytical platforms helping to facilitate research activities as well as improve the quality of both experiments and the drug development process. As per the SelectUSA program of the US Department of Commerce, the amount of money spent on R&D by biopharmaceutical companies was approximately US$104 billion in 2024, which indicates the scale of investment in the therapy industry. This is because companies need to obtain biochip instruments, consumables, and other technologies for their research and development work. Thus, the increase in drug development processes, precision medicine, and investments in biotechnology research will lead to the solid position of the aforementioned end-user segment in the future.
The following segments are part of an in-depth analysis of the United States Biochip Market:
United States Biochip Market Competition Landscape Analysis
The market for biochips in the United States consists of well-known companies in life science technology, as well as some specialized biochip industry players. Those companies compete for profits in the fields of DNA microarrays, protein analysis technologies, lab-on-a-chip, as well as things like cell-based arrays and integrated diagnostics. One of the main motivations for these companies to compete with each other is the need for reforms in the products offered to clients as well as technological differences, accuracy of analysis performed, compatibility of the platforms employed for providing their services, as well as being able to offer integrated systems that include instruments, consumables, etc. Major players in the biochip market such as Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Illumina, Inc., Bio-Rad Laboratories, Inc., Abbott Laboratories, Revvity, Inc., and Standard BioTools Inc. derive advantages from the life science portfolios they have, extensive distribution networks, as well as good connections with such partners as pharmaceutical companies, hospitals, and research centers. Market players are constantly concentrating on high-capacity, miniaturized, and automated platforms, extended consumables, and integrated technologies for maximizing research efficiency, enhancing client engagement, and obtaining recurrent revenues. Partnerships, product launches, and technology developments contribute to the expansion of portfolios and strengthening of competitiveness. Generally, the market is formed by a combination of diversified life science companies with a competitive edge in terms of scale and distribution opportunities, and specialized firms competing with the help of industry-related innovations; however, the lack of consistent biomolecular information leads to unrealistic concentration numbers.
United States Biochip Market Recent Developments News:
In September 2026, Emulate, Inc. submitted a full qualification package for its Human Liver-Chip to the US FDA's Innovative Science and Technology Approaches for New Drugs (ISTAND) program. The submission seeks qualification of the platform as a Drug Development Tool for assessing drug-induced liver injury, highlighting progress toward regulatory acceptance of organ-on-a-chip technologies in pharmaceutical safety testing.
In April 2026, Agilent Technologies, Inc. launched the BioTek Cytation 9 multimode reader, combining cell imaging and microplate reading capabilities to support cell-based assays, high-content analysis, and drug discovery workflows. The development reflects increasing integration of imaging and analytical technologies to improve the efficiency of biological research.
The United States Biochip Market is dominated by a few large companies, such as
Agilent Technologies, Inc.
Thermo Fisher Scientific Inc.
Illumina, Inc.
Standard BioTools Inc.
Bio-Rad Laboratories, Inc.
Revvity, Inc.
10x Genomics, Inc.
Abbott Laboratories
Bio-Techne Corporation
BioChain Institute Inc.
US Biomax, Inc.
RayBiotech, Inc.
LC Sciences, LLC
Arrayit Corporation
Axion BioSystems, Inc.
Baebies, Inc.
ALine, Inc.
LightDeck Diagnostics, Inc.
NanoCellect Biomedical, Inc.
Meso Scale Diagnostics, LLC
Other Prominent Players
Frequently Asked Questions
Swetal (Research Analyst)
Swetal is a Research Analyst with 4+ years of experience specializing in healthcare market research, medical devices, healthcare IT, and medical technology industry analysis. Her expertise includes competitive intelligence, secondary research, market trend forecasting, and healthcare business insights across global healthcare ecosystems.
She contributes to advanced market research reports by analyzing regulatory frameworks, emerging healthcare technologies, competitive landscapes, and innovation trends shaping the medical industry. With a strong focus on accurate market intelligence, strategic insights, and healthcare industry trends, Swetal supports businesses in making informed, data-backed decisions in a rapidly transforming healthcare environment.
United States Biochip Market Introduction and Market Overview
Objectives of the Study
Market Segmentation
Type of the United States Biochip Market
Products of the United States Biochip Market
Application of the United States Biochip Market
End User of the United States Biochip Market
Competition Coverage List of Market Participants
Market Definition: Biochip Market
Executive Summary
United States Biochip Market Estimation & Forecast
United States Biochip Market Size (US$ Million) Estimates & Historical Trend Analysis (2021 - 2025)
United States Peptide Cancer Vaccine Overall Market Size (US$ Million), Growth Rate (Y-o-Y), Market CAGR (%), Market Forecast (2026 - 2034)
Snapshot of United States Biochip Market
United States Biochip Market Revenue Share (%) 2025
Key Competitors & Key Insights
Market Overview (Qualitative Analysis)
Demand Side Trends
Supply Side Trends / Manufacturing Trends
Demand and Opportunity Assessment, 2026 - 2034
Market Dynamics
Drivers
Limitations
Opportunities
Impact Analysis of Drivers and Restraints
Key Developments
Regulatory Landscape
Pricing Analysis
Supply Chain Analysis
Porter’s Five Forces Analysis
Bargaining Power of Suppliers
Bargaining Power of Buyers
Threat of Substitutes
Threat of New Entrants
Competitive Rivalry
PEST Analysis
Political Factors
Economic Factors
Social Factors
Technology Factors
United States Biochip Market Estimates & Forecast Trend Analysis, by Type
United States Biochip Market Assessments & Key Findings, by Type
United States Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Type, 2021 - 2034
Protein Chips
Lab-on-a-Chip (LOC)
Cell Arrays
Others
United States Biochip Market Estimates & Forecast Trend Analysis, by Product
United States Biochip Market Assessments & Key Findings, by Product
United States Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Product, 2021 - 2034
Consumables
Instruments
Software and Services
United States Biochip Market Estimates & Forecast Trend Analysis, by Application
United States Biochip Market Assessments & Key Findings, by Application
United States Biochip Market Revenue (US$ Million) Estimates and Forecasts, by Application, 2021 - 2034
Disease Diagnostics
Drug Discovery and Development
Genomics
Agricultural Biotechnology
Others
United States Biochip Market Estimates & Forecast Trend Analysis, by End User
United States Biochip Market Assessments & Key Findings, by End User
United States Biochip Market Revenue (US$ Million) Estimates and Forecasts, by End User, 2021 - 2034
Biotechnology and Pharmaceutical Companies
Hospitals and Diagnostic Center
Academic and Research Institutes
Others
Competition Landscape
United States Biochip Market Product Mapping
United States Biochip Market Concentration Analysis, by Leading Players / Innovators / Emerging Players / New Entrants
United States Biochip Market Tier Structure Analysis
United States Biochip Market Concentration & Company Market Shares (%) Analysis, 2025
Company Profiles
Agilent Technologies, Inc.
Company Overview & Key Stats
Financial Performance & KPIs
Product Portfolio
SWOT Analysis
Business Strategy & Recent Developments
* Similar details would be provided for all the players mentioned below
Thermo Fisher Scientific Inc.
Illumina, Inc.
Standard BioTools Inc.
Bio-Rad Laboratories, Inc.
Revvity, Inc.
10x Genomics, Inc.
Abbott Laboratories
Bio-Techne Corporation
BioChain Institute Inc.
US Biomax, Inc.
RayBiotech, Inc.
LC Sciences, LLC
Arrayit Corporation
Axion BioSystems, Inc.
Baebies, Inc.
ALine, Inc.
LightDeck Diagnostics, Inc.
NanoCellect Biomedical, Inc.
Meso Scale Diagnostics, LLC
Other Prominent Players
Research Findings & Conclusion
Assumptions & Acronyms Used
Research Methodology
External Transportation / Databases
Internal Proprietary Database
Primary Research
Secondary Research
Assumptions
Limitations
Report FAQs
Our Research Methodology
"Insight without rigor is just noise."
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
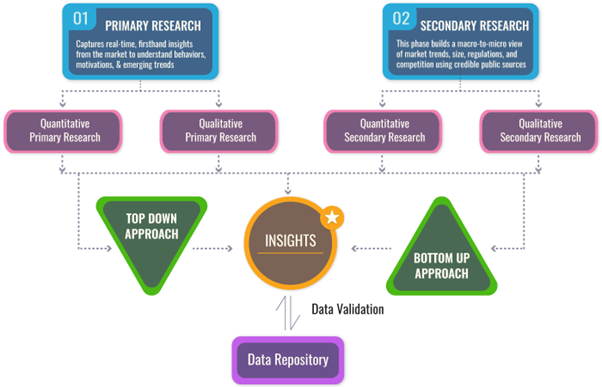
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables